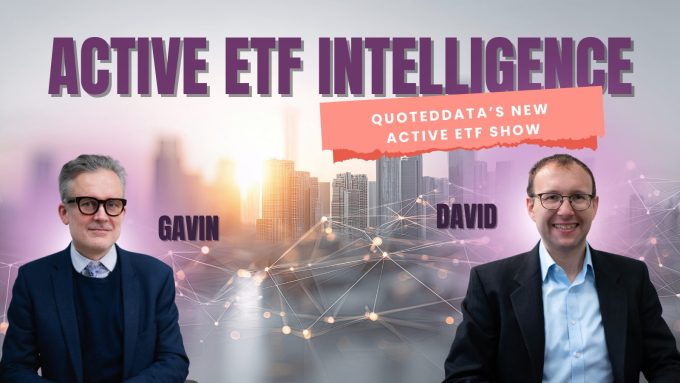
The next stage in QuotedData’s evolving coverage of the European active ETF market begins next Wednesday, 4 March, with the launch of our new weekly live show, Active ETF Intelligence. Each week, Gavin Lumsden, our head of news, and I will explore the latest developments in the market, aiming to make what can often feel like an impenetrable world of acronyms and jargon, a little easier to understand. I thought this column would be a good opportunity to preview some of the topics I plan to cover in the early episodes – and to invite suggestions from curious readers on what they would most like us to tackle.
The show will be live here at 11am on Wednesday.
How active are active ETFs?
An obvious starting point is the considerable variation in how much genuine active management is actually deployed within active ETFs.
At one end of the spectrum sit the largest products in the market, often described as “enhanced index”, “systematic active” or – my preferred term – “index plus”. These are benchmark-aware strategies designed to deliver returns close to the index, while aiming to eke out a modest degree of outperformance on top.
This can be achieved in a variety of ways: using quantitative overlays, factor investing or a tightly defined qualitative framework. Costs are typically low, and while individual managers may be named, they are often responsible for several vehicles, implementing a set of pre-defined and repeatable rules. This segment of the market is currently dominated by JPMorgan’s Research Enhanced range.
An increasingly popular subset of the “index plus” universe is funds that incorporate a pre-defined options strategy. The most common of these is the covered call, where a fund will hold a portfolio of equities that closely match an index, and then sell call options on that index. Investors in the fund benefit both from the additional income stream from selling the options, and lower overall volatility, but at the cost of partially capping their upside in strong markets.
Can the small become mighty?
In contrast to “index plus” giants, the smaller end of the market contains many more strategies that would be viewed as genuinely active. These funds are often built around a particular theme – examples of funds focused on US equities include Harbor Health Care (ticker WELL) and US Global Investors Travel (ticker TRIP) – and have named managers who have the discretion to construct their portfolios as they see fit, often without any reference to a benchmark.
One of the topics I am particularly keen to explore in the show – alongside the pressing question of whether a witty ticker is now compulsory – is whether this part of the market can truly achieve scale, or is it destined to remain relatively niche. At present, many of these funds operate through a “white label” structure, where a third-party provider supplies an existing regulatory umbrella, infrastructure and operational platform, allowing portfolio managers to focus on investment decisions rather than the mechanics of running an ETF. This lowers the barriers to entry and has undoubtedly encouraged innovation. The open question is whether that democratisation of access will translate into durable asset growth – or simply a proliferation of small, specialist products serving a narrow but loyal client base.
Is there such a thing as too much transparency?
Another area I would like to talk about is transparency, which is particularly topical at present. Traditionally, ETFs have been required to disclose their full portfolio holdings on a daily basis. For passives strategies, this presents little difficulty: if you are tracking an index, there is no intellectual property to protect. However, for genuinely active ETFs, this level of disclosure raises two concerns.
First, there is the issue of protecting intellectual property, specifically the manager’s proprietary research and portfolio construction decisions. A manager running a differentiated strategy may be understandably reluctant to show competitors their workings in real time.
Second, there is the practical risk of the front-running of strategies. This is especially relevant in less liquid areas such as small-caps funds, where building and exiting positions can take days or even weeks to complete. In response to these concerns, the Central Bank of Ireland (CBI) – the regulator of Europe’s largest ETF domicile – moved last year to permit ETF issuers to publish their holdings just once per quarter, with a 30-day lag, rather than daily. This month, the number two market, Luxembourg, followed suit with a similar framework. So far, take-up from providers has been modest, suggesting investors still value transparency or providers are reluctant to deviate from the long-established model, so it will be interesting to see what impact this change has on the market over time.
Will JPMorgan continue to dominate?
At QuotedData, we’ve always been keen to engage with difficult topics, and so I feel compelled to talk about the elephant in the room within the European active ETF space, namely, the dominance of one name: JPMorgan. As at the end of 2025, its assets of $43.1bn dwarfed those of its nearest competitors and accounted for roughly 45% of the entire European active ETF market.
This scale is no accident. JPMorgan made a serious commitment to the active ETF structure while it was still niche. This, paired with the strength of its existing distribution network across the continent, gave it a powerful first mover advantage, allowing it to seed products effectively and gather assets at pace.
JPMorgan is not resting on its laurels either. It continues to launch new products – most recently the Europe Equity Premium Income Active ETF, building on the success of its income-oriented and research-enhanced ranges. A growing number of asset managers – from global houses to boutiques – have entered the space over the past two years. Increased regulatory flexibility, improving adviser familiarity and shifting client demand have all lowered the barriers to entry. Watching how the competitive landscape unfolds could turn out to be one of the most fascinating aspects of the European active ETF story.
Is the sky the limit?
This leads me nicely to the last of my topic previews – just how high is the ceiling for European active ETFs? Lest we forget, this is a product that originated across the pond, and in the US the ceiling seems to be very high indeed. There, active ETFs have amassed total assets of $1.6 trillion, or roughly 17 times the current level in Europe. However, part of the US success rests on structural advantages that do not translate perfectly across the Atlantic.
In America, the mechanism for creating and redeeming shares “in kind” allows an ETF to transfer securities rather than sell them. This helps avoid realising capital gains within the portfolio, meaning fewer gains are distributed than in mutual funds, with investors instead mainly taxed when selling individual shares in the fund. This feature has been a powerful selling point for advisers and end investors alike.
In Europe, this is not a problem to be solved, with most fund vehicles not facing the same issue of taxable gains being crystallised through their management. There is one specific tax advantage of ETF investing in the UK: the absence (for Irish and Luxembourg-domiciled funds) of the 0.5% stamp duty charged on the purchase of any share in a UK company or investment trust. This should provide some support to growth but the broader question remains: can the growth of European active ETFs be sustained without the specific tax advantages that exist in the US.
Join us each Wednesday for the latest in European active ETFs
Finally, do join us each Wednesday as we delve into the ever-evolving world of active ETFs. We’ll be exploring all of the themes outlined above – and plenty more besides – with the aim of cutting through the jargon, challenging assumptions and, above all, making sense of this fast-moving corner of the market together.