
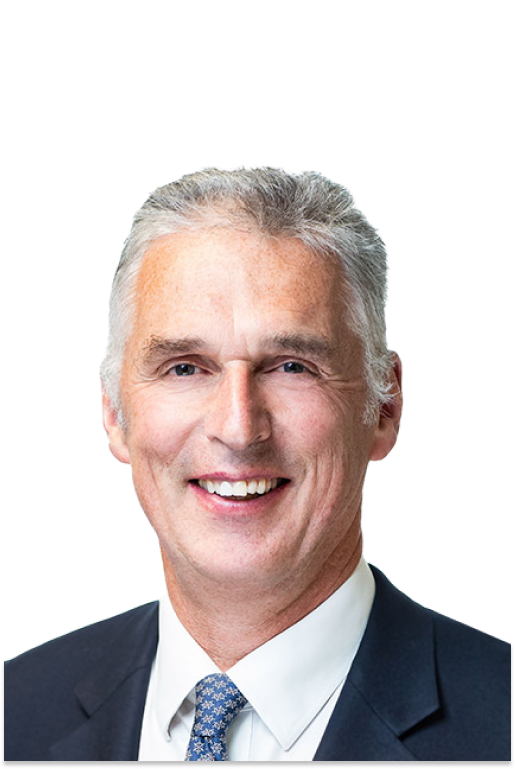
Valhalla, the investment vehicle of Preqin founder Mark O’Hare (pictured), has increased its stake in HgCapital (HGT) from 7.2% to 8% as shares in the £1.9bn software focused private equity trust continue to struggle over concerns about the impact of artificial intelligence (AI) on its companies.
Valhalla bought over 3.9m shares last Thursday to take its total to nearly 36.9m. Since then the shares have fallen from 449.5p to 428.5p valuing its total stake at around £158m. This leaves them nearly 24% below net asset value (NAV) compared to an 8.6% average discount of the past year.
As we reported, Valhalla first bought in on 10 February after HGT plunged from 507p at the end of January to 380p on 4 February. After recovering to 472p last week after fund manager Hg expressed confidence in its companies’ ability to adjust, they have retreated again. Investec reversed its earlier upgrade of HGT to “buy” with a “hold” that reflected the initial rebound in the shares and the risk of write-downs to NAV if falls in listed software providers feed through to its private companies.
Yesterday saw US software stocks fall, with IBM tumbling 13%, after Anthropic said its Claude Code tool could be used to modernise legacy computer systems that run on COBOL. US financial stocks were also weakened when a bearish report by Citrini Research on the implications of AI for employment and the economy was widely circulated.
Our view
Matthew Read, senior analyst at QuotedData, said: “Valhalla Ventures continuing to edge up its stake in HgCapital Trust is certainly eye-catching, but it does little to address HGT’s underlying challenges. Investors remain uncertain about what agentic AI could mean for the traditional software businesses that dominate the portfolio. That uncertainty is unlikely to fade quickly and may keep the trust’s discount wider than shareholders have been accustomed to for some time.
“Against this backdrop, talk of a potential IPO for Visma looks ambitious. Public market appetite for large software floats appears limited, and pricing expectations may yet need to adjust. If software multiples continue to compress, NAV momentum could stall or even reverse. Investment company investors know that a widening or persistent discount combined with falling NAV is an uncomfortable mix. It may be that long-term conviction buyers, who need to build meaningful positions, are simply moving early. Equally, they may just be able to afford to take a braver stance than most.”
Stay a step ahead. Our daily newsletter brings you the latest on investment trusts and active ETFs. Subscribe here.
