
The healthcare sector has picked up strongly over recent months as a significant beneficiary of the rotation out of crowded trades in AI and technology. We believe the mid to long-term trend is also much improved for healthcare as investors start to appreciate a variety of drivers which could support outperformance.
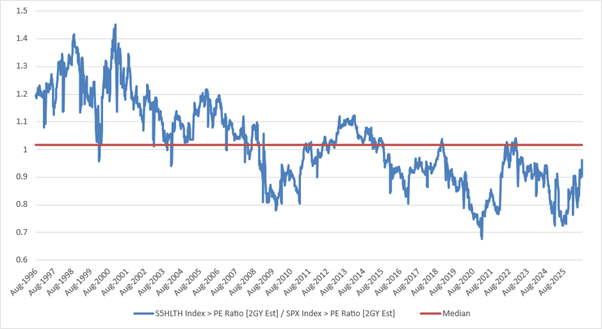
The sector has had an indifferent start to the year but recent performance has been strong with the sector trading on undemanding valuations, a statement underpinned by the relative price-to-earnings ratio (P/E) which is at a discount to the US market.
Healthcare sector’s relative P/E at a discount
Healthcare is seeing positive earnings revisions for 2027 compared to 2026 when the opposite is true for the broader market. This is largely driven by continuing growth in weight-loss and diabetes medicines (GLP-1s) and a recovery in managed care. The Q2 earnings season, so far, has been positive in terms of surprises and upwards revisions to consensus estimates.
Positive momentum
We also see three near-term catalysts to support the sector’s recovery.
The first is innovation, the pace of which continues to accelerate. So far in 2026, there have been 33[1] novel drugs approved by the US Food and Drug Administration (FDA1). This compares to 46 new drugs approved over the course of 2025.
In our view, one of the greatest unmet medical needs is improved access to and delivery of care across the globe. At the same time, the associated budgets – whether government, employer or consumer – are increasingly strained. This is likely to ensure the healthcare marketplace will be a prime beneficiary of new technologies that can not only add value to patients but also drive efficiencies.
The second catalyst is consolidation. Many large pharmaceutical and biotechnology companies will likely turn to mergers and acquisitions (M&A) to bolster pipelines in the hope of sustaining revenue growth as over the next decade some very profitable drugs will lose patent protection. M&A has continued apace since the start of 2026, with a number of significant deals struck at attractive premiums. Recent examples include GSK’s $10.6bn acquisition of oncology company Nuvalent and AbbVie’s $10.9bn acquisition of Apogee Therapeutics.
The third catalyst is increasing utilisation. Healthcare utilisation is experiencing a sustained and meaningful uplift globally. Much of this is driven by demographics as the baby boomer generation reaches 75, the peak age for using healthcare. Evolving patient behaviour is another factor, as well as the continued clearing of pandemic-era backlogs and waiting lists. This is supporting revenue and profit growth across companies in a range of subsectors including healthcare distribution, equipment and facilities.
US elections
Looking beyond dynamics in the sector, another reason for near-term optimism is the approach of the mid-term elections in the US. In the second year of a US presidential cycle, the healthcare sector typically outperforms. The reason in theory is that the market anticipates mid-term results typically going against the incumbent president and the resulting gridlock in Congress means less risk of any adverse policies being passed.
This year’s rebound is slightly lagging the average over the past 50 years but is heading towards the trend level.
The Trust’s positioning
Against this background, the Polar Capital Global Healthcare Trust has broad-based sector exposure. We invest across the market-cap spectrum and see real value in many different subsectors which means we can and do take a highly diversified approach.
The Trust currently has high exposure to biotechnology because of the new product cycles and potential for M&A. It also has a large allocation to healthcare services, specifically diversified US services companies including healthcare insurance, pharmacy benefit and physical pharmacy assets.
Given the strong earnings season, ongoing positive pipeline news flow and the breadth of opportunities we are seeing across a number of healthcare subsectors, we remain optimistic that the recent improved performance in the sector could continue.
Polar Capital Healthcare Team
19 August 2026
Polar Capital Global Healthcare Trust plc (the “Company”)
The Company is an investment company with investment trust status and its shares are excluded from the Financial Conduct Authority’s (“FCA”) restrictions on the promotion of non-mainstream investment products. The Company conducts its affairs, and intends to continue to conduct its affairs, so that the exemption will apply.
The Company is an Alternative Investment Fund under the EU’s Alternative Investment Fund Managers Directive 2011/61/EU as it forms part of UK law by virtue of the European Union (Withdrawal) Act 2018.
The Investment Manager
Polar Capital LLP is the investment manager of the Company (the “Investment Manager”). The Investment Manager is authorised and regulated by the FCA and is a registered investment adviser with the United States’ Securities and Exchange Commission.
Key Risks
- Investors’ capital is at risk and there is no guarantee the Company will achieve its objective.
- Past performance is not a reliable guide to future performance.
- The value of investments may go down as well as up.
- Investors might get back less than they originally invested.
- The value of an investment’s assets may be affected by a variety of uncertainties such as (but not limited to): (i) international political developments; (ii) market sentiment; and (iii) economic conditions.
- The shares of the Company may trade at a discount or a premium to Net Asset Value.
- The Company may use derivatives which carry the risk of reduced liquidity, substantial loss and increased volatility in adverse market conditions.
- The Company invests in assets denominated in currencies other than the Company’s base currency and changes in exchange rates may have a negative impact on the value of the Company’s investments.
- The Company invests in a concentrated number of companies based in one sector. This focused strategy can lead to significant losses. The Company may be less diversified than other investment companies.
- The Company may invest in emerging markets where there is a greater risk of volatility than developed economies, for example due to political and economic uncertainties and restrictions on foreign investment. Emerging markets are typically less liquid than developed economies which may result in large price movements to the Company.
Important Information
This document is not an offer to buy or sell or a solicitation of an offer to buy or sell any security, and under no circumstances is it to be construed as a prospectus or an advertisement. This document does not constitute, and may not be used for the purposes of, an offer of the securities of, or any interests in, the Company by any person in any jurisdiction in which such offer or invitation is not authorised.
Information subject to change:
Any opinions expressed in this document may change.
Not Investment Advice:
This document does not contain information material to the investment objectives or financial needs of the recipient. This document is not advice on legal, taxation or investment matters. Prospective investors must rely on their own examination of the consequences of an investment in the Company. Investors are advised to consult their own professional advisers concerning the investment.
No reliance:
No reliance should be placed upon the contents of this document by any person for any purposes whatsoever. None of the Company, the Investment Manager or any of their respective affiliates accepts any responsibility for providing any investor with access to additional information, for revising or for correcting any inaccuracy in this document.
Performance and Holdings:
All data is as at the document date unless indicated otherwise. Company holdings and performance are likely to have changed since the report date. Company information is provided by the Investment Manager.
Benchmark:
The Company is actively managed and uses the MSCI All Country World Index/Healthcare as a performance target. The benchmark is considered to be representative of the investment universe in which the Company invests. The performance of the Company is likely to differ from the performance of the benchmark as the holdings, weightings and asset allocation will be different. Investors should carefully consider these differences when making comparisons. Further information about the benchmark can be found at: www.msci.com.
Third-party Data
Some information contained in this document has been obtained from third party sources and has not been independently verified. Neither the Company nor any other party involved in compiling, computing or creating the data makes any warranties or representations with respect to such data, and all such parties expressly disclaim all warranties of originality, accuracy, completeness, merchantability or fitness for a particular purpose with respect to any data contained within this document.
Country Specific Disclaimers
United States
The information contained within this document does not constitute or form a part of any offer to sell or issue, or the solicitation of any offer to purchase, subscribe for or otherwise acquire, any securities in the United States or in any jurisdiction in which such an offer or solicitation would be unlawful. The Company has not been and will not be registered under the United States Investment Company Act of 1940, as amended (the “Investment Company Act”) and, as such, the holders of its shares will not be entitled to the benefits of the Investment Company Act. In addition, the offer and sale of the Securities have not been, and will not be, registered under the U.S. Securities Act of 1933, as amended (the “Securities Act”). No Securities may be offered or sold or otherwise transacted within the United States or to, or for the account or benefit of U.S. Persons (as defined in Regulation S of the Securities Act). In connection with the transaction referred to in this document the shares of the Company will be offered and sold only outside the United States to, and for the account or benefit of non-U.S. Persons in “offshore transactions” within the meaning of, and in reliance on the exemption from registration provided by Regulation S under the Securities Act. No money, securities or other consideration is being solicited and, if sent in response to the information contained in this document, will not be accepted. Any failure to comply with the above restrictions may constitute a violation of such securities laws.
Further Information about the Company
Investment in the Company is an investment in the shares of the Company and not in the underlying investments of the Company. Further information about the Company and any risks can be found in the Company’s Key Information Document, the Annual Report and Financial Statements and the Investor Disclosure Document which are available on the Company’s website, found at: https://www.polarcapitalglobalhealthcaretrust.co.uk
