
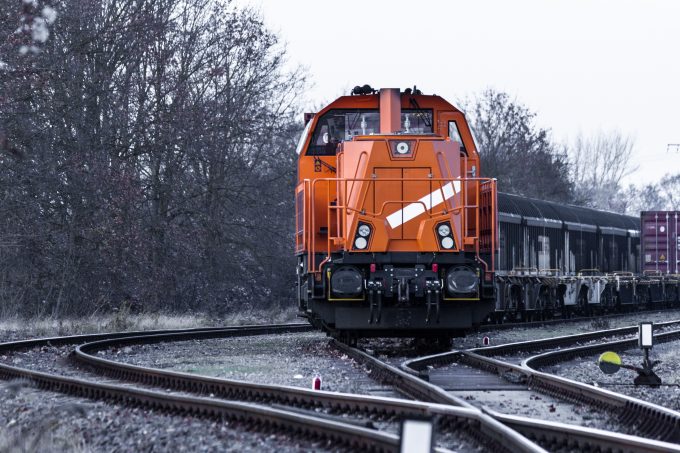
HICL Infrastructure (HICL) has unveiled its first “enhancer” investment designed to boost shareholder returns, ploughing £68m into Hector Rail, the largest private rail freight operator in Scandinavia.
The £2.5bn investment company is investing some of its cash resources in the Stockholm-based company alongside other InfraRed-managed funds which together will buy 100% of Hector Rail from Ancala, an infrastructure fund manager in London.
The transaction is expected to complete at the end of the year when the investment will represent around 2.3% of HICL’s portfolio. HICL is eventually targeting having 20% of its assets in higher-return investments.
Founded in 2004, Hector Rail has expanded to operate across Sweden, Norway, Denmark and Germany, serving what HICL said was a diversified base of blue-chip industrial customers in timber, intermodal freight and energy.
“Customer relationships are deep and long-standing, with the five largest customers by revenue having an average relationship tenure of more than 16 years,” HICL said.
Hector Rail employs 400 people, including 300 train drivers and operates a fleet of 100 locomotives, around 75% of which are electric.
HICL said the business was well positioned for “substantial expansion”, driven by long-term demand from existing and new customers for efficient, lower-carbon freight transport.
Revenues had increased by around 7% a year since 2021 with clear scope for continued growth given the supportive policy backdrop for rail freight in the region which should spur a further switch in commercial traffic from road to rail.
Edward Hunt, head of core income funds at InfraRed, said the new investment was an “important milestone” after the company outlined in July its target of increasing total investment returns to over 10% a year. “Hector Rail is a high-quality infrastructure business with a strong position in the Scandinavian rail freight market, supported by clear opportunities for value creation. The investment demonstrates HICL’s disciplined approach to selectively enhancing returns for shareholders while remaining focused on essential infrastructure.”
HICL shares rose 0.5% to 134.2p in early trading. They ended last week on around a 17% discount to net asset value.
Our view
Matthew Read, senior analyst at QuotedData, said: “Hector Rail is an interesting first outing for HICL’s new Enhancer strategy. This is clearly a different proposition from the availability-based PPP assets on which HICL built its reputation, with returns more dependent on growing the business and improving its operations. However, there is plenty to like: long-standing customers, inflation-linked multi-year contracts, significant barriers to entry and structural support from the shift of freight from road to rail.
“Importantly, HICL says the prospective return is materially higher than that available from buying back its own shares. That is the hurdle any new investment needs to clear while HICL trades at a discount. The £68m commitment is also modest at around 2.3% of the portfolio, giving InfraRed scope to demonstrate that Enhancers can lift returns without materially changing HICL’s overall risk profile. If Hector Rail can deliver the double-digit EBITDA growth being targeted, it should make a useful contribution towards HICL’s new 10%+ medium-term return ambition.”
