
Ready for a growth revival
Montanaro European Smaller Companies (MTE) is a growth-focused European smaller companies fund. It has faced strong headwinds in recent years as value investing has been more popular in Europe and elsewhere. Earlier this year, performance was hurt by a sell-off in software shares as investors weighed the potential impact of agentic artificial intelligence. More recently, MTE’s performance has recovered, for reasons set out in this note, and the manager remains optimistic.
Steps announced by the board last year have had early success in supporting shareholder value. The second 5% tender offer has just completed, and the trust’s share price discount to net asset value (NAV) has traded in single figures for over a year, in line with MTE’s discount policy.
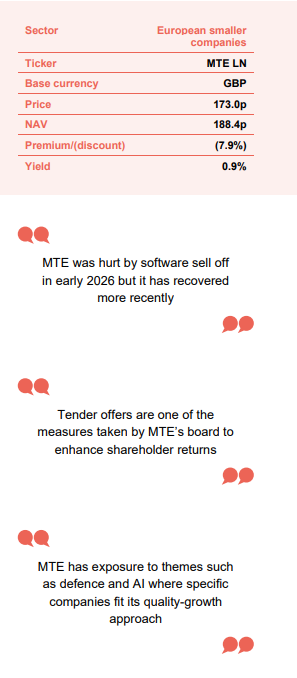
Continental European smaller companies
MTE aims to deliver capital growth by investing mainly in quoted smaller companies in Continental Europe. Its benchmark is the MSCI Europe ex UK Small Cap Index, in sterling terms.
At a glance
Share price and discount
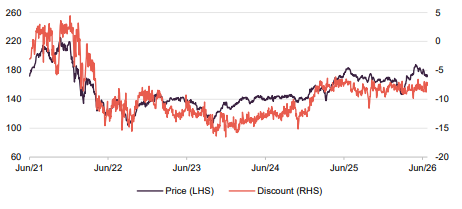
Over the 12 months to the end of June 2026, MTE’s shares traded within a range of a 7.3% to an 8.7% discount to NAV, with an average discount of 8.1%. As at 22 July 2026, the shares were trading on a discount of 7.9%. MTE’s discount to NAV has almost continuously been in single figures for more than a year, following the introduction of a more active discount-control policy by the board.
Time period 30 June 2021 to 22 July 2026
Performance over five years
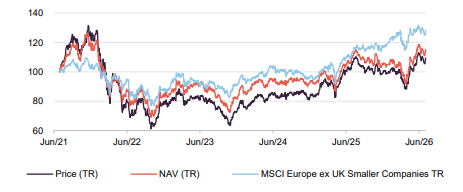
Over the past five years, MTE’s NAV total return has been behind its benchmark, the MSCI Europe ex UK Small Cap Index. Performance was held back by the sharp rotation away from growth companies in 2022 and, more recently, by concerns about the impact of AI on software businesses. Since the end of March, performance has been ahead of the index.
Time period 30 June 2021 to 22 July 2026
| Year ended | Share price total return(%) | NAV total return(%) | MSCI Europe ex UK small cap TR. (%) | MSCI Europe ex UK TR(%) |
|---|---|---|---|---|
| 30/06/22 | (29.9) | (22.0) | (16.5) | (9.8) |
| 30/06/23 | 16.8 | 14.7 | 9.2 | 20.1 |
| 28/06/24 | 0.3 | 2.2 | 9.1 | 12.9 |
| 30/06/25 | 28.5 | 20.1 | 13.3 | 9.8 |
| 30/06/26 | 0.8 | 2.3 | 11.4 | 22.7 |
Fund profile
More information is available from the manager’s website www.montanaro.co.uk
MTE aims to deliver capital growth by mainly investing in smaller listed companies in continental Europe, including the European Union, Norway and Switzerland. It can also invest in smaller companies listed on other European stock exchanges. Its benchmark is the MSCI Europe ex UK Small Cap Index, in sterling terms.
The trust was originally launched in 1981. Montanaro Asset Management Limited took over management in September 2006, when the current European small-cap approach began.
The manager
MAML was established in 1991 and has around £2.5bn of assets under management. Charles Montanaro and his family own 65% of the business. The CEO, Cédric Durant des Aulnois, owns 5%, with the remaining 30% owned by staff through an employee benefit trust established in 2025.
Lead manager of MTE is George Cooke, supported by Stefan Fischerfeier.
The chief investment officer and lead fund manager of MTE is George Cooke, with Stefan Fischerfeier as his deputy. Charles and George sit on the investment committee alongside Alex Magni, Adam Montanaro and Guido Dacie-Lombardo. MAML also owns around 10.8% of MTE’s outstanding shares, excluding treasury shares, having increased its holding in April 2025.
MAML has one of the UK’s largest specialist teams focused on quoted smaller companies. The team is multi-lingual and international, and all but three fund managers also carry out research. Montanaro’s managers believe the firm works best with no more than around 40 staff, helping it keep the benefits of a boutique business. With £2.5bn of assets under management as at 31 December 2025 and an established range of UK, European and global equity strategies, Montanaro plans to focus on supporting and developing its existing offering rather than growing its assets under management.
Alongside MTE, Montanaro manages UK and European equity funds, the Montanaro Better World Fund, an open-ended fund investing in small- and midcap companies that support the UN Sustainable Development Goals, and two global equity funds.
Board update
Gordon Neilly became MTE’s chairman on 1 January 2026, replacing Richard Curling. He had already been on the board for over five years. Neilly has wide experience in investment management, having been chief of staff at Standard Life Aberdeen, global head of strategy at Aberdeen Standard Investments and joint chief executive of Cantor Fitzgerald. He is also a non-executive director of Personal Assets Trust.
The change represents continuity rather than a shift in the trust’s strategy, as Neilly was already on the board when the current buyback and tender-offer policies were developed (see below).
The board has three independent non-executive directors: Gordon Neilly as chair, Caroline Roxburgh as senior independent director and audit committee chair, and Hillary Williams as remuneration committee chair.
Tender offer
Tender offers are one of the measures taken by the board to enhance shareholder returns.
As covered in our last note (which can be read here), in March 2025 MTE’s board announced several initiatives to improve the trust’s appeal to shareholders. These included a more active share buyback policy, lower management fees and twice-yearly tender offers, aimed at improving liquidity.
The first tender offer, completed in November 2025, received valid tenders for 29,792,053 shares, or 20.5% of issued share capital excluding treasury shares. As this exceeded the 5% maximum, shareholders tendering up to their basic entitlement were bought in full, while those tendering more were scaled back.
Six-monthly 5% tender offers at a 5% discount to NAV.
The second tender offer has now closed. Eligible shareholders could again tender up to 5% of their holding, with the price set at a 5% discount to the NAV per share on the calculation date. The board says this reflects wider spreads in smaller companies and the costs of running the tender. It also allows shareholders to sell part of their holding at close to NAV, while continuing shareholders may see a modest uplift to NAV per share. The offer closed on 9 July and results were announced on 13 July. A total of 17,966,998 shares were validly tendered, representing 14.6% of share capital excluding treasury shares. As before, tenders above the basic entitlement were scaled back. Purchases under the offer are expected to take place on 28 July.
The tender offers are structured to avoid forcing too much realisation at any one time.
Demand for both tenders suggests a meaningful group of shareholders wanted liquidity close to NAV. However, the 5% limit is designed to avoid forcing too much selling from the underlying portfolio at any one time, which is important for a smaller companies strategy where liquidity can be an issue.
Alongside buybacks and the lower management fee, the tender facility is part of the board’s broader attempt to address the discount while preserving the trust’s long-term investment case.
Market update
Figure 1: Performance of various indices, 12 months to 30 June 2026
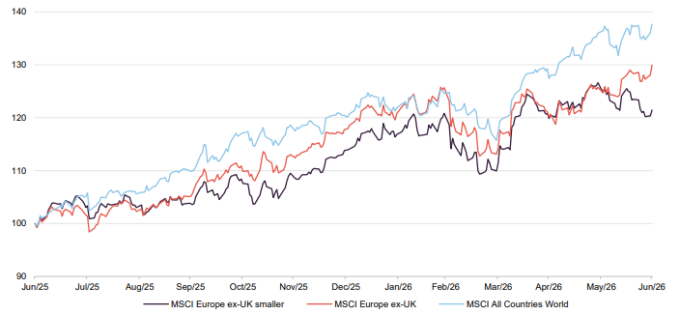
The 12 months to the end of June were generally very positive for equity markets. As shown in Figure 1, European equities took part in this global rally but lagged the MSCI All Countries World index. This was mainly because Europe has less exposure to AI and mega-cap technology stocks, which drove US equity market returns. Smaller European companies also lagged larger ones, although they had kept pace until early June.
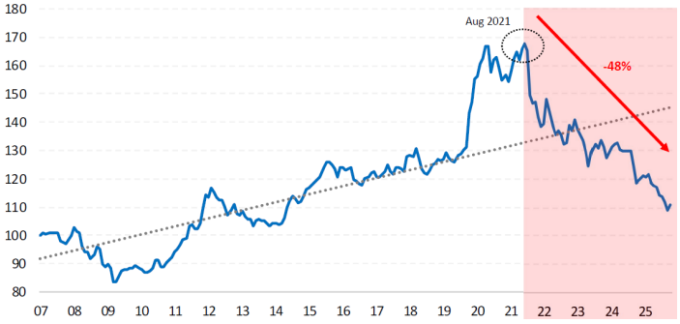
Over the longer term, from after the GFC to late 2021, growth investing delivered strong relative performance, including for European small-cap investors. Figure 2 shows this clearly, with especially strong performance during the COVID pandemic.
Markets then turned in August 2021 as worries about rising inflation and interest rates grew. Since then, growth sectors and holdings have underperformed sharply, down 48% to the end of the first quarter of this year.
Figure 2: MSCI Europe ex-UK small-cap growth vs value index since 2021
This has been a tough environment for MTE as a growth-focused small-cap investor. However, the backdrop appears to be getting less challenging, even if it is too early to call a clear shift back towards growth.
In recent years, European markets have been led by more value-focused areas such as banks, energy and other rate-sensitive cyclical stocks. As the impact of rising rates has eased, valuations in small- and mid-caps look more attractive, and several long-term growth themes are drawing more investor attention. Two of these, AI infrastructure and defence, are discussed below. These areas offer meaningful opportunities in Europe and MTE has exposure.
After four straight years of small-cap underperformance in Europe, 2025 saw a 1% outperformance by smaller companies versus large caps, based on the MSCI Europe ex-UK small cap versus large cap index. This was followed by a further 2% outperformance in the first quarter of this year. MTE has also performed strongly in recent months (see page 13).
Companies exposed to AI bottlenecks have been pushed up sharply.
Artificial intelligence
The European smaller companies sector has been affected by the ongoing artificial intelligence (AI) boom. George notes that investors have quickly looked for potential bottlenecks in the AI data centre supply chain, which has pushed up the share prices of some European companies linked to this theme.
Many AI businesses do not meet MTE’s quality criteria.
In many cases, these have been businesses that do not meet MTE’s usual quality criteria, including loss-making companies or those where George does not see the same durable barriers to entry, compounding potential or strength of business model that he looks for in portfolio holdings. This has been frustrating, as several MTE holdings have continued to perform well operationally but have not always been rewarded by the market.
MTE’s exposure to AI is through high-quality business the manager regards as attractive in their own right.
This does not mean MTE has no exposure to AI. Technoprobe, for example, has been a strong recent contributor to performance. However, George stresses this is a profitable, high-quality business he already viewed as attractive in its own right, rather than a speculative AI trade. He remains focused on companies with the quality, profitability and barriers to entry needed to grow over the long term.
The same disciplined approach is being applied to software. The so-called “SaaSpocalypse” has pressured some software shares as investors worry AI could weaken the advantages of products built around narrow workflows or features that AI agents may replicate. This was especially clear earlier in the year, when a new Claude security tool released in February triggered a sell-off in software names.
The “SaaSpocalypse” has gone too far.
George agrees this risk matters, but says investors should not treat all software companies the same. MTE focuses on businesses where barriers to entry are not just the code, but embedded workflows, specialist functionality or hard-to-copy assets. He believes the sell-off has gone too far and does not justify selling all software exposure.
European defence
European defence has been much in focus, and MTE stands to benefit.
Strong performance from defence companies has been a key theme in European equities over the past year. This has been driven by higher government spending and a reassessment of Europe’s security needs, particularly given a less supportive US administration. NATO allies have agreed to invest 5% of GDP annually in defence and related security spending by 2035, including at least 3.5% of GDP on core defence. The European Commission’s Readiness 2030 plan aims to mobilise more than €800bn of defence-related investment.
Germany’s commitment is especially important. Berlin has loosened strict fiscal rules and is planning a major rise in defence spending, with expenditure expected to move towards NATO’s 3.5% core defence target well before 2035. As Europe’s largest economy, a sustained shift in Germany’s defence budget could drive long-term demand.
MTE does not have large direct exposure to the defence sector. This reflects Montanaro’s quality-growth approach and ethical restrictions around weapons and munitions. Where MTE does have exposure, it is mainly through specialist suppliers supporting the wider defence ecosystem rather than prime contractors or weapons manufacturers.
Invisio (invisio.com) is one example. The Swedish company develops advanced communications and hearing-protection systems for defence and public-safety customers. Kitron (kitron.com – see page 14) is another; the company provides electronics manufacturing services and has benefited from strong defence and aerospace demand. In the first quarter of 2026, defence and aerospace made up 59% of Kitron’s order backlog, up from 45% a year earlier. George says this is notable because defence was previously seen as steady rather than a key growth driver. This shift reflects wider changes across the sector.
Asset allocation
Figure 3: Sector allocation as at 31 May 2026
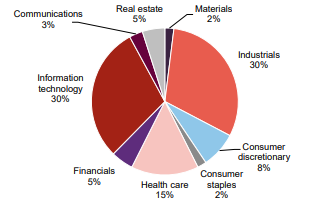
Figure 4: Country allocation as at 31 May 2026
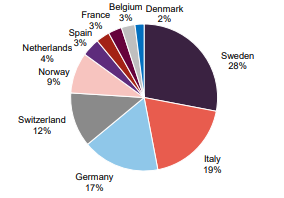
Figure 3 shows MTE’s sector allocation has been broadly stable since our last note, which used data as at 30 April 2025. Industrials and information technology remain the two largest sectors and both have increased their weightings. Healthcare and consumer discretionary are next and have stayed at 15% and 8%, respectively.
Figure 4 shows Sweden remains MTE’s largest country weighting at 28%. Italy and Germany have swapped second and third place, with Italy rising from 14% to 19%. Switzerland is the only other country in double digits.
These modest shifts match George’s long-term approach. He tends to hold companies through market cycles and rarely sells purely due to changes in market sentiment. Country weights mainly reflect his stock selection.
The portfolio had 47 holdings at the end of May 2026, down one since our previous note.
Top 10 holdings
There have been significant changes to MTE’s top 10 holdings since our last note, with six new names: Technoprobe, NCAB, Carel Industries, Brembo, Melexis and Merlin Properties. George confirms these are not new to the portfolio and that their rise into the top 10 is mainly due to market moves. He prefers to “let the winners win”, rather than selling simply because a holding has performed well.
Figure 5: MTE’s 10 largest holdings as at 31 May 2026
| Holding 30 April 2025 (%) | Holding 31 May 2026 (%) | Change (%) | Country | Sector | |
|---|---|---|---|---|---|
| Technoprobe | 1.4 | 5.4 | 1.0 | Italy | Semiconductor testing equipment |
| NCAB | 2.7 | 5.4 | 2.7 | Sweden | Printed circuit board |
| Kitron | 4.9 | 4.9 | – | Norway | Electronics manufacturing |
| Plejd | 4.0 | 3.9 | (0.1) | Sweden | Smart lighting manufacturer |
| Belimo | 3.9 | 3.5 | (0.4) | Switzerland | Ventilation and air conditioning |
| Carel Industries | 1.7 | 3.5 | 1.8 | Italy | HVAC and refrigeration controls |
| Brembo | 2.0 | 3.1 | 1.1 | Italy | Automotive braking systems |
| Melexis | 1.9 | 3.0 | 1.1 | Belgium | Semiconductor sensors |
| Merlin Properties | 2.0 | 2.8 | 0.8 | Spain | Real estate |
| CTS Eventim | 4.4 | 2.7 | (1.7) | Germany | Ticketing and events |
| Total | 38.2 |
Technoprobe
Figure 6: Technoprobe (EUR)
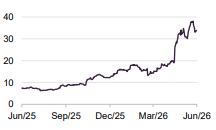
Technoprobe (technoprobe.com) is an Italian semiconductor equipment company that makes probe cards used to test chips during manufacturing. These products are particularly important for the complex chips used in high-performance computing, artificial intelligence, consumer electronics, automotive and industrial markets.
The company has benefited from strong investment in advanced semiconductors, with AI and data centre demand driving a sharp improvement in trading and a strong share price rally. Technoprobe reported record first-quarter 2026 revenue of €187m, up 19% year-on-year, and raised its full-year guidance. Management said that having enough capacity has become critical to meet demand in the current semiconductor upcycle.
NCAB
Figure 7: NCAB (SEK)
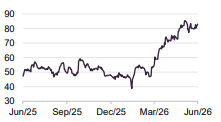
NCAB (ncabgroup.com) is a Swedish printed circuit board (PCB) specialist supplying customers across industrials, automotive, medical technology, telecoms and aerospace sectors. It is asset-light, using a network of factories rather than owning large manufacturing sites. Smaller buyers can use NCAB instead of buying direct, as it can negotiate better terms through its combined purchasing power.
George says NCAB gives the portfolio exposure to a wider set of long-term growth themes, rather than being a pure AI holding. The shares have been supported by improving demand and a strong recovery in orders. In Q1 2026, net sales were SEK 1,074m, up 12%, and order intake rose 27%. NCAB said demand benefited from large project orders, price rises and stronger industrial activity, while its supply-chain model helped it manage a more volatile environment.
Carel Industries
Figure 8: Carel Industries (EUR)
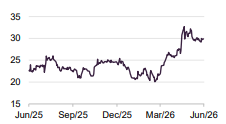
Carel Industries (carel.com) is an Italian company that designs and makes control systems, sensors and software for heating, ventilation and refrigeration, used in commercial refrigeration, building management and industrial cooling.
Carel is attractive for its exposure to energy efficiency and more advanced cooling systems. George also highlights opportunities in data centres, which need high-quality cooling technology. Demand is supported by long-term growth in refrigeration and lower-energy building systems, driven by regulation and customers shifting towards more efficient solutions. This gives Carel a mix of industrial technology and sustainability-linked growth, and recent performance suggests these end-markets remain supportive.
Brembo
Figure 9: Brembo (EUR)
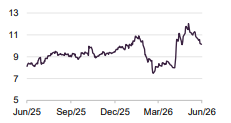
Brembo (brembogroup.com) is an Italian maker of braking systems for cars, motorcycles and commercial vehicles, with a strong position in premium, high-performance and motorsport markets.
It has built a strong brand and technology lead in a specialist part of the car supply chain where safety, reliability and performance are critical. Its Sensify intelligent braking system shows it is moving beyond traditional parts towards more software-driven, higher-value systems. While the near-term outlook for autos is mixed, Brembo’s premium positioning and margins have helped it stay more resilient than many suppliers.
Melexis
Figure 10: Melexis (EUR)
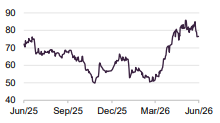
Melexis (melexis.com) is a Belgian semiconductor company that makes mixed-signal chips, sensors and driver integrated circuits, with a strong position in the automotive sector. Its products are used in electrification, safety, thermal management, lighting and position sensing.
Melexis has been hit by a weaker period for automotive semiconductors as customers reduced excess stock and vehicle production growth slowed. The longer-term case is supported by rising semiconductor content per car as vehicles become more electrified, automated and digitally controlled. This gives MTE exposure to automotive technology without relying solely on vehicle volumes. The shares struggled until recently but have rebounded strongly since the end of March.
Merlin Properties
Figure 11: Merlin Properties (EUR)
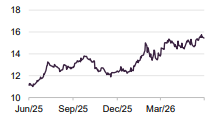
Merlin Properties (merlinproperties.com) is a Spanish listed property company with a portfolio of offices, logistics, shopping centres and data centres, mainly in Spain and Portugal.
While many listed property companies are still judged on interest rates, valuations and office demand, Merlin has stood out through the growing importance of its data centre platform. It is developing sites on land it already owns across the “Iberian Digital Diagonal”, where it believes better power availability, renewable energy, fibre connections and lower build costs give it an edge over more constrained hubs such as Frankfurt, London and Paris.
For MTE, the holding adds exposure to digital infrastructure through a property company with an established Iberian asset base.
Performance
Figure 12: MTE NAV total return performance relative to the MSCI Europe ex UK Small Cap Index, over the five years to 30 June 2026
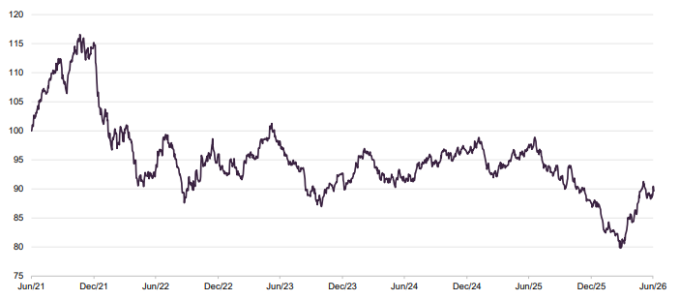
As Figure 12 shows, over the past five years MTE’s NAV return has lagged its benchmark, the MSCI Europe ex UK Small Cap Index. The fund did outperform in 2020 and 2021, helped by low interest rates and the pandemic-driven boost to growth stocks. However, much of this was reversed in 2022 as inflation rose and higher rate expectations led to a sell-off in growth stocks, while value-style investing recovered.
Performance has been steadier since then, but there was another setback at the end of 2025. European markets saw an unusually sharp shift away from growth and quality towards value, cyclicals and more macro-sensitive areas. George says this was particularly frustrating because many portfolio companies performed well operationally, but their share prices still fell. This was partly due to valuation worries, as investors moved from early AI hype to demanding proof of profits. Rising trade tensions and changing monetary policy also pushed investors towards steadier, cash-generating companies. In early 2026, performance was further held back by a software sell-off linked to concerns about the potential negative impact of agentic AI.
Very recent performance has been good. Figure 13 shows clear outperformance versus the benchmark in both NAV and share price terms in the past months. George says there is no clear reason for the turnaround, although MTE has benefited from positive momentum in some stocks.
Figure 13: Cumulative total returns for periods ending 30 June 2026
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | 10 years (%) | |
|---|---|---|---|---|---|---|
| NAV | 18.1 | 6.0 | 0.8 | 29.9 | 6.3 | 254.5 |
| Share price | 17.9 | 6.7 | 2.3 | 25.5 | 12.4 | 209.5 |
| Benchmark1 | 6.2 | 4.4 | 11.4 | 37.8 | 25.6 | 144.7 |
| MSCI European ex UK | 12.8 | 10.5 | 22.7 | 52.2 | 64.9 | 190.9 |
Figure 13 also shows much longer-term performance, which remains strong. Over 10 years, MTE’s total NAV return has been more than 100% ahead of the benchmark and also comfortably ahead of the larger-cap index.
Top contributors and detractors
Figure 14 shows the main contributors and detractors to MTE’s returns over the 12 months to 31 March 2026.
Figure 14: MTE top contributors and detractors
| Top contributors | % contribution | Top detractors | % contribution |
|---|---|---|---|
| Kitron | 2.1 | ChemoMetec | (1.7) |
| Technoprobe | 0.7 | ATOSS Software | (1.3) |
| NCAB | 0.6 | CTS Eventim | (1.1) |
| IMCD | 0.3 | Reply | (0.7) |
| Merlin Properties | 0.3 | Belimo | (0.6) |
Technoprobe and NCAB were covered in detail above (see page 10), but it is worth highlighting Kitron and the three biggest detractors.
Kitron (kitron.com) is a Scandinavian electronics manufacturing services provider that produces complex electronic assemblies for customers in defence, industrials, electrification, connectivity and medical devices. The shares performed strongly as investors responded to faster demand, especially in defence and aerospace. This reflected higher European defence spending and the need to expand manufacturing capacity for sensitive electronic systems. Kitron also reported progress in its other end-markets.
ChemoMetec (chemometec.com) fell after weaker momentum and uncertainty over its earnings outlook. While the company later upgraded its 2025/26 guidance, this followed an earlier downgrade and was partly helped by an accounting adjustment that had a one-off positive effect on sales and EBITDA. The shares were held back by concerns about the pace of underlying growth, particularly after an earlier strong period for the life sciences tools business.
ATOSS Software (atoss.com) weakened despite continued growth in its workforce management software business. The shares were hit by a wider fall in highly valued European software and quality growth stocks. A planned leadership change, with founder and chief executive Andreas Obereder moving to the supervisory board, added to near-term uncertainty, although management kept its previously announced 2026 growth outlook.
CTS Eventim (eventim.de) detracted after investors reacted negatively to weaker-than-expected second-quarter 2025 results. The ticketing and live entertainment group reported lower profit due to weaker revenue from its own events and the cost of integrating acquisitions. More recent trading showed some recovery, including a strong first quarter in 2026.
Eventim has also faced scrutiny over consumer practices. In February 2025, a German court ruled that repeatedly promoting ticket insurance during online checkout breached the EU Digital Services Act, although the decision was not final and Eventim appealed. In January 2026, it agreed an out-of-court settlement with a German consumer organisation over fees kept from refunds for pandemic-era cancellations. More than 5,000 registered claimants were offered €20 vouchers, but the settlement did not create a general right to fee repayments.
Peer group
MTE is one of three funds in the AIC’s European Smaller Companies sector.
MTE is a member of the AIC’s European Smaller Companies sector, alongside JPMorgan European Discovery Trust and The European Smaller Companies Trust. The peer group has shrunk since our last note after The European Assets Trust merged into The European Smaller Companies Trust in October 2025.
As shown in Figure 15, MTE’s strong recent performance puts it top of the peer group over three months, but weaker performance earlier in the year leaves it bottom over six months.
MTE has also underperformed the peer group median over the last three and five years. It did particularly well when growth stocks were strongly favoured in 2020 and 2021, but much of the later relative weakness came in the first half of 2022. Russia’s invasion of Ukraine and the jump in fuel and commodity prices pushed up inflation and expectations for higher interest rates, which was a tough backdrop for growth companies. While this period has now dropped out of the three-year figures, it is still fully reflected in the five-year numbers.
Over 10 years, MTE’s performance has been more competitive, with its NAV total return ahead of the peer group median. This period includes the post-COVID rally in growth stocks, supported by low interest rates and ample liquidity, which benefited the smaller companies held by the fund. While subsequent weakness has weighed on the five-year figures, the 10-year numbers give a clearer picture of MTE’s longer-term performance across different market conditions.
Figure 15: Listed European smaller companies peer group NAV total return performance over periods ending 30 June 2026
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | 10 years (%) | |
|---|---|---|---|---|---|---|
| MTE | 17.9 | 6.7 | 2.3 | 25.5 | 12.4 | 209.5 |
| JPMorgan European Discovery Trust | 11.1 | 8.5 | 16.3 | 60.1 | 34.0 | 157.2 |
| The European Smaller Companies Trust | 14.9 | 8.4 | 16.8 | 49.9 | 37.8 | 242.1 |
| Peer group median | 14.6 | 7.9 | 11.8 | 45.2 | 28.1 | 202.9 |
| MTE rank | 1/3 | 3/3 | 3/3 | 3/3 | 3/3 | 2/3 |
Figure 16 shows fund statistics for MTE’s peer group. Following the merger discussed above, MTE is now the sector’s smallest trust. However, it remains large enough that this should not materially affect demand for its shares.
MTE has the lowest dividend yield among its peers, reflecting its higher exposure to high-growth companies, which typically pay lower dividends.
MTE’s discount is still the narrowest in the peer group, although it is close to the average given the tight range. Its ongoing charges ratio is higher than its two peers, mainly due to its smaller size. The historic cost in Figure 16 does not yet show the full impact of the management fee reduction from 1 April 2025, which should bring costs closer to the peer-group median over time.
Figure 16: Listed European smaller companies peer group stats, as at 25 June 2026
| Market cap(£m) | Discount(%) | Dividend yield(%) | Ongoing charge(%) | |
|---|---|---|---|---|
| MTE | 219 | (8.1) | 0.7 | 1.00 |
| JPMorgan European Discovery Trust | 584 | (8.7) | 2.5 | 0.88 |
| The European Smaller Companies Trust | 796 | (9.3) | 2.1 | 0.68 |
| Peer group median | 584 | -8.7 | 2.1 | 0.88 |
| MTE rank | 3/3 | 1/3 | 3/3 | 3/3 |
Dividend
MTE is managed with capital growth as its main objective. Any income is therefore a by-product of the manager’s stock selection, not a specific target, so it can vary significantly over time. However, given the trust’s focus on high-quality companies, many of which generate cash and pay dividends, MTE can make a payout. Its current yield is 0.74%.
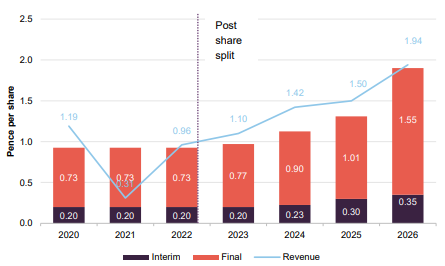
Figure 17: MTE dividend history, accounting years ended 31 March
of MTE’s shares
In 2025, MTE paid a third interim dividend of 0.05p alongside the usual first two payments. For simplicity, this has been included in the final dividend in Figure 17. The company has not explained the extra payment, but it appears to be a small adjustment to the distribution for the year ended 31 March 2025.
A second interim dividend of 1.2p has been announced, to be paid on 28 August 2026. To meet minimum distribution rules and reflect the recent sharp fall in shares in issue, a special dividend of 0.35p will also be paid on the same date. This brings total dividends for the year to 1.9p per share.
Figure 17 shows the dividend has been comfortably covered by revenue in recent years. MTE also has a large revenue reserve, which rose to £5.8m at 31 March 2026. This equals about 4.8p per share, or more than three times the total dividend of 1.31p per share paid for the year, giving the board a useful buffer if earnings come under pressure.
Premium/(discount)
Over the 12 months to the end of June 2026, MTE’s shares traded at a 7.3% to 8.7% discount to NAV, averaging 8.1%. As of 22 July 2026, the shares were at a 7.9% discount.
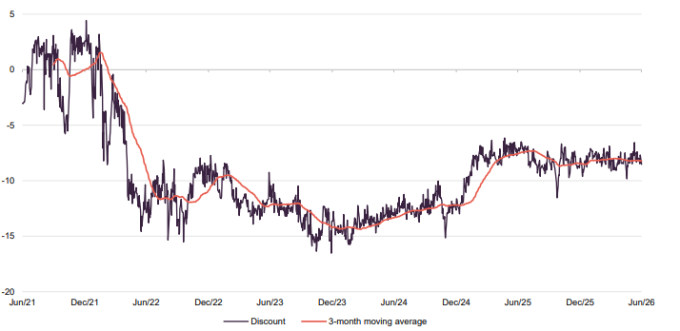
MTE’s discount widened sharply in 2022 as rising inflation and interest-rate expectations reduced demand for growth companies. It rose above 15% in late 2023, before narrowing significantly from the end of 2024 as the outlook for inflation and interest rates improved and the board took a more active approach to managing the discount.
In March 2025, the board introduced a policy to keep the discount in single digits in normal market conditions, using regular share buybacks and twice-yearly tender offers (see page 4). The policy appears to be working. Since early 2025, MTE’s discount has generally stayed in the high single digits, compared with much wider levels in 2022 to 2024.
The board has continued buybacks between tenders. It repurchased a further 12.51m shares between completion of the first tender and the second tender circular, equal to about 9% of the shares remaining after the first tender.
Figure 18: MTE discount over five years ending 30 June 2026
SWOT analysis
Figure 19: SWOT analysis for MTE
| Strengths | Weaknesses |
| MTE has a differentiated, quality-growth approach to European smaller companies. The manager focuses on businesses with strong market positions, recurring revenues, high returns on capital and the potential to compound earnings over long periods. This has supported a strong record over the very long term, with MTE ahead of the peer group median over 10 years. | MTE’s pronounced quality and growth bias can leave it behind when value, cyclical or lower-quality companies lead the market, even if the underlying portfolio businesses continue to perform well operationally. |
| The trust benefits from a specialist and well-resourced manager. George Cooke has substantial experience investing in European smaller companies and is supported by Montanaro’s wider research team, whose dedicated focus on smaller businesses can be an advantage in a relatively under-researched part of the market. | The portfolio is sensitive to interest-rate expectations. Higher bond yields reduce the present value placed on companies whose earnings are expected further into the future. This was a major factor behind the trust’s relative weakness from 2022 and remains an important source of style risk. |
| Gearing can enhance returns when the portfolio performs well. The trust may borrow up to 30% of shareholders’ funds, net of cash, although gearing has generally been used conservatively and stood at 1.6% at 29 May 2026. This gives the manager scope to increase exposure when attractive opportunities arise without making gearing a dominant source of risk. | The five-year performance remains weak relative to peers. Although the most recent three-month performance has improved and the 10-year record is stronger, the five-year figures still capture the sharp derating of growth companies during 2022. |
| The board has taken a more active approach to discount control. Its single-digit discount policy, regular buybacks and twice-yearly tender offers have helped keep the discount broadly in the high single digits since early 2025. | A quality-focused process can lead the manager to avoid cheaper parts of the market. The emphasis on financially strong businesses means MTE may miss rallies in highly leveraged, economically sensitive or lower-quality companies that do not meet its investment criteria. |
| Gearing can magnify losses as well as gains. Current gearing is modest, but the trust has authority to borrow materially more. Increased gearing introduced at the wrong point in the cycle would amplify declines in NAV. | |
| Opportunities | Threats |
| A decline in interest rates could provide a more supportive backdrop. Lower discount rates would be helpful for long-duration growth businesses and could encourage investors to place greater value on MTE’s portfolio of compounders. | Interest rates could remain higher for longer. Renewed inflation or rising bond yields would be likely to weigh on growth-company valuations and could again place pressure on MTE’s relative performance. |
| European smaller companies remain relatively overlooked. Investor attention and capital have been concentrated in US mega-cap stocks, leaving scope for a broader market rotation towards smaller businesses and less-crowded areas of Europe. | The market may continue to favour value or cyclical businesses. A prolonged rotation away from quality growth would remain a difficult environment for the trust, irrespective of the operational progress made by its holdings. |
| The portfolio has exposure to structural growth themes, including artificial intelligence, healthcare innovation and increased European defence spending. The opportunity is not limited to direct beneficiaries, but also includes specialist suppliers and enabling technologies. | Smaller companies can be less liquid and more economically sensitive. In periods of stress, their shares may fall more sharply than those of larger companies and can be harder to trade without affecting the price. |
| Improving earnings delivery could prompt a rerating. If portfolio companies continue to compound earnings while their valuations remain subdued, returns could benefit from both profit growth and a recovery in valuation multiples. | Valuation discipline remains important. High-quality companies can still produce poor investment returns when bought at excessive valuations. Earnings disappointments can lead to particularly sharp falls where strong growth has already been priced in. |
| The discount-control measures could improve shareholder returns. Repurchasing shares below NAV is accretive to NAV per share, while the tender offers provide a regular exit mechanism and may help reduce the risk of the discount returning to the much wider levels seen in 2022 to 2024. | MTE has concentrated geographic and style exposure. It is focused on continental European smaller companies rather than offering broad global diversification, leaving returns sensitive to the European economy, political developments, regulation and currency movements. |
| The discount could widen again despite the board’s policy. Buybacks and tenders can influence supply and demand, but they cannot remove the effect of weak sentiment towards European smaller companies or investment trusts more generally. |
Bull vs. bear case
Figure 20: Bull vs. bear case for MTE
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | MTE offers focused exposure to high-quality European smaller companies, an area that has historically generated attractive long-term returns. Its 10-year record remains strong and recent performance has improved as the market backdrop has become more supportive. If investors continue to move beyond US mega-cap technology stocks and return to European smaller companies, MTE could benefit from both earnings growth and a recovery in valuations. Modest gearing can also enhance returns in rising markets. | MTE’s quality-growth bias leaves it vulnerable when value, cyclical or lower-quality companies lead the market. The five-year record remains weak relative to peers, reflecting the sharp derating of growth stocks from 2022. If interest rates or bond yields remain elevated, investors may continue to apply lower valuation multiples to the portfolio’s longer-duration earnings. Gearing, although currently modest, can magnify losses during falling markets. |
| Dividends | MTE’s dividend has been comfortably covered by revenue in recent years. At 30 September 2025, its £6.4m revenue reserve was equivalent to around 4.29p per share, providing a meaningful cushion relative to the annual dividend. This gives the board some flexibility to maintain or gradually increase distributions if portfolio income fluctuates. | MTE is principally a capital-growth investment rather than an income vehicle. Its yield is modest and the dividend is unlikely to be a major contributor to total returns. Income may also vary because the portfolio is concentrated in smaller growth companies, where reinvestment in the business often takes priority over paying high dividends. |
| Outlook | The long-term opportunity in European smaller companies remains attractive. The portfolio contains businesses exposed to structural trends including artificial intelligence and increased European defence spending. A stabilisation or decline in inflation and interest rates would provide a more favourable backdrop for growth-company valuations, while continued earnings delivery could encourage a rerating. | The outlook remains sensitive to macroeconomic conditions. Renewed inflation, higher-for-longer interest rates or weaker European economic growth could place pressure on both company earnings and valuation multiples. Smaller businesses can also be more exposed to changes in customer demand, financing conditions and supply chains. If growth investing remains out of favour, operational progress may not translate into stronger share prices. |
| Discount | The board’s more active discount-control policy appears to be working. Regular market buybacks and twice-yearly tender offers have helped keep the shares on a broadly single-digit discount since early 2025. Between the first and second tenders, MTE repurchased approximately 12.5m shares in the market, equivalent to around 9% of the shares outstanding immediately after the first tender. Buybacks at a discount are accretive to NAV per share and the tenders provide shareholders with a regular exit mechanism. | Discount-control measures cannot eliminate weak market demand for investment trusts or European smaller companies. The discount could widen again if performance disappoints, interest-rate expectations rise or investors move away from growth-oriented strategies. Regular buybacks and tenders also reduce the trust’s size, which may lower liquidity and increase the ongoing-charges ratio if costs are spread across a smaller asset base. |
| Other | MTE benefits from a specialist manager and a dedicated European smaller-companies research platform. The portfolio’s emphasis on financially strong, well-managed businesses may also provide some resilience in more difficult economic conditions. | The trust is concentrated by geography, market-cap segment and investment style. Its quality discipline may lead it to avoid cheaper or more cyclical companies that can perform strongly during market rotations. Smaller-company shares are generally less liquid than large caps and can experience sharper price movements during periods of stress. |
Previous notes
Readers looking for more information about MTE can read our other notes by clicking the links in the table or visiting the QuotedData website.
Figure 21: QuotedData’s other notes on MTE
| Note | Date published | Note type |
|---|---|---|
| Quality businesses at sensible prices | March 2019 | Initiation |
| Focus on the small picture | September 2019 | Update |
| Impressive returns in difficult market | October 2020 | Annual overview |
| Unfazed by market turmoil | March 2022 | Annual overview |
| No Continental drift | August 2023 | Annual overview |
| Primed for ignition | August 2024 | Annual overview |
| Turning tariffs into opportunity: MTE’s edge | June 2025 | Update |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Montanaro European Smaller Companies Investment Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.