
Ready for a small-cap reset?
The April 2026 combination with BlackRock Throgmorton has reinforced BlackRock Smaller Companies Trust’s (BRSC) position as the largest growth-focused trust in the UK smaller companies sector. The transaction also seems to provide shareholders with lower fees, an exit mechanism in the event of underperformance and greater flexibility to invest overseas.
The manager believes that backdrop for UK small caps remains challenging. Fund flows have been weak, and political uncertainty may have weighed on confidence. However, valuations may already reflect much of this pessimism, while continued M&A activity might suggest that corporate buyers may be identifying value that public-market investors are not reflecting.
There may also be signs of improvement beneath the surface, while the appointment of a new Prime Minister could offer the prospect of a change in perceptions of the domestic UK market. With growth shares seemingly inexpensive relative to value, BRSC trading at a discount, and modest gearing potentially providing additional upside, any sustained recovery in sentiment could benefit returns.
UK smaller companies with a quality-growth focus
BRSC aims to achieve long-term capital growth by investing mainly in smaller UK quoted companies. It focuses on high-quality businesses with strong management teams, good cash generation and robust balance sheets.
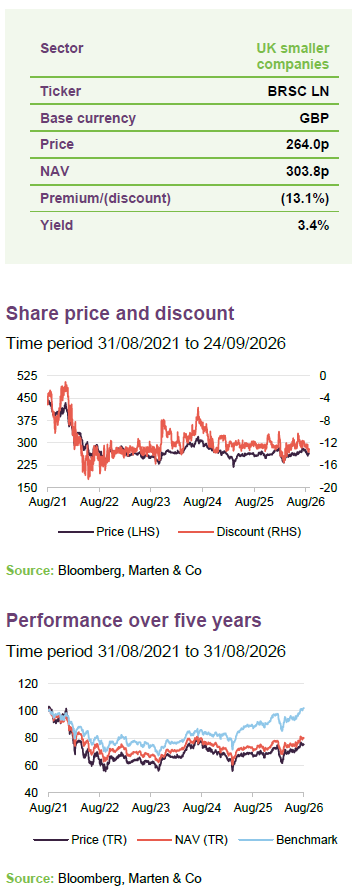
| Year ended | Share price total return (%) | NAV total return (%) | Deutsche Numis Sm Cos +AIM, ex IC TR (%) | MSCI UK total return (%) |
|---|---|---|---|---|
| 31/08/2022 | (35.3) | (28.5) | (21.9) | 11.4 |
| 31/08/2023 | (3.9) | (5.8) | (4.1) | 3.4 |
| 31/08/2024 | 23.9 | 18.5 | 14.6 | 17.6 |
| 31/08/2025 | (11.6) | (9.7) | 3.0 | 13.3 |
| 31/08/2026 | 10.7 | 11.0 | 15.3 | 21.7 |
Fund profile
BRSC aims for capital growth through smaller UK quoted companies.
BRSC aims to achieve long-term capital growth by investing predominantly in smaller UK quoted companies. Established in 1906, the trust adopted its small-cap focus in the early 1990s and has refined its approach over time. It provides exposure to a part of the market that the manager believes is comparatively under-researched, where it says active stock picking can identify businesses capable of long-term growth.
BRSC is benchmarked against the Deutsche Numis Smaller Companies plus AIM (excluding Investment Companies) Index, although the portfolio is constructed on a bottom-up basis and can differ materially from the benchmark (an active share according to the manager that is typically between 70-78%, and was 77.7% as at 31 August). The manager states that the investment approach has a quality-growth bias, with him looking for businesses with established management teams, leading positions in their markets, and the ability to generate sustainable growth and cash flow.
Roland Arnold is BRSC’s portfolio manager. He has managed UK small- and mid-cap portfolios since 2006. Roland is supported by BlackRock’s wider Emerging Companies team, which comprises three portfolio managers within its Fundamental Equities platform. The team conducts its own company research while drawing on BlackRock’s broader resources, including its global research platform, corporate access, equity capital markets expertise and specialist sector teams. Matt Betts provides additional input and ideas for the overseas portion of BRSC’s portfolio.
BRSC can gear by up to 20% of net assets, although the board expects gearing to remain within a range of 0-15% under normal market conditions. Current gearing is around 8%.
Combination with Throgmorton
The combination with THRG appears to have supported BRSC’s position as the largest growth-focused UK smaller companies fund.
BRSC completed its combination with BlackRock Throgmorton (THRG) in April 2026, bringing together two UK smaller-company trusts with similar investment approaches and portfolio overlap. We covered the transaction at the time here. The deal increased BRSC’s scale and liquidity, broadened its shareholder base and, according to BRSC, reinforced its position as the largest growth-focused trust in the UK smaller companies sector.
Although a proportion of THRG shareholders exited through a tender offer, BRSC acquired approximately £303m of net assets and issued 20.9m new shares to those who rolled their holdings into the enlarged trust.
The merger was accompanied by lower management fee rates and a performance-related tender mechanism. Specifically, if BRSC underperforms its benchmark over a three-year assessment period, shareholders may be offered a 100% tender at a 4% discount to NAV. The first potential tender is in 2029.
Separately, a quarterly dividend was announced in October 2025 and became effective in March 2026.
The transaction also sought to address the position of Saba Capital, the US hedge fund that has targeted several UK investment trusts in recent years. Saba elected to tender its shares in full and agreed to an extension of its standstill agreement with the board until June 2030. However, because the tender was oversubscribed, Saba’s tendered shares were scaled back. It has also subsequently added to its holding to build an economic interest in BRSC and, at 24 July 2026, disclosed aggregate exposure equivalent to 14.2% of the trust, predominantly through a total return swap.
Ability to go overseas
After the THRG combination, BRSC can now invest overseas.
One change following the combination with THRG is BRSC’s ability to invest up to 15% of gross assets, at the time of acquisition, in overseas-listed small-cap stocks. Roland states that the intention is to run this allocation at around 10%, which may give him flexibility to buy into additional themes. One example is Construction Partners, a civil infrastructure company that provides exposure to the US market. However, Roland states that this additional flexibility may not be sufficient on its own to offset the challenges facing the UK market.
Unlike THRG, BRSC does not have the ability to short stocks.
Market update – difficult backdrop, but attractive valuations?
Roland believes the UK smaller companies market faces a number of challenges.
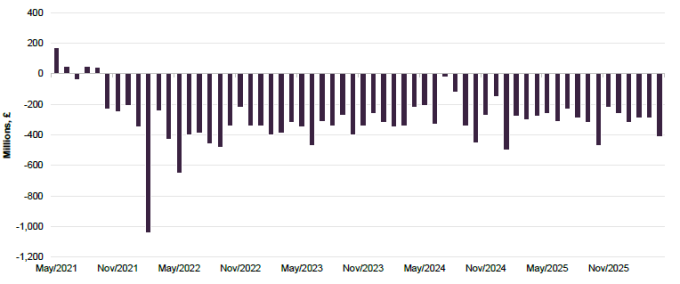
Roland is cautious on the near-term outlook for UK smaller companies. He believes the UK faces structural challenges, while the possibility of another difficult Budget in the autumn may be adding to uncertainty around taxation, inflation and employment. Investor flows into UK smaller companies also appear weak, seemingly leaving buybacks and M&A as some of the few consistent sources of demand. Takeover activity may reflect the valuations available to corporate and private equity buyers, but this may not compensate indefinitely for persistent outflows – Figure 1 shows active flows out of UK small- and mid-cap funds over recent years.
According to the BRSC manager however, there are some more encouraging signs beneath the surface. Roland sees evidence of an industrial recovery, particularly from the depressed levels reached across parts of the engineering and capital goods sectors. He cautions, though, that some of the improvement may be influenced by spending on data centres and AI-related infrastructure, making it difficult to judge how broad-based or durable the recovery may be. At the same time, many of the companies exposed to these trends have seemingly continued to become cheaper despite little change in their longer-term prospects.
Figure 1: Active UK equity small- and mid-cap fund flows over five years to 30 April 2026
New government – chance for a reset?
New Prime Minister Andy Burnham may offer the possibility of a reset.
Roland believes that much of the recent negative sentiment around the UK domestic economy has reflected political uncertainty rather than economic weakness. He was critical of the Starmer government’s handling of the economy but sees scope for a reset under the new prime minister Andy Burnham. Burnham has seemingly so far emphasised growth, while Roland considers the appointment of John Healey as chancellor reassuring.
Roland says that if the government demonstrates fiscal discipline, manages its parliamentary party and brings public borrowing under control, there could be scope to help consumers and businesses. In this scenario, the current cycle could reverse relatively quickly, with the UK smaller companies sector potentially returning to favour.
Despite his cautious view, Roland does not believe the underlying UK economy is as weak as sentiment suggests. Productivity appears to be showing signs of improvement after a long period of stagnation, albeit partly at the expense of employment, while corporate and household balance sheets seemingly remain relatively cash rich.
He suggests that, with UK smaller-company valuations appearing low in absolute terms, valuations appearing to reflect a considerable amount of adverse expectations, and growth stocks trading at lower valuations relative to value, any sustained improvement in sentiment could be associated with a recovery.
Asset allocation
As shown in Figure 2, BRSC’s two largest sector allocations are to industrials and financials. Both are overweight positions versus the benchmark.
Figure 2: BRSC sector allocation as at 31 July 2026
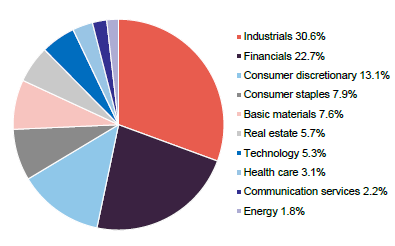
Figure 3: BRSC’s top 10 holdings at 31 July 2026
| Company | (%) |
| Greencore Group | 3.5 |
| Great Portland Estates | 3.2 |
| XPS Pensions | 3.2 |
| Tatton Asset Management | 2.9 |
| Morgan Sindall | 2.7 |
| IntegraFin | 2.6 |
| discoverIE | 2.5 |
| Young’s & Co Brewery | 2.3 |
| SigmaRoc | 2.1 |
| AJ Bell | 2.1 |
| Total top 10 | 27.1 |
BRSC’s portfolio seems to have been relatively stable over the past financial year. Roland highlighted two of the top 10 holdings where he feels that prospects have improved:
Greencore Group
Figure 4: Greencore Group (GBp)
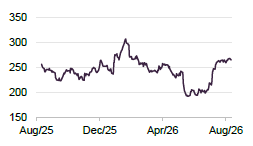
Greencore (www.greencore.com) is a UK and Ireland food producer supplying a range of products to major retailers and foodservice customers. The business experienced a period that included an acquisition in the US that was subsequently unwound, alongside cost pressures and lower margins closer to home.
More recently, performance appears to have improved. A refreshed management team has focused on restoring profitability through pricing, cost control and operational execution, which may have supported margin recovery.
Greencore has also appeared to benefit from broader changes across the food manufacturing sector, as easing input-cost pressures and pricing practices may have improved the outlook for profitability. With earnings momentum appearing to strengthen and confidence in the recovery increasing, the shares have rerated and have been among the portfolio’s stronger recent performers.
discoverIE
Figure 5: discoverIE (GBp)
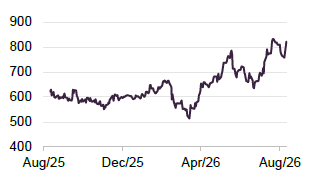
discoverIE (www.discoverieplc.com) designs and manufactures customised and niche electronic components for a range of industrial applications. The group focuses on specialist products where technical expertise and close customer relationships may create relatively high barriers to entry and support margins.
The company states that it was affected by a prolonged period of destocking as customers that had built up excess inventories during earlier supply-chain disruption reduced orders. This appears to have taken longer than the company expected to unwind, which may have affected growth and sentiment.
More recently, conditions appear to have begun to improve, with the order book increasing by around 30%. Roland hopes this could mark the early stages of a broader recovery in capital goods. If customer inventories have now normalised, a recovery in underlying demand could support revenues and profitability.
Performance
Figure 6: Cumulative total return performance over periods ending 31 August 2026
| 1 month (%) | 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|---|
| BRSC NAV | 3.8 | 5.2 | 2.8 | 11.0 | 18.8 | (19.9) |
| BRSC share price | 2.8 | 5.1 | 1.7 | 10.7 | 21.2 | (24.7) |
| Deutsche Numis Smaller Cos plus AIM ex IC | 4.2 | 5.8 | 4.3 | 15.3 | 36.2 | 2.0 |
| MSCI UK | 0.0 | 4.7 | 1.1 | 21.7 | 62.2 | 86.8 |
As Figure 6 shows, BRSC’s recent performance appears to have improved, although it has yet to fully recover the ground lost over the past few years. This longer-term shortfall versus the benchmark and wider market may reflect market conditions that have been challenging for the manager’s quality-growth style, as value and larger companies appear to have led the market. Growth-oriented UK smaller companies seem to have experienced a prolonged period of underperformance, with the valuation gap versus value apparently close to its widest in 20 years.
Roland does not expect this gap to close simply because it has become extreme, but believes the starting point is increasingly attractive. He states that many growth companies are generating substantial cash flow and, in some cases, now offer high dividend yields because their share prices have fallen.
Dividend
Although BRSC’s primary objective is capital growth, it has a record of dividend growth, having increased its annual payment every year since 2003, and has AIC Dividend Hero status. In October 2025, BRSC announced it would move from semi-annual to quarterly distributions for the next financial year, while retaining its progressive dividend policy. The first quarterly payment, due in September 2026, is 2.225p per share after July’s five-for-one share split, equivalent to a quarter of the dividend paid for the previous financial year.
Revenue reserves may provide additional flexibility to support the dividend during weaker periods for portfolio income. However, the dividend was fully covered by earnings in every year apart from 2020, during the Covid pandemic.
Premium/(discount)
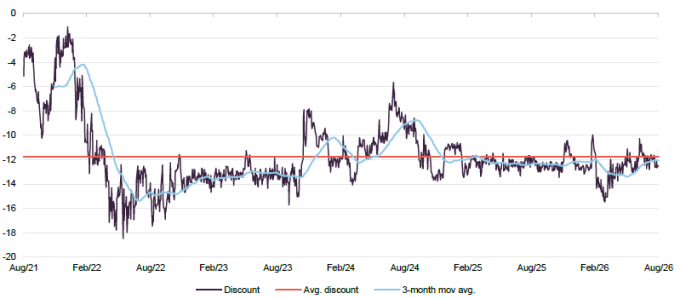
As shown in Figure 7, the discount widened in the first half of 2022, as growth investing appeared to come under pressure from rising inflation and interest rates. Since then, the broad trend appears to have been a gradual discount narrowing.
Over the 12 months to 31 August 2026, the average discount was 12.5%, ranging from 10.0% to 15.5%.
Figure 7: BRSC premium/(discount) over five years to 31 August 2026
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on BlackRock Smaller Companies Trust.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.