
A sharper edge for BGUK
Baillie Gifford UK Growth Trust (BGUK) provides access to the UK market through a concentrated portfolio of growth companies. Its performance appears to have been affected by a prolonged period in which UK growth investing has been out of favour. However, the trust states that many portfolio companies have continued to make operational progress, while valuations remain low relative to their earnings prospects and international peers.
The appointment of James Smith as a third co-manager may bring a different perspective and is expected by the manager to increase the focus on portfolio construction, valuation and sell discipline, while preserving BGUK’s long-term growth philosophy. With gearing in place, a strengthened management team and a portfolio of businesses with long-term growth objectives, BGUK may be positioned to benefit from any recovery in UK growth equities. In the meantime, the management fee has been cut by 20% until April 2029, and the trust’s high-single-digit discount could provide an additional source of potential upside if performance and investor sentiment improve.
Focused portfolio of UK growth equities
BGUK aims to achieve capital growth by investing in a concentrated portfolio (35–65 companies) of predominantly UK equities, with the aim of providing a total return in excess of the FTSE All-Share Index.
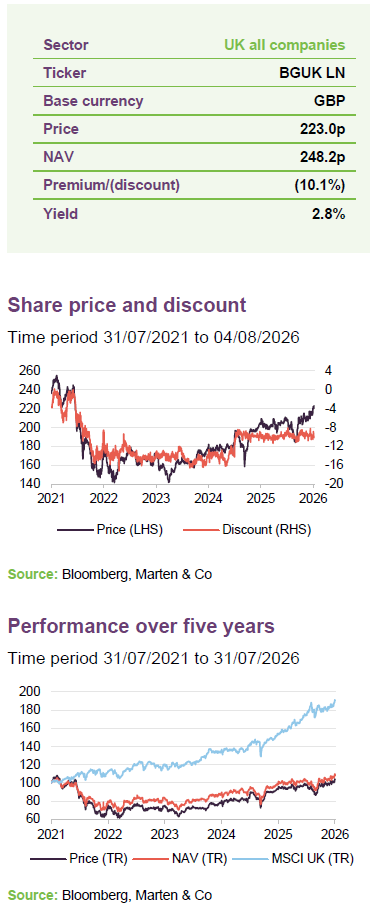
| 12 months ended | Share price TR (%) | NAV total return (%) | MSCI UK TR (%) | MSCI UK Growth TR (%) | MSCI World TR (%) |
|---|---|---|---|---|---|
| 31/07/2022 | (24.4) | (20.4) | 12.8 | 5.1 | 4.2 |
| 31/07/2023 | (0.7) | 4.4 | 6.8 | 5.6 | 8.0 |
| 31/07/2024 | 7.5 | 8.1 | 13.5 | 7.7 | 19.1 |
| 31/07/2025 | 18.5 | 13.2 | 12.7 | 8.8 | 12.8 |
| 31/07/2026 | 8.2 | 6.2 | 23.6 | 6.6 | 18.7 |
Fund profile
Focused UK growth equities portfolio
Further information can be found at Baillie Gifford’s website: www.bailliegifford.com
BGUK aims to deliver capital growth and outperform the FTSE All-Share Index by investing mainly in UK equities. It holds a relatively concentrated portfolio of 35 to 65 companies, most of which are constituents of the FTSE 350, although it may also invest outside the index.
Baillie Gifford has managed BGUK since the end of June 2018. The managers state that they use a conviction-led, stock-picking approach, with position sizes determined by their confidence in each company rather than its index weight. BGUK may also use convertible securities and equity-related derivatives for efficient portfolio management and can invest up to 10% of total assets in unlisted companies, measured at the time of investment.
BGUK’s benchmark is the FTSE All-Share Index, although the portfolio is managed without reference to any index. In this report, the MSCI UK Index is used as a proxy and performance is also compared with the MSCI UK Growth and MSCI World indices.
About the managers
Well-resourced investment team.
Baillie Gifford has 175 investors and analysts across 23 teams, most based in Edinburgh. Its partnership structure appears to support a collegiate investment culture, while portfolio managers retain final responsibility for their portfolios. At 30 June 2026, the firm managed or advised on around £197.4bn of assets, including £6.8bn in UK equities. BGUK is co-managed by Iain McCombie, Milena Mileva and James Smith (see page 17 for brief biographies).
Managers’ view
Sentiment towards growth stocks and the UK market continues to improve
Interest rate cuts are still coming through.
When we last published on BGUK in August 2025, we commented that sentiment towards growth stocks appeared to be improving, which was subsequently reflected in BGUK’s interim results for the six months to 31 October 2025. However, as we discuss in the performance section from page 10 onwards, value stocks appear to have had a resurgence, which may be a function of rising inflation and interest rate expectations as energy costs have increased following the outbreak of war in Iran. In addition, a swathe of software and platform businesses were affected by the “SaaSpocalypse” earlier this year – see below – which has been a further headwind to the approach.
Global capital appears to have continued to shift towards other developed markets, including Europe and the UK, which may reflect heightened uncertainty surrounding US government policy and its potential impact. However, despite growth stocks now delivering higher earnings growth, this has not been reflected in share prices and UK equities, particularly UK growth stocks, continue to trade at a significant discount relative to both historical levels and global peers. The managers believe that this disconnect between earnings growth and share prices cannot persist indefinitely, and have maintained gearing to seek to take advantage of it.
The manager states that backing high-quality growth companies while they are out of favour may offer better prospective returns than investing in areas whose recent performance may have been influenced by unusually favourable cyclical conditions. They have therefore viewed share price weakness as an opportunity to add to certain holdings.
AI selloff too indiscriminate?
BGUK’s managers state that the market’s response to AI may have been indiscriminate. Holdings including Autotrader, Rightmove, Experian and Softcat were derated as investors questioned whether AI might undermine their role in their respective industries. The managers accept that these businesses will have to adapt, but state that AI may not automatically replace the proprietary data, trusted brands, network effects, customer relationships and embedded workflows that underpin their competitive positions. In some cases, AI could make these assets more useful and easier to monetise, the managers add. The companies are already introducing AI-enabled products, and the managers describe the resulting weakness in their share prices as an opportunity rather than evidence that their investment cases have been broken.
Fundamental philosophy remains intact
The managers recognise that stock selection has not met expectations. A review by the board concluded that the trust has generally identified companies capable of delivering earnings growth, but has sometimes paid too high a price or been too slow to sell when valuations became stretched. With James Smith joining as a third co-manager, the intention is to place greater emphasis on portfolio construction, valuation and sell discipline, with turnover expected to increase from historically low levels. However, BGUK’s long-term growth philosophy remains intact.
Investment approach
Markets are inefficient at pricing long-term growth
Baillie Gifford believes markets often undervalue long-term growth, particularly over periods of five years or more, which it says may create opportunities to outperform. Its investment culture therefore emphasises long-term thinking and holding on to companies it considers successful, with management it considers strong and business models it considers durable.
Three-stage team-based approach
Baillie Gifford favours a team-based approach, and the firm states that teams make better decisions than individuals. This, they say, is supported by a culture of debate and constructive challenge. The firm is organised into a small number of investment teams pursuing different growth strategies. Its UK equities team follows a three-stage process: discovery, debate and decision.
Stage 1 – Discovery: Discovery is the idea-generation stage. Every six weeks, the team holds a prospects meeting to set its research priorities for the next six weeks. From a UK universe of more than 500 stocks, it maintains a priority list of around 200 companies. Portfolio managers and analysts are expected to conduct their own research, which may help to maintain accountability for investment decisions. Team members bring early-stage ideas to the prospects meeting for open and constructive discussion. These conversations determine which ideas merit deeper research.
A stock will only be researched in depth if it has a credible long-term growth case.
A stock is only researched in depth if it appears to have a credible long-term growth case, although the team also considers other businesses when assessing competitors and industry dynamics. Analysts can draw on external research and colleagues across Baillie Gifford, but are encouraged to pursue ideas that interest them. They are generalists rather than sector specialists, and there is no routine “maintenance research” from a prescribed list of stocks.
‘Debate’ is the most important stage.
Stage 2 – Debate: Debate is described as a key stage of the investment process. It centres on a concise investment note, limited to three pages for the UK equities team, to keep the analysis focused and to set out a recommendation. Supporting material can be added in appendices. Each note is structured around Baillie Gifford’s five-question framework:
- Edge – why is a stock interesting? This focuses on the industry background, company-specific factors, competitive position, and key issues pertinent to the investment case.
- Growth – what may it look like in five years? This focuses on sales, profit margins and capital allocation.
- Sustainability – what, if any, ESG factors are material to the investment case? Consider both opportunities and risks. This focuses on climate impact, sustainable business practices, board structures, and management alignment.
- Valuation – should we own it? This focuses on the company’s valuation, the factors that may influence how a company trades, and the likely valuation in five years and beyond.
- Discipline – what would make us sell? This focuses on the key risks and any non-negotiables of the investment case.
Another team member is appointed as a devil’s advocate to challenge assumptions and help test the final recommendation.
Stage 3 – Decision: The team discusses every stock, but the lead managers make the final portfolio decisions. This process combines team debate with individual accountability.
Sell discipline: The managers will sell if they lose confidence in a company’s management, believe its business model is failing, or judge that the market has fully recognised its growth potential.
Asset allocation
Portfolio is radically different to the benchmark.
As at 30 June 2026, BGUK held 36 companies, unchanged in number from 30 June 2025 (the most recently available information when we last published). The industry breakdown in Figure 1 shows the range of ideas within the portfolio. Despite its UK all-cap remit, there are large parts of the market that BGUK has no exposure to, which appears consistent with a concentrated growth portfolio built without reference to the benchmark.
Figure 1: Industry allocation as at 30 June 2026
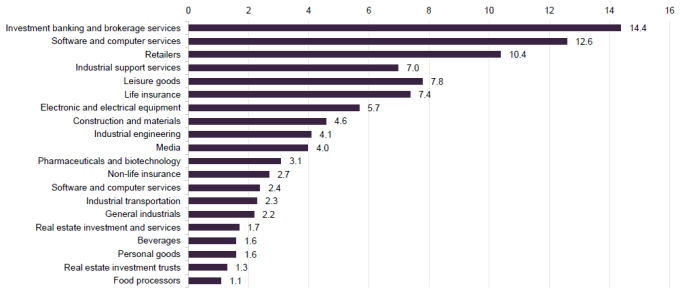
Although BGUK is a long-term, low-turnover portfolio, its sector exposure changes gradually. Since our last report, the largest increases have been in industrial engineering (+2.1 percentage points), investment banking and brokerage services (+1.7 points) and media (+1.3 points). The largest reductions have been in industrial support services (-4.4 points), life insurance (-2.2 points), construction and materials (-1.6 points) and real estate investment and services (-1.2 points). All other changes were one percentage point or less. Reflecting its concentrated, stock-specific approach, BGUK’s active share remains high at 92%, broadly in line with its long-term average.
BGUK’s portfolio differs markedly from the benchmark. It has traditionally traded at a valuation premium, which may reflect stronger expected earnings and sales growth, and also retains a pronounced mid-cap bias. This is not a deliberate allocation decision, but the result of bottom-up stock selection and where the managers have found what they believe to be the most attractive opportunities.
Portfolio activity
Reflecting the managers’ low-turnover approach, the number of stocks entering and exiting the portfolio in a given year is likely to be limited. For example, during the year ended 30 April 2026, just three positions were exited in their entirety: FD Technologies, which was acquired by TA Associates in July 2025; FDM Group was exited entirely as the managers felt that the long-term growth case had weakened (strategic growth initiatives had disappointed, particularly attempts to expand overseas and AI may have increased uncertainty around the medium-term outlook for the demand for junior technology consultants and IT staffing services); and Just Group was acquired by Brookfield Wealth Solutions in April 2026. There have been two new additions to the portfolio – Spirax and Greggs – which are discussed below.
Spirax Group – world-class industrial compounder that’s cyclically, rather than structurally, depressed
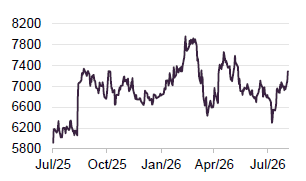
Figure 2: Spirax share price (GBp)
Spirax Group (www.spiraxgroup.com) is a specialist engineering company focused on thermal-energy management and fluid technology. It supplies steam-control systems, electric thermal solutions and precision pumps for demanding industrial processes where reliability, efficiency and technical support are critical. Its network of around 2,000 specialist sales engineers works closely with customers to identify inefficiencies, design tailored systems and improve safety, productivity and energy efficiency. BGUK’s managers believe this creates durable customer relationships, recurring aftermarket revenues, pricing power, high barriers to entry and opportunities to sell additional products over time. Spirax operates in fragmented specialist markets, which may give it scope to take share from smaller competitors. It also appears to benefit from structural growth themes including industrial decarbonisation, electrification and biopharmaceutical production.
The shares weakened as demand normalised after unusually strong pandemic-era growth, while customer destocking and subdued industrial activity added further pressure. The market appears to have interpreted this as evidence that Spirax’s historic growth rate may no longer be sustainable. BGUK’s managers state that they disagree, and view the slowdown as cyclical rather than a sign of weakening competitive advantages or long-term prospects.
They invested following the de-rating, stating that it offered an entry point into a business they consider high-quality. As industrial spending recovers, Spirax may benefit from stronger organic growth, improved factory utilisation, margin recovery, continued market-share gains and selective acquisitions. This may create potential for returns from both earnings growth and a recovery in the valuation multiple.
Greggs – a value-led consumer growth business with a meaningful store-opening runway
Greggs (www.greggs.com) is a UK bakery-led food-on-the-go retailer, with shops across high streets, retail parks, transport hubs, roadside sites and drive-throughs. Its vertically integrated model, under which it manufactures and distributes much of its own food, may give it greater control over quality, availability and costs. Growth appears to be supported by new shop openings, longer trading hours and expansion into evening and delivery.
Figure 3: Greggs share price (GBp)
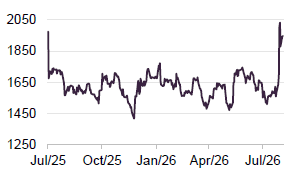
BGUK’s managers state that Greggs is sometimes described as a mature bakery chain, particularly given slower like-for-like sales growth and recent margin pressure. Weaker consumer spending and rising ingredient, energy and wage costs have been headwinds, but margins also appear to have been affected by a major investment programme designed to support future growth.
Greggs has invested over £1bn between 2022 and 2026 in manufacturing and distribution capacity. These facilities carry costs before reaching efficient utilisation, but may support a larger shop estate and higher sales volumes as capacity fills. The managers believe Greggs’ brand and value proposition remain its main growth drivers. Vertical integration may provide a cost advantage, while recent investment appears to have strengthened its operational position. As capex moderates, efficiency, cash generation and returns from new shops may improve, which could support earnings growth over the next five years and beyond.
Top 10 holdings
Figure 4: Top 10 holdings as at 30 June 2026
| Holding | Sector | Business | Portfolio weight 30 June 2026 (%) | Portfolio weight 30 June 2025 (%) | Percentage point change |
|---|---|---|---|---|---|
| Games Workshop | Consumer discretionary | Tabletop games manufacturer/retailer | 7.8 | 6.7 | 1.1 |
| AJ Bell | Financials | UK wealth manager | 5.4 | 5.0 | 0.4 |
| Volution Group | Industrials | Ventilation equipment supplier | 4.6 | 6.1 | (1.5) |
| Softcat | Technology | IT reseller and infrastructure solutions | 4.5 | 3.5 | 1.0 |
| Wise | Financials | Online global FX money transfer | 4.1 | 4.7 | (0.6) |
| Howden Joinery | Industrials | Manufacturer/distributor of kitchens to trade | 4.1 | 4.1 | – |
| 4imprint | Communications | Promotional merchandise | 4.1 | 2.6 | 1.5 |
| Renishaw | Industrials | Metrology products | 4.0 | 2.4 | 1.6 |
| Legal & General | Financials | Insurance and investment management | 4.0 | 3.3 | 0.7 |
| Moonpig Group | Consumer discretionary | Online greetings card and gifting platform | 3.7 | 3.2 | 0.5 |
| Total of top five | 26.4 | 28.6 | (2.2) | ||
| Total of top 10 | 46.4 | 48.3 | (1.9) |
Figure 4 shows BGUK’s top 10 holdings as at 30 June 2026 and how these have changed since 30 June 2025 (the most recently available data when we last published). Reflecting the managers’ long-term, low-turnover approach, most of the top 10 portfolio holdings may be familiar to regular followers of BGUK’s portfolio announcements and our research on the trust.
Figure 5: Games Workshop share price (GBp)
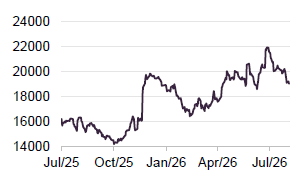
New entrants to the top 10 are 4imprint, Renishaw, Legal & General and Moonpig. Names that have moved out of the top 10 are Autotrader, Experian, St. James’s Place and Just Group. We discuss some of these developments in the next few pages. Other holdings have been discussed in our previous notes.
Games Workshop (7.8%) – trimmed on the back of strong performance
Games Workshop (www.warhammer.com) is a British manufacturer of products for playing fantasy tabletop games, using figurines that customers paint themselves, and is known for its Warhammer and Warhammer 40,000 series of products.
Games Workshop has been trimmed following strong performance. However, BGUK’s managers state that they continue to favour the company, citing its pricing power, high margins, expanding international footprint and the potential opportunities to monetise the Warhammer intellectual property through licensing and its partnership with Amazon.
AJ Bell (5.4%) – benefitting from a shift towards self-directed retirement investing
Figure 6: AJ Bell share price (GBp)
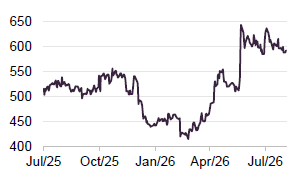
AJ Bell (www.ajbell.co.uk) provides a share dealing platform and related financial services and products to investors, serving both B2B and D2C segments in the UK. The company states that it has positioned itself as a low-cost provider and has been growing its market share at a time when some of its peers appear to have struggled to remain competitive.
Like Games Workshop above, AJ Bell is another holding that has been trimmed following a strong performance. BGUK’s managers state that they remain positive on the outlook for the company which, in their view, is likely to be one of the long-term winners from the shift towards self-directed retirement saving, supported by its scale, customer service and competitive pricing.
Volution Group (4.6%) – benefitting from a structural trend to improve air quality
Figure 7: Volution share price (GBp)
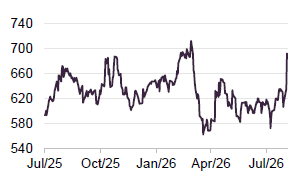
Volution Group (www.volutiongroupplc.com) manufactures and supplies ventilation products and indoor air-quality products, from simple extractor fans to more complex heat recovery solutions. Its primary markets are the UK, Continental Europe and Australasia, where it operates through 17 different brands split across these different regions. As discussed in the last two notes, BGUK’s managers identify a long-term structural trend of efforts to improve air quality, with demand for Volution’s products potentially benefiting from environmental regulations in building and construction. The managers state that Volution’s heat recovery ventilation solutions are helping customers to meet new energy efficiency building standards. BGUK’s managers have trimmed the position following strong performance, but they remain positive on the company as they believe these structural trends could boost Volution’s organic growth for years come.
Softcat (4.5%) – position added to following AI-related sell off
Figure 8: Softcat share price (GBp)
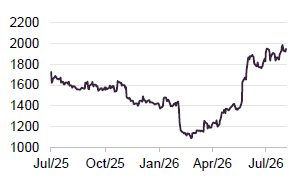
Softcat (www.softcat.com) is a value-added reseller of IT infrastructure (both software and hardware), primarily to SMEs in the UK. It has around 10,200 active customers, including BGUK’s manager, and may benefit from the long-term structural trend of growing IT expenditure. As discussed previously, Softcat’s rate of staff attrition is low relative to peers, which may differentiate it from peers and may allow Softcat to foster customer relationships.
Softcat reported 23% growth in gross profit and 27% growth in operating profit in its January half-year results, and management upgraded its full-year profit guidance. Despite this, the shares had been de-rated, as investors appeared to fear that AI could reduce the need for IT resellers and other channel partners. BGUK’s managers stated that they believed those concerns to be misplaced and added to the position. In their view, AI appears to be making enterprise IT more complicated by adding challenges around cloud architecture, data readiness, governance, compliance and cybersecurity. This may increase the need for Softcat’s advice and its ability to help customers navigate a complex, multi-vendor technology environment.
Wise (4.1%) – taking substantial market share from incumbents
Figure 9: Wise share price (GBp)
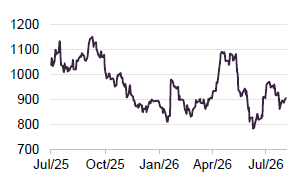
Wise (wise.com) is a London-based foreign exchange transfer business that provides an online platform to send and receive money internationally at low cost. By maintaining local accounts and connecting directly to payment systems in more than 80 countries, Wise may be able to transfer money more quickly and cheaply than traditional correspondent banks. BGUK’s managers state that as volumes grow, Wise’s unit costs fall, enabling it to reduce prices further and attract additional customers, in what they describe as a virtuous circle.
BGUK’s managers believe that Wise still has a long runway. Despite processing about £180bn of payments, Wise handles around 5% of consumer cross-border transfers and less than 1% of the SME market. They believe that growth could come from gaining customers, entering additional markets and securing more partnerships with banks that opt to use Wise’s infrastructure rather than their own.
Performance
Figure 10: BGUK’s NAV total return relative to various indices, over five years to 31 July 2026
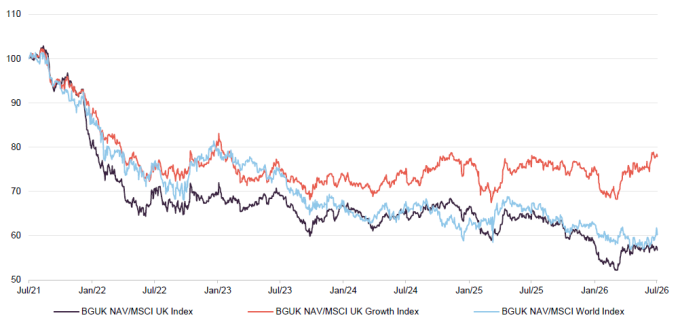
Figure 11: Cumulative total return performance over periods ending 31 July 2026
| 3 months (%) | 6 months (%) | YTD (%) | 1 year (%) | 3 years (%) | 5 years (%) | BG tenure1 (%) | 10 years (%) | |
|---|---|---|---|---|---|---|---|---|
| BGUK NAV | 6.4 | 6.0 | 6.4 | 6.2 | 29.9 | 8.0 | 37.0 | 67.6 |
| BGUK share price | 6.3 | 6.3 | 7.8 | 8.2 | 37.8 | 3.5 | 34.7 | 73.1 |
| MSCI UK | 5.2 | 8.5 | 11.8 | 23.6 | 58.1 | 90.4 | 93.5 | 136.5 |
| MSCI UK Growth | 0.9 | 2.6 | 2.3 | 6.6 | 24.9 | 38.7 | 77.5 | 99.4 |
| MSCI World | 5.3 | 10.0 | 10.4 | 18.7 | 59.5 | 79.5 | 168.0 | 242.2 |
Up-to-date information on BGUK and its peers is available on the QuotedData website.
As discussed in previous notes, there has been disruption in financial markets since Baillie Gifford took over the management of the trust in June 2018. However, as illustrated in Figure10, rising inflation and interest rate expectations in the latter part of 2021 and the first half of 2022 appears to have had the greatest impact on growth stocks and hence BGUK’s relative NAV and share price performance. This subsequently stabilised, as inflation appeared to be brought under control and interest rates receded, but the gap expanded again as inflation and interest rate expectations increased, potentially first with Trump’s Liberation Day tariffs and more recently the war in Iran. The manager states that there may still be significant catch-up potential.
Results for the year ended 30 April 2026
For its financial year ended 30 April 2026, BGUK reported NAV and share price total returns of 15.6% and 18.2% respectively. In comparison, the broader MSCI UK Index returned 26.6% and the MSCI UK Growth Index 10.9%. BGUK’s NAV total return was below that of its All-Share benchmark (which BGUK’s annual report says returned 25.2%), which BGUK attributes largely to its lack of exposure to oil & gas, mining and banks. Stock selection also appears to have been a negative contributor, with platform and software related businesses derated on fears of disruption from AI during the second half of the financial year.
Top positive contributors for the year to 30 April 2026
Figure 12: Top five positive contributors to relative returns
| Stock | Total return (%)1 | Contribution (%) |
|---|---|---|
| Renishaw | 115.9 | 1.7 |
| Just Group | 56.2 | 1.5 |
| Unilever2 | (13.0) | 1.3 |
| Molten Ventures | 111.0 | 1.0 |
| 3i2 | (38.2) | 0.9 |
Figure 12 lists the top five contributors to performance for the year ended 30 April 2026. As noted above, Just Group was acquired during the year. Unilever and 3i feature in the list because both performed poorly during the period, and neither was held within BGUK’s portfolio.
Figure 13: Renishaw share price (GBp)
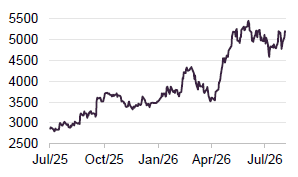
Renishaw is a British engineering group specialising in precision measurement, additive manufacturing and analytical instruments. Its products serve industries including aerospace, electronics and healthcare, where it supplies metal 3D-printing and neurosurgical systems. During BGUK’s FY2025, Renishaw appears to have performed poorly; its February 2025 interim results missed expectations and the company appeared to respond negatively to Trump’s tariff plans in April 2025. In FY2026, the company performed strongly as the tariff threat receded and the underlying business appeared to be resilient. BGUK’s managers have trimmed the position, but consider the long-term investment case to remain intact. They cite several structural growth drivers: increasing factory automation; greater precision in semiconductor and aerospace manufacturing; reshoring and localisation of production; and growth in metal additive manufacturing.
Figure 14: Molten Ventures share price (GBp)
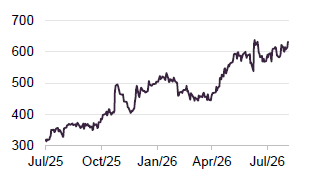
Molten Ventures (moltenventures.com) is a closed-end investment company focused on providing venture capital to UK and European technology companies. It is an early-stage investor, participating in series A fundraising rounds and onwards (these funding rounds generally follow “seed funding”). BGUK’s managers state that their rationale for holding Molten Ventures is that the manager has a generally positive track record of growing its NAV and achieving realisations with its investments. In addition, private companies have been out of favour, which has been reflected in Molten’s trading at a significant discount to NAV, while the vast majority of its core portfolio has performed in line with or above expectations. This view appeared to be supported during FY2026, as the operational performance of its biggest investments was strong and its discount to NAV narrowed.
Top detractors for the year to 30 April 2026
Figure 15 lists the top five detractors from for the year ended 30 April 2026. Softcat is discussed in the asset allocation section. With the exception of HSBC, which features as it performed well during the period and was not held by BGUK, all the other large detractors were hit by the “SaaSpocalypse”.
Figure 15: Top five negative contributors to relative returns
| Stock | Total return (%)1 | Contribution (%) |
|---|---|---|
| Autotrader | (40.0) | (3.5) |
| HSBC2 | 115.9 | (2.2) |
| Experian | (26.7) | (1.9) |
| Rightmove | (40.0) | (1.6) |
| Softcat | (15.4) | (1.3) |
Peer group
BGUK sits in the five-member UK All Companies sector, shown in Figures 16 and 17. Although the sector is growth-focused, BGUK has a particularly strong growth bias. Fidelity Special Values and Aurora UK Alpha lean more towards value, while Schroder UK Mid Cap and Mercantile invest further down the market-cap spectrum.
Peer group performance
Please click here to visit QuotedData.com for a live comparison of the UK all companies peer group.
Baillie Gifford took over BGUK’s management at the end of June 2018, following a period of weak relative performance under the previous manager. Parts of the subsequent eight years have been challenging for markets generally and for growth stocks in particular. UK equities have also been out of favour with international investors, with smaller companies particularly affected, which may have weighed on the sector’s longer-term performance. BGUK’s growth bias may have left it more exposed than most.
Figure 16: Peer group cumulative NAV total return performance (annualised) to 31 July 2026
| 1 month (%) | 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | 10 years (%) | |
|---|---|---|---|---|---|---|---|
| BGUK | 3.0 | 6.4 | 5.0 | 6.5 | 9.0 | 1.1 | 4.9 |
| Aurora UK Alpha | 2.2 | 11.3 | (4.6) | 3.7 | 6.6 | 5.5 | 7.8 |
| Fidelity Special Values | 6.6 | 9.0 | 6.1 | 19.9 | 20.0 | 13.4 | 11.1 |
| Mercantile | 2.7 | 4.4 | 5.1 | 11.4 | 12.5 | 1.9 | 6.4 |
| Schroder UK Mid Cap | 8.1 | 5.6 | 0.3 | 7.9 | 10.1 | 2.8 | 6.9 |
| BGUK rank | 3/5 | 3/5 | 3/5 | 4/5 | 4/5 | 5/5 | 5/5 |
| Sector median | 3.0 | 6.4 | 5.0 | 7.9 | 10.1 | 2.8 | 6.9 |
More recently, investors appear to have begun to look beyond the US, aside perhaps from the small group of mega-cap technology stocks that has driven much of that market’s performance. The UK appears to have benefitted, led so far by larger companies. Although inflation has recently risen, the broader trend might still favour lower interest rates as central banks respond to slowing economies. This might also support growth stocks.
As Figure 17 shows, BGUK is the smallest trust in the sector by market capitalisation, although it is similar in size to Aurora and Schroder UK Mid Cap. Despite widespread share buybacks, the sector’s average market capitalisation has risen slightly since our last report. BGUK has the sector’s second-widest discount, although it is similar to those of Aurora and Mercantile.
BGUK’s ongoing charges are slightly above the peer-group average. However, this average is lowered by Aurora, which charges no base management fee but does levy a performance fee, and Mercantile, whose much larger size provides economies of scale. BGUK’s gearing, measured at the end of June 2026, is above the sector average. Like most of its peers, it does not charge a performance fee. BGUK has traditionally offered a relatively low yield, slightly below the sector average, although it is currently modestly above it.
NAV volatility has fallen across the sector since our last note. BGUK has historically had one of the lowest levels of long-term volatility in the peer group, but has slipped down the rankings as volatility among some peers has fallen more quickly.
Figure 17: Peer group comparison – size, ongoing charges, discount, and yield as at 4 August 2026
| Market cap (£m) | Ongoing charges (%) | Perf. fee | Premium/ (discount) (%) | Dividend yield (%) | Net gearing (%) | |
|---|---|---|---|---|---|---|
| BGUK | 237 | 0.76 | No | (10.2) | 2.8 | 8 |
| Aurora UK Alpha | 275 | 0.351 | Yes1 | (11.7) | 1.8 | 0 |
| Fidelity Special Values | 1,520 | 0.68 | No | 0.7 | 2.0 | 6 |
| Mercantile | 1,777 | 0.49 | No | (9.7) | 2.9 | 12 |
| Schroder UK Mid Cap | 250 | 0.92 | No | (5.5) | 2.9 | 3 |
| BGUK rank2 | 5/5 | 4/5 | 4/5 | 3/5 | 2/5 | |
| Sector median | 275 | 0.68 | (9.7) | 2.8 | 6 |
Dividend
BGUK’s priority is capital growth, with dividends paid to the extent required to maintain its investment trust status. Despite the UK market’s traditionally higher yield, income is therefore likely to make up only a small part of shareholders’ total returns. The trust pays one final dividend each year following approval at the AGM, usually in September. For the year ended 30 April 2026, the board has proposed a final dividend of 6.2p per share, up from 5.7p in 2025. This equates to a yield of 2.8% based on the 223.0p share price at 4 August 2026. Revenue earnings of 6.23p per share covered the dividend.
Figure 18: BGUK revenue income and dividend by financial year (ended 30 April)1
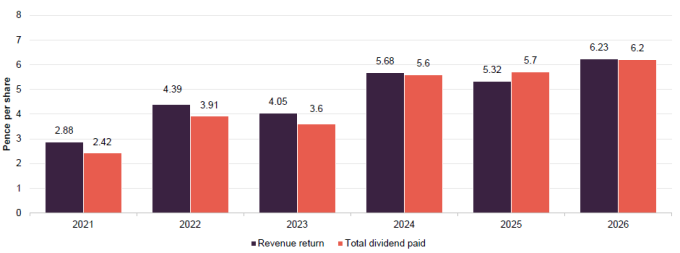
Revenue earnings have exceeded dividends in recent years, allowing BGUK to build its revenue reserve. At 30 April 2026, this stood at £17.9m, or 16.53p per share, compared with £17.6m, or 13.57p per share, two years earlier. BGUK may also pay dividends from capital profits.
Premium/(discount)
Figure 19: BGUK premium/(discount) over five years to end July 2026
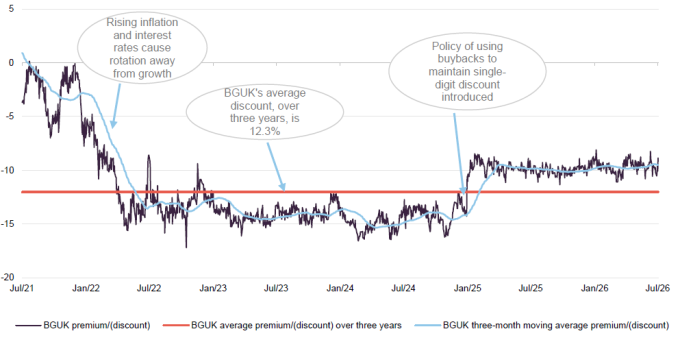
On 28 January 2025, BGUK announced an updated buyback policy whereby share repurchases would be used with the aim of maintaining a single digit discount to the trust’s NAV per share, in normal market conditions. As illustrated in Figure 19, this policy appears to have been effective with a step in BGUK’s discount since its introduction. There has been an increase in buybacks since the policy’s introduction. Figure 19 also illustrates that the discount has been less volatile since the policy’s introduction.
In the year prior to the policy’s introduction, BGUK traded at an average discount of 14.5%, and moved with a discount range between 10.9% and 16.6%. Since the policy’s introduction, the average discount has been 9.8%, with the discount moving in a range between 8.1% and 11.3%. As at 4 August 2026, BGUK was trading at a discount of 10.1%.
Structure
Fees and costs
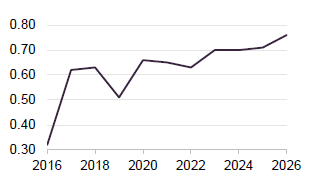
Figure 20: BGUK ongoing charges ratio (%)1
UK Growth Trust Note: 1) For financial years ended 30 April.
BGUK’s board has secured a temporary cut in its management fee from 0.50% to 0.40% of NAV, effective from 1 July 2026 until 30 April 2029, the calculation date for the trust’s performance-triggered tender offer. It is then expected to revert to 0.50%, assuming the trust continues following the tender process. There is no performance fee, and the management agreement can be terminated by Baillie Gifford with six months’ notice and by BGUK with three months’ notice. The manager also provides company secretarial and administrative services, all covered by this fee.
The management fee is split 30% to revenue and 70% to capital, reflecting the board’s view of the long-term balance of returns. The ongoing charges ratio for the year to 30 April 2026 was 0.76%, 5bp higher than 0.71% a year earlier, despite a reduction in overall costs, largely due to the impact of share buybacks.
Capital structure and life
BGUK has one class of ordinary share listed on the London Stock Exchange’s premium segment. At 31 July 2026, it had 112,484,853 shares in issue, of which 6,332,402 were held in treasury and 106,152,451 were in general circulation. The trust may borrow, subject to a net gearing limit of 20% of net assets. The board reviews gearing limits periodically to assess whether they remain appropriate for market conditions.
BGUK has a significant retail presence on its share register.
BGUK has a retail presence within its share register, with major direct-to-consumer platforms accounting for around 25% of the register. Wealth managers and intermediaries represent a further 35%.
BGUK shareholders vote on its continuation every five years at the AGM. The next vote is due in 2029, although an additional vote will be held in 2027. A performance-triggered tender is also planned for 2029 if BGUK’s NAV per share underperforms the All-Share over the five years to 30 April 2029.
BGUK’s year-end is 30 April, its annual results are usually released in June or July (interims in November or December), and its AGMs are usually held in September. BGUK pays one final dividend, after the AGM, if required.
Management team
Iain McCombie joined Baillie Gifford in 1994 and has spent the majority of his career as an investment manager in the UK equity team. He became a partner in 2005. Iain graduated with an MA in Accountancy from the University of Aberdeen, and qualified as a Chartered Accountant.
Milena Mileva joined Baillie Gifford in 2009 and is an investment manager in the UK equity team. She became a partner in 2022. Milena graduated with a BA in Social & Political Sciences from the University of Cambridge in 2007 and an MPhil in Politics from the University of Oxford in 2009.
James Smith joined Baillie Gifford in 2022, and prior to joining the firm, worked as a senior investment manager at ADIA in Abu Dhabi covering UK Equities, having begun his career at Martin Currie in Edinburgh in 2012. James graduated with a BSc (Hons) in Economics from UCL in 2010.
Board
All directors retire and stand for re-election annually.
BGUK’s board comprises five non-executive directors, all considered independent of the investment manager. Newly appointed directors must stand for election at the next AGM, while all directors retire and seek re-election annually. The directors have served for an average of 5.2 years. Andrew Westenberger, chair of the audit committee, is the longest-serving director, with 9.3 years on the board, and is not standing for re-election at September’s AGM. Seema Patterson will become audit chair following his retirement. The directors have no other shared directorships. The company’s articles cap total annual directors’ fees at £250,000. Average fees for individual board roles have increased by 6.7% for the current financial year compared with FY26.
Figure 21: Board member – length of service and shareholdings
| Director | Position | Date of appointment | Length of service (years) | Annual fee (GBP)1 | Shareholding2 | Years of fee invested3 |
|---|---|---|---|---|---|---|
| Neil Rogan | Chairman | 1 January 2024 | 2.6 | 49,200 | 135,607 | 6.1 |
| Andrew Westenberger | Chair of the audit committee | 5 May 2017 | 9.3 | 39,800 | 20,000 | 1.1 |
| Ruary Neill | Senior independent director | 15 November 2018 | 7.7 | 34,300 | 36,707 | 2.4 |
| Cathy Pitt | Director | 5 August 2021 | 5.0 | 32,800 | 21,501 | 1.5 |
| Seema Paterson | Director | 2 January 2025 | 1.6 | 32,800 | 20,000 | 1.4 |
| Average (service length, annual fee, shareholding, years of fee invested) | 5.2 | 37,780 | 46,763 | 2.5 |
Since our last report, three BGUK directors have made share purchases. Neil Rogan bought 50,746 shares at 204.0p on 3 December 2025, Catherine Pitt bought 5,014 shares at 198.3p on 5 March 2026, and Seema Paterson bought 10,000 shares at 212.51p on 1 July 2026. All BGUK directors hold shares in the company, and on average their holdings are equivalent to 2.5 years of fees, up from 1.8 years when we last published.
Neil Rogan (chairman) was appointed to BGUK’s board in January 2024 and became chairman on 14 June 2024. He is also chairman of Invesco Asia Trust and a director of JPMorgan Global Growth & Income Trust. Previously, he held investment roles at Touche Remnant, Flemings and Gartmore/Henderson, where he was head of global equities. He has also chaired Murray Income Trust and served as a director of The Scottish Investment Trust.
Andrew Westenberger (chairman of the audit committee) joined BGUK’s board in 2017 and has chaired the audit committee since then. He is chief executive of Hurst Point Group. Previously, he was chief financial officer of Tysers Insurance Brokers and group finance director of Brewin Dolphin Holdings and Evolution Group. He has also served as a non-executive director and trustee of the Chartered Institute for Securities & Investment and held senior finance roles at Barclays Capital and Deutsche Bank. Andrew is a chartered accountant.
Ruary Neill (senior independent director) joined BGUK’s board in 2018 and became senior independent director in 2021. He is also a director of JPMorgan Emerging Markets Investment Trust. Previously, he worked in investment banking at UBS and held roles in Asian equity markets at UBS and Schroder Securities.
Cathy Pitt (director) joined BGUK’s board in 2021. A former consultant partner at the law firm CMS, she has over 20 years’ experience advising boards and asset managers on corporate matters. She is also a non-executive director of Gresham House Energy Storage Fund and the deputy chair of the Association of Investment Companies.
Seema Paterson (director) joined BGUK’s board in 2025. She is chief financial officer and a board director of This Works Products, chairs the audit committee of CQS Natural Resources Growth and Income, and serves on the board of youth employment charity Resurgo Trust. Previously, she worked in mergers and acquisitions at Société Générale and corporate finance at Collins Stewart. Seema is a chartered accountant and will – as mentioned above – take on the role of audit chair for BGUK later this year. Seema will also become a non-executive director of AVI Global Trust Plc with effect from 1 September and chair of its audit committee when the incumbent retires.
Previous publications
Figure 22: QuotedData’s previously published notes on BGUK
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Baillie Gifford UK Growth Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.