
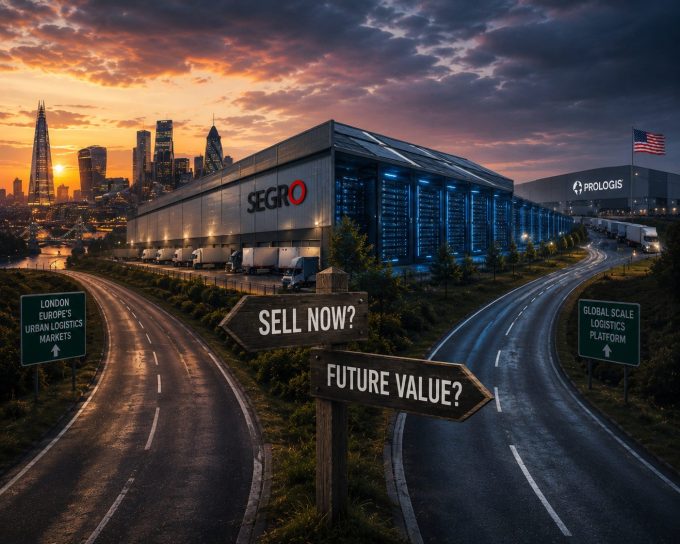
It looks like the UK’s largest REIT – and one of the sector’s great success stories, SEGRO, will be gobbled up by a US warehouse behemoth in a deal worth around £14bn. SEGRO’s board says that it is minded to recommend a ‘best and final’ offer from Prologis, after a rollercoaster couple of weeks of to-and-fro.
SEGRO’s board performed a drastic turnaround – from a unanimous rejection to acceptance in a matter of days – for an offer upped by just 3.9%. But its hand seems to have been forced by some of its largest shareholders, which had publicly put the pressure on to get a deal done.
My feeling is this latest offer will be enough to get it over the line. At 1,031.7p, it is a tidy premium to its 905p NAV and above the undisturbed share price by almost 40%. It is irksome that SEGRO’s share price was languishing at such low levels – but it could be argued that it only has itself to blame for that.
It took Prologis going public with details of its initial offer in June for SEGRO to come out and put some real meat on the bone of the potential growth prospects of its portfolio. CEO David Sleath set out the company’s earnings and valuation growth projections in an analyst presentation in early July.
It was the previous lack of this sort of detail that may have contributed to its lowly rating – although there is a lot of credence to the argument that this bid is opportunistically timed to coincide with share price weakness caused by the Iran war. Also, listed UK property companies have struggled to command market valuations that properly reflect their long-term development opportunities. In that sense, the proposed takeover says as much about the London market as it does about SEGRO.
In its response to Prologis, SEGRO laid out the scale of the opportunity embedded within the business: a development pipeline capable of delivering hundreds of millions of pounds of additional rent, an irreplaceable portfolio concentrated in Europe’s most land-constrained urban logistics markets, and – perhaps most valuable of all – a scarce data centre pipeline.
It believes that its near-term data centre platform would add 139p (£1.9bn) to NAV, while its logistics development pipeline would add a further 103p (£1.4bn). With additional value from future data centre and logistics developments and organic portfolio rental growth, the company says there is a credible route to a valuation of 1,311p.
If shareholders believe those projections, then accepting a modest premium to today’s NAV inevitably raises the question of who will ultimately enjoy that future upside.
That is particularly true when it comes to data centres. What was once viewed as a useful adjacent opportunity has increasingly become one of SEGRO’s defining attractions. The company has assembled a substantial landbank capable of supporting significant power-enabled development in locations where planning permission, grid connectivity and land availability are becoming ever harder to secure.
Taking the 139p of value that CBRE has ascribed to SEGRO’s near-term data centre pipeline (the majority of which should be available to lease within the next two years) brings the theoretical NAV to 1,044p – above Prologis’s best and final offer, without the extra from SEGRO’s proven logistics development platform.
Key to Prologis’s case is its criticism of SEGRO’s reliance on project-level joint ventures, such as its agreement with Pure Data Centres, arguing that “SEGRO shareholders will give away significant value and upside to joint venture partners … at high leverage due to balance sheet constraints”.
Losing a UK real estate giant
If SEGRO were to go, a large hole will be made in the listed real estate space – with the company making up around 23% of the sector by market cap. In recent years, the company has been synonymous with the e-commerce boom. However, its roots stretch back to 1920, when it founders – Lord Percival Perry, Redmond McGrath and Noel Mobbs – acquired the former First World War military vehicle depot at Slough. As surplus workshops were let to manufacturers and traders, the Slough Trading Estate became arguably the world’s first modern industrial estate and the foundation of what would become SEGRO.
Over more than a century, the business has repeatedly reinvented itself. It evolved from servicing manufacturers to accommodating technology companies, from owning a sprawling collection of industrial, office and retail assets to becoming a focused logistics specialist, and now from warehouse landlord to a provider of the physical infrastructure underpinning both digital commerce and artificial intelligence.
The Slough Trading Estate itself illustrates that evolution. Once synonymous with factories, it is now home to one of the world’s largest concentrations of data centres.
Much of that transformation occurred under Sleath, whose strategy of simplifying the portfolio, recycling capital and concentrating on urban logistics looked unfashionable at the time but ultimately proved prescient.
Long before “last-mile logistics” became investment jargon, SEGRO was assembling assets in supply-constrained locations close to Europe’s largest population centres. When online retail accelerated during the pandemic, the company was perfectly positioned to benefit. More recently, it has sought to repeat that playbook by positioning itself early in data centre infrastructure.
Which perhaps explains Prologis’ persistence. Combining the world’s largest logistics property owner with Europe’s premier urban logistics platform creates obvious strategic logic. The question for SEGRO shareholders is whether that logic is worth surrendering for a premium of little more than 14% to NAV.
A good offer at 14% premium to NAV We have lost a few trusts that didn’t even make NAV. I will be voting YES. The Picton Property bid is a prime example.