
The endgame?
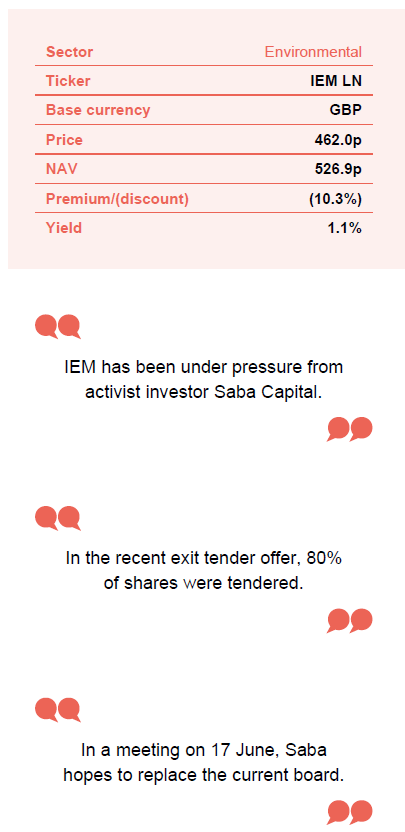
Impax Environmental Markets (IEM) has produced poor investment performance and is under pressure from activist hedge fund Saba Capital. In May, an exit tender offer saw about 80% of shares tendered. The fund, now much smaller, faces a Requisitioned General Meeting (RGM) on 17 June, where Saba aims to replace the entire IEM board with its own nominees.
IEM’s chairman has said that Saba now effectively controls the fund’s strategy, making it likely that Saba’s proposals will be approved. If so, this will end the current board’s tenure and start a new phase for IEM. There is little detail on what changes might follow; Saba has only said that the new board will focus on delivering long-term value for shareholders.
Capital growth and a more sustainable world
IEM is designed to enable investors to benefit from a highly differentiated, well-researched, and diversified portfolio of fast-growing, globally listed companies providing innovative solutions to environmental challenges or improving resource efficiency.
At a glance
Share price and discount
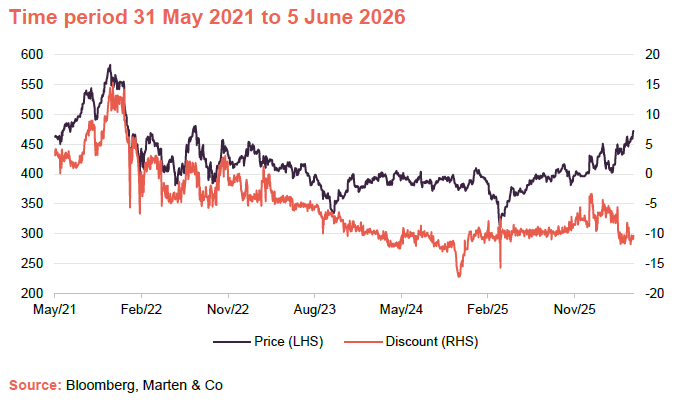
IEM’s five-year performance relative to the global index has been disappointing. The shares suffered significantly in 2022, against a backdrop of rising inflation and interest rates. They then stabilised, without ever truly recovering, although performance over the past year has been stronger. The discount has widened over time.
Performance over five years
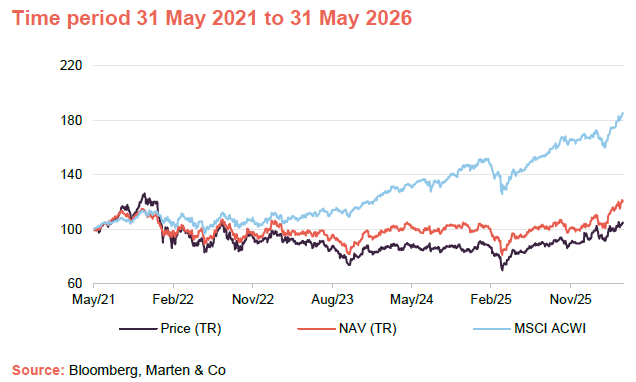
Both IEM’s share price and net asset value (NAV) performance have been consistently behind global indices as measured by the MSCI All Countries World Index (MSCI ACWI). Global equities have been driven by technology companies outside IEM’s remit, while IEM’s investment style has been somewhat out of favour.
| Year ended | Share price total return (%) | NAV total return (%) | MSCI ACWI total return (%) |
|---|---|---|---|
| 31/05/2022 | (7.7) | (1.6) | 5.4 |
| 31/05/2023 | (3.6) | (3.0) | 3.3 |
| 31/05/2024 | (0.6) | 6.8 | 20.8 |
| 31/05/2025 | (6.4) | (7.7) | 8.0 |
| 31/05/2026 | 27.1 | 28.2 | 30.7 |
Upcoming AGM and RGM
IEM has faced pressure from US activist hedge fund Saba Capital, which held a large stake by the end of 2025. The board was concerned about the impact of this on the company’s stability and mandate due to the differing interests of its underlying shareholders.
After discussions with shareholders, including Saba, the board launched a continuation tender offer in 2026. Saba did not support this or the board’s request that it tender most of its shares. To avoid a costly dispute, the board then launched an “exit tender offer”, which over 99% of voting shareholders supported. This completed on 19 May, with almost 80% of shares tendered, suggesting most non-Saba shareholders did not want to remain invested if Saba took control.
Saba now has a realistic chance of controlling the much smaller fund that remains after the tender. Following share buybacks, as of 21 May, Saba owns 31.36% of shares and has called for the removal of the entire board, proposing its own nominees. The board must now hold a Requisitioned General Meeting (RGM) on 17 June, the same day as the Annual General Meeting (AGM).
IEM’s chairman, Glen Suarez, wrote to shareholders on 22 May, acknowledging that “Saba now has effective control over the company’s strategic direction.” He recommended voting for all AGM resolutions, including re-electing the current board, and against all Saba resolutions at the RGM. Glen also noted the board does not know Saba’s future plans, warning that a Saba-nominated board would bring uncertainty and could be influenced by Saba as the largest shareholder.
Asset allocation
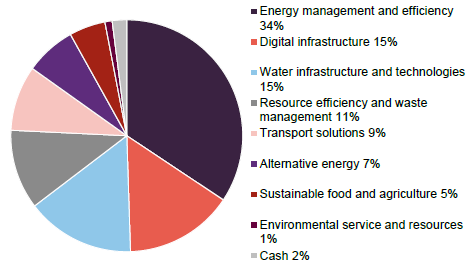
At the end of April 2026, IEM held 54 investments, just below the 55 reported at the time of our last note (using data as at March 2025). North America is still IEM’s largest regional exposure, though it has fallen from 57% to 46% over the year, while European exposure has grown from 29% to 34%. Sector weightings in energy management and efficiency, and digital infrastructure have increased since the last update.
Figure 1: IEM portfolio by geography as at 30 April 20261
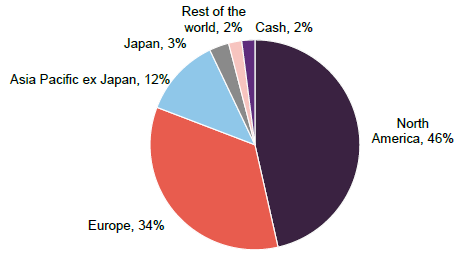
Figure 1: IEM portfolio by geography as at 30 April 20261
Top 10 holdings
Figure 3: IEM 10 largest holdings as at 30 April 2026
| Stock | Subsector | Country | As at 30/04/26 (%) | As at 31/03/25 (%) | Change(%) |
|---|---|---|---|---|---|
| Siemens Energy | Smart & efficient grids | Germany | 4.4 | n/a | n/a |
| Waste Connections | General waste management | United States | 3.5 | 3.3 | 0.2 |
| Air Liquide | Industrial energy efficiency | France | 3.5 | n/a | n/a |
| SSE | Renewable energy development | United Kingdom | 3.0 | n/a | n/a |
| Contemporary Amperex Tech | Advanced road vehicles & devices | China | 3.0 | n/a | n/a |
| KLA | Water efficiency | United States | 2.8 | n/a | n/a |
| Novonesis (Novozymes) | Sustainable agriculture | Denmark | 2.8 | n/a | n/a |
| Veolia Environnement | Water utilities | France | 2.8 | n/a | n/a |
| Littelfuse | Industrial energy efficiency | United States | 2.3 | n/a | n/a |
| Schneider Electric | Smart & efficient grids | France | 2.2 | n/a | n/a |
| Total of top 10 | 30.3 |
IEM has significantly changed its top ten holdings over the past year. As shown in Figure 3, only Waste Connections remains from the previous list as of 31 March 2025, with the other nine holdings replaced. The managers made these changes to try and improve recent disappointing performance.
Performance
IEM has underperformed the MSCI ACWI, as shown in Figures 4 and 5. Its strong performance up to May 2021 is no longer included in the five-year comparison. Although there have been some periods of steady performance, overall relative returns have disappointed. This is mainly because global equities, especially technology companies not covered by IEM, have performed strongly. IEM’s investment style has also been out of favour. From late 2021, rising inflation and interest rates were a particular challenge for growth-focused stocks, and inflation concerns have recently resurfaced.
Figure 4: IEM performance relative to MSCI ACWI over five years ended 31 May 2026
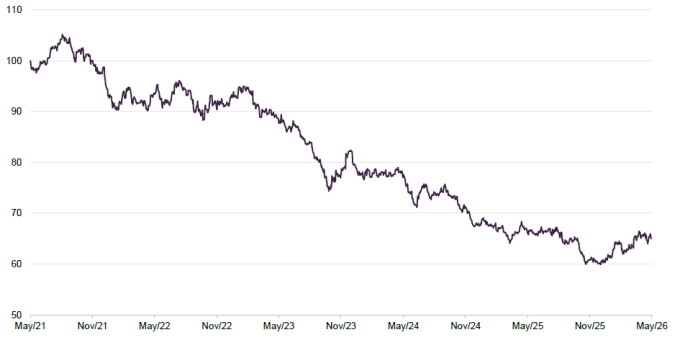
Figure 5: IEM cumulative returns for periods ending 31 May 2026
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| IEM price | 2.4 | 16.9 | 27.1 | 15.9 | 5.2 |
| IEM NAV | 9.2 | 19.3 | 28.2 | 23.3 | 20.6 |
| MSCI AC World Index | 7.6 | 11.6 | 30.7 | 68.2 | 85.5 |
Previous publications
Readers interested in further information about IEM may wish to read our previous notes (details are provided in Figure 6 below). You can read the notes by clicking on them below or by visiting our website.
Figure 6: QuotedData’s previously published notes on IEM
| Title | Note type | Date published |
|---|---|---|
| Sustainable long-term growth | Initiation | 3 June 2024 |
| Delayed but not derailed | Update | 3 December 2024 |
| Significant headwinds, but still value | Update | 8 May 2025 |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Impax Environmental Markets Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have
regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information.
This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.