
A listed gateway to private AI
Shaires Holdings Ltd (SHR) is seeking to provide public market investors with exposure to some of the world’s largest private technology businesses, particularly those at the forefront of AI. A large proportion of technology value creation now occurs before companies reach public markets, leaving traditional equity investors excluded from many of the sector’s strongest growth opportunities.
SHR’s strategy is to build a concentrated portfolio of high-conviction private investments, focusing primarily on late-stage AI businesses. A distinctive feature of the model is its ability to acquire private company shares through “in-kind” contributions from existing shareholders including founders, employees and early investors. They can exchange their private holdings for newly issued listed SHR shares, providing them liquidity and diversification without requiring an outright cash sale.
The company has assembled a board and executive team with extensive experience of investing in private technology companies and established relationships across the AI ecosystem. SHR has begun raising capital to construct its initial portfolio, and today has launched a retail offer.
SHR’s success will depend not only on the performance of the underlying private companies, but also on management’s ability to source attractive transactions and establish SHR as a trusted liquidity partner for private market shareholders. The ambition is that the company offers investors rare access to some of the world’s leading private AI businesses and expands through further share issuance, although execution risk remains significant.
Capital appreciation from private AI companies
SHR seeks to generate superior long-term capital appreciation by acquiring and holding equity stakes – principally through in-kind share contributions and secondary market transactions – in high-growth private companies, with a particular focus on AI.
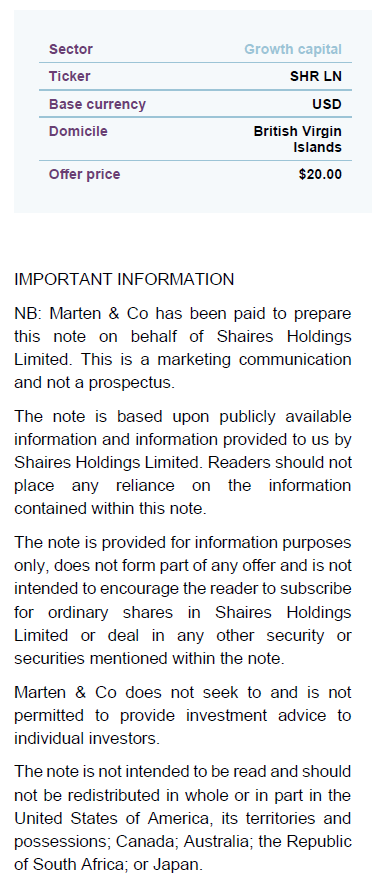
Fund profile
More information can be found on the company website shaires-holdings.com
Shaires Holdings Ltd (SHR) is a recently formed, internally managed listed investment company focused on providing public market investors with exposure to private mid- and late-stage technology businesses, with a particular emphasis on artificial intelligence (AI). Domiciled in the British Virgin Islands and listed on AIM, the company seeks to bridge what management views as a growing disconnect between where technology value creation occurs (predominantly in private markets) and the limited access traditionally available to public investors.
Unlike a traditional venture capital or private equity fund, SHR has a permanent capital structure with no fixed investment horizon or wind-up date. Management believes that this allows the company to hold investments throughout their evolution rather than being forced to realise assets within a predetermined fund life. The company also differentiates itself by operating without external investment management, charging neither management nor performance fees.
Investment strategy
Concentrated portfolio of private technology companies
The strategy centres on building a concentrated portfolio of high-conviction positions in private technology companies. Management argues that the universe of businesses capable of generating outsized long-term returns is relatively small and therefore believes concentration, rather than broad diversification, offers superior risk-adjusted returns.
The company intends to focus primarily on late-stage and pre-IPO businesses operating across technology and AI, although its investment policy also permits investments across adjacent innovation-driven sectors including space, fintech and clean energy.
Its strategy comprises two complementary investment baskets. Over time, the majority of the portfolio is intended to be allocated to frontier AI model developers and foundation model companies, with the remaining portfolio invested in “AI beneficiaries”, namely businesses commercialising AI through applications such as infrastructure, defence, fintech, enterprise software and other AI-enabled industries.
Innovative liquidity model
A defining feature of the strategy is SHR’s “in-kind contribution” model.
Management believes that the AI cycle has reached the point where the pioneering stage is largely over and mass adoption is still to come. What is scarce, it says, is a route to liquidity for the people who built these companies. Employees and early investors cannot easily sell stock and are faced with a fragmented secondary market or several more years of waiting for a liquidity event. SHR’s model aims to provide that liquidity without the timetable.
Founders, employees, venture investors and early shareholders can contribute private shares into SHR in exchange for newly issued listed SHR shares. This provides contributors with immediate liquidity, public market exposure and portfolio diversification without requiring an outright disposal of their private holdings.
Share transfer restrictions are common in private markets, and so SHR intends to focus on approved, consented and compliant transactions and is not seeking to circumvent transfer restrictions imposed by portfolio companies. Becoming a trusted and credible counterparty is critical to the long-term success of the model.
In-kind share contributions creates a differentiated sourcing advantage
Management believes that this structure creates a differentiated sourcing advantage versus conventional investment companies by opening access to shareholders who may otherwise be unwilling or unable to sell private holdings through secondary transactions. It also emphasises the accessibility of the listed structure. Unlike traditional venture capital or private equity vehicles, SHR is designed to offer investors daily liquidity through AIM trading, with no lock-up periods, accreditation requirements or carried interest, allowing retail investors to gain exposure through a conventional brokerage account.
SHR’s investment proposition is unique and, therefore, cannot be compared to any other UK listed investment company.
Recent history
Created through the strategic transformation of Jade Road Investments, with new investing policy and articles of association
SHR was created through the strategic acquisition and complete transformation of Jade Road Investments Limited, an AIM-listed investment company, where the management reports that almost every fundamental aspect of the company has changed other than it being an investment company, including clearing all of its debts and obligations. As part of the repositioning, shareholders approved a new investing policy, a share consolidation, a change of name, new articles of association and expanded share issuance authorities to facilitate the implementation of the new strategy.
The strategic repositioning included:
- renaming to Shaires Holdings Limited;
- adopting an entirely new investment policy;
- a share consolidation;
- appointing a new technology-focused leadership team (details on page 12); and
- commencing a substantial capital raising programme to fund its inaugural portfolio.
Equity raises
Raised $28.5m in July
A first institutional fundraising closed on 30 July 2026, raising $28.5m. A total of 1,424,000 new ordinary shares were issued at a price of $20.00 per share. Combined with existing cash resources of around $8m, the company currently has approximately $36.5m available for deployment (ahead of this latest fundraise, there are 2,949,989 shares in issue).
New institutional and retail offer launched at $20 per share
A second institutional fundraising tranche is in progress and a retail offer, managed by the Winterflood Retail Access Platform (WRAP) launched today.
Under the WRAP retail offer, new ordinary shares will be made available at a price of $20.00 per share, representing a discount of approximately 18% to the mid-market closing price of $24.50 on 12 August (being the latest practicable date prior to this announcement) and a premium to the NAV.
A number of retail platforms, including Hargreaves Lansdown and AJ Bell, are able to access the WRAP retail offer, which is expected to close at 4.30pm on 18 August 2026. Eligible retail investors should note that financial intermediaries may have earlier closing times.
Minimum subscription of $100
There is a minimum subscription of $100 per investor under the retail offer. The terms and conditions on which investors subscribe will be provided by the relevant financial intermediaries including relevant commission or fee charges.
A capital access window will be initiated from today, which involves a pause to the trading of a company’s shares. It will remain in place until completion of the retail offer. The result of the retail offer is expected to be announced by the company on or around 19 August 2026.
NOIA Capital acts as the sponsor to capital raises and receives 5.5% of newly issued stock in each fund raise. NOIA does not receive an annual management fee or performance allocation.
Market backdrop
Technology companies remaining private for longer
Over the past decade, many of the world’s largest technology companies have remained private significantly longer than previous generations, allowing substantial value creation to occur before public listings. Companies such as SpaceX, OpenAI, Anthropic and Databricks achieved valuations measured in tens or hundreds of billions of dollars while remaining inaccessible to most public market investors.
Equity investors miss out on substantial value creation
AI only appears to be accelerating this trend. Rather than listing early to fund growth, leading AI businesses increasingly benefit from access to deep pools of private capital supplied by venture capital firms, sovereign wealth funds, family offices and strategic investors. Consequently, public equity investors have often gained exposure only after much of the value appreciation has already occurred.
SHR’s business model aims to give institutional and retail investors access to frontier AI innovation and enable them to participate in their growth. Simultaneously, SHR seeks to offer liquidity solutions to founders, employees and early investors in the private AI companies whose capital remains locked in.
SHR intends to become the partner of choice for many of the world’s leading AI companies and their stakeholders, building on management’s existing founder relationships, by providing flexible capital and innovative liquidity solutions that support their continued growth while they remain private.
SHR also believes its model can strengthen London’s public markets by providing a listed gateway to frontier AI investments at a time when relatively few high-growth technology companies are choosing to list in the UK.
Investment process
SHR intends to invest primarily in private technology companies through four principal acquisition channels:
- in-kind contributions from existing shareholders;
- secondary market purchases of private company shares;
- co-investments alongside strategic investors; and
- primary subscriptions into new financing rounds.
Portfolio construction
The company adopts an explicitly concentrated investment philosophy. During its initial investment period, individual investments may represent up to 75% of net asset value, reflecting the practical realities of portfolio construction through large in-kind contributions and early-stage deployment.
Following the initial investment period, no new investment may exceed 50% of NAV at the time of commitment, although subsequent appreciation may result in positions exceeding this threshold without breaching policy.
After the investment period expires, the company intends to maintain at least five investments, although there is no upper limit on portfolio size.
AIM rules do not impose any mandatory diversification threshold on investing companies. Potential shareholders are advised to exercise caution given SHR’s highly concentrated profile in terms of size, holding and nature of the company’s future investments.
Investment universe
The investment policy permits investment across:
- private equity securities;
- listed equities;
- convertible securities;
- debt instruments with equity-like characteristics;
- SPVs and co-investment vehicles;
- ETFs; and
- cash and money market instruments.
Although technically sector-agnostic, management indicates that AI and advanced technology will remain the principal investment focus.
Holding period
Exits expected through IPOs, strategic acquisitions and secondary market disposals
Investments are expected to be held over the medium-to-long term, typically between three and 10 years, although the company is under no obligation to realise investments within a fixed timeframe. Exits are expected through IPOs, strategic acquisitions and secondary market disposals.
Governance approach
The board has adopted the Quoted Companies Alliance (QCA) Corporate Governance Code, the governance framework commonly followed by AIM-listed companies.
SHR expects to operate as a predominantly passive investor, but reserves the right to seek observer rights or board representation where appropriate. The company intends to undertake rigorous due diligence prior to investment, including legal, commercial and financial diligence, management meetings and, where appropriate, independent third-party valuations. New investments may also incorporate negotiated investor protections, including governance rights where justified by the size or nature of the investment.
Investment restrictions
The investment policy contains relatively few formal restrictions. Key limitations include:
- no investment in other AIM-listed investment companies;
- no activities that would classify the company as a collective investment scheme; and
- no FCA-regulated activities unless authorised.
Derivative usage is tightly constrained and limited primarily to FX hedging, interest-rate hedging and temporary acquisition bridging. The company explicitly prohibits speculative derivative strategies, synthetic leveraged exposure and net short positions.
Leverage
Borrowings may be employed where appropriate, with aggregate net borrowings generally limited to 50% of NAV at drawdown, although temporary breaches are permitted during acquisition completion provided leverage is reduced within 12 months.
Capital returns
Focus on capital growth, although realised gains may be returned through dividends or buybacks
The company is primarily focused on capital growth and does not currently intend to pay a dividend in the immediate future. As investments mature through IPOs or strategic exits, management expects realised gains to be reinvested or returned primarily through dividends or share buybacks.
Initial portfolio
Initial portfolio valued at $86.7m
The company has identified an initial investment portfolio valued at $86.7m, detailed in Figure 1. It has entered into binding commitments to purchase up to $40m of interests in single asset special purpose vehicles (SPVs) managed by Rizvi Traverse (a company connected to Suhail Rizvi, executive chairman of SHR and a related party to the company) that provide exposure to some of the world’s most exciting private technology companies including: Anthropic, the frontier AI company behind the Claude family of models; Stripe, the financial technology company building AI-driven financial infrastructure; and Figure AI, the AI robotics company working on general purpose humanoids.
In addition, SHR has entered into a subscription agreement with third-party SPVs providing exposure to Bytedance and Moonshot AI, the leading Chinese AI lab behind the Kimi series of open-source models.
Figure 1: Initial portfolio
| Company | Industry | Basis of investment | Value ($m) | % of portfolio |
|---|---|---|---|---|
| Anthropic | Frontier | Binding option agreement | Up to 16.2 | 18.7% |
| Moonshot AI | Frontier | Cash | 5.0 | 5.8% |
| ByteDance | Social media | Cash | 15.0 | 17.3% |
| SandboxAQ | Quantum computing | In-kind contribution | 14.8 | 17.1% |
| Figure AI | Physical AI | Binding option agreement | Up to 14.5 | 16.7% |
| Colossal | Biosciences | In-kind contribution | 12.0 | 13.8% |
| Stripe | Fintech | Binding option agreement | Up to 9.2 | 10.6% |
| Total | Up to 86.7 |
As part of its in-kind, share-for-share contribution programme, the company has entered into contribution agreements with certain counterparties that are contributing $14.8m of interests in SPVs providing exposure to SandboxAQ, a leading quantum computing and AI company, as well as $12m of shares in Colossal Biosciences, an advanced genetics and biosciences company working on “de-extinction”.
The investments in SandboxAQ and Colossal Biosciences as part of the in-kind programme will be funded by the issuance of 1,341,821 new ordinary shares
Ambition to grow portfolio to more than $500m
SHR’s management says that the company’s ambition is to build a portfolio worth more than $500m. It adds that it is in advanced discussions regarding further investments into leading private technology and AI names and will provide regular updates as and when definitive agreements are signed. These opportunities are at varying stages of negotiation, it says, and there is no certainty that any will be completed. In addition, the company maintains an active pipeline of additional cash and in-kind investments at various stages of advancement.
The portfolio will intentionally be concentrated to reflect the management team’s belief that a relatively small number of companies are capturing the majority of value creation in AI and that a concentrated portfolio may provide better exposure than a traditional diversified approach. Over time, the portfolio is expected to expand to around 40-50 holdings while retaining a focus on high-conviction positions.
Management’s broader investment thesis is that the AI ecosystem is increasingly bifurcating between frontier model developers and the businesses monetising those capabilities. The company believes both parts of the value chain will benefit from the long-term AI adoption cycle, and therefore intends to allocate capital across each segment rather than focusing exclusively on foundation model developers.
The portfolio will be focused on AI builders (such as Anthropic, OpenAI and Moonshot AI) and AI beneficiaries (such as ByteDance and Stripe). It will also focus on companies over $1bn in value – in an effort to limit the risk of its portfolio companies failing.
Valuation
Ongoing portfolio valuations will be set using a framework established by an investment and valuations committee, and overseen by the board of directors (see page 12 for profiles), that incorporates multiple inputs including recent funding rounds, company-sponsored tender offers, secondary market transactions, and independent analysis.
Potential growth
Management has stated that NAV growth is the primary measure of long-term performance. An obvious potential means for SHR’s NAV growth is from the growth in value of the underlying portfolio companies. A second is the NAV accretion generated through issuing in-kind contributions shares above NAV. Management believes that the combination of portfolio growth and accretive issuance can create a self-reinforcing cycle of NAV growth, scale and liquidity.
A premium share price rating is an important element for the success of the in-kind contribution model, but management states that the primary driver of long-term value creation remains the performance of the underlying portfolio. Nevertheless, there is a risk with this investment strategy that a disconnect between SHR’s share price and its NAV becomes apparent.
Capital structure and life
SHR is incorporated in the British Virgin Islands (and is, therefore, not subject to the UK City Code on Takeovers and Mergers) and listed on AIM. Unlike traditional private equity funds, the company has a permanent capital structure with no finite investment life or mandatory return of capital.
Operating expenses limited to 1% of NAV. Executive team and board incentivised through employee stock ownership plan.
The company is internally managed, and so does not bear management fees and performance fees. The company intends to limit total operating expenses to 1% of NAV, covering audit, custody, registrar, listing and regulatory costs. However, we understand that the team is incentivised by an employee stock ownership plan (ESOP) – a multi-year performance-based option aligning with long-term NAV/share compounding (see Compensation section below).
In addition, as early-stage investors, the directors benefit from shares that were issued when the NAV was lower than the $20 issue price. As such, they benefit from the NAV enhancement associated with issuing shares at a premium to NAV.
The company does not currently expect to pay regular dividends during the portfolio build-out phase. In the longer term, management expects realised gains from portfolio exits to be reinvested into the portfolio or distributed via dividends or share buybacks where appropriate.
The company intends to provide regular portfolio updates, announcements regarding in-kind contributions, and quarterly NAV reporting following completion of the initial investment period. Shareholders should expect quarterly NAV and portfolio updates (generally within 30 days of quarter end), annual audited financial statements in June, and interim results and an Annual General Meeting in August.
Equity issuances
A central feature of the structure is the flexibility to issue new shares both for cash and as consideration for in-kind contributions.
The company has powers to issue shares in order to implement its new investing policy, and can issue new equity on a non-pre-emptive basis. The ambition is to grow the company significantly over time. Whilst the board has indicated that it will give consideration to the conduct of retail offers in appropriate circumstances, there is no obligation on the company to do so, and any such offers would be subject to conditions, including minimum subscription thresholds, timing and regulatory requirements, which may not always be capable of fulfilment.
Board and executive management
The company’s board and executive team have a strong track record in technology venture capital investing. Board members have been associated with some of the most successful technology investments of the last two decades, and maintain deep relationships across the sector.
Suhail Rizvi – executive chairman
Suhail Rizvi is co-founder and chief investment officer of Rizvi Traverse, a private investment firm established in 2004. Over more than two decades the firm has invested in excess of $3.5bn across technology, media and entertainment businesses including SpaceX, Facebook, Twitter, Square, Snapchat, Sandbox AQ, Figure AI and Instacart.
Suhail brings extensive experience investing in private technology companies through multiple market cycles, and is expected to lead the firm’s investment strategy and long-term portfolio construction.
Vivek Seth – chief executive officer
Vivek Seth has more than 35 years of investment banking and capital markets experience, having advised on transactions exceeding $110bn. He founded Sunsar Capital Management and previously served as vice chairman of investment banking at Raymond James, where he established the firm’s Real Estate Investment Banking practice.
Management expects his experience in financing private companies and public market transactions to support portfolio company development, valuation oversight and capital markets execution.
Shervin Pishevar – vice chairman and non-executive director
Shervin Pishevar is a venture capitalist and serial technology entrepreneur with more than 27 years of experience investing in emerging technology businesses.
He previously founded Sherpa Capital, investing in companies including Uber, Airbnb, SpaceX and IONQ, and prior to that led Uber’s Series B investment while at Menlo Ventures. He has invested in more than 200 technology companies and has appeared on the Forbes Midas List multiple times.
His expertise is expected to strengthen proprietary deal sourcing and relationships across the global AI ecosystem.
Yunus Olçer
Yunus has investment management experience spanning Goldman Sachs, BlueMountain Capital and NOIA Capital, specialising in global equities, credit and special situations investing.
Christian Reyntjens
The founder of family office A Black Square and former Partner at York Capital Management, Christian has significant experience in European hedge fund investing, special situations and private equity.
Nicolas Vassaux
Nicolas is head of direct deals at NOIA Capital and has experience spanning venture capital, family office investing, operational portfolio company management and strategy consulting.
John Croft
Formerly executive chairman of Jade Road Investments, John transitioned to a non-executive role following the strategic repositioning. He has extensive experience across technology, banking and listed company governance.
Committees
Two standing committees have been established: an investment and valuation committee, chaired by Christian Reyntjens, responsible for reviewing strategy, portfolio valuations and major investment transactions; and an audit committee, chaired by Yunus Olçer with Nicolas Vassaux as a member, overseeing financial reporting, financing structures, risk management and internal controls. The board states that it intends to meet at least six times annually.
Compensation
Management and the board will be compensated and incentivised through a structure based on long-term shareholder value creation. As already mentioned, no management or performance fee is charged, and a substantial portion of compensation is equity-based. Equity awards vest over time and are linked to performance, with the focus on NAV growth.
Vesting is tied to value-creation milestones, with the executive team holding a 1% option plan and the board 7%.
IMPORTANT INFORMATION
This marketing communication has been prepared for Shaires Holdings Limited by Marten & Co, which is authorised and regulated by the Financial Conduct Authority (FCA). It constitutes non-independent research as defined under the UK MiFID II regime and the onshored Commission Delegated Regulation (EU) 2017/565.
This communication is intended for use by investment professionals as defined in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005.
Marten & Co is not authorised to provide advice to retail clients. Accordingly, if you are not a professional investor, or are otherwise restricted from receiving this information, you should disregard it.
Charts and data are sourced from Bloomberg unless otherwise stated. Please read the important information at the back of this document. The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it.
The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.