
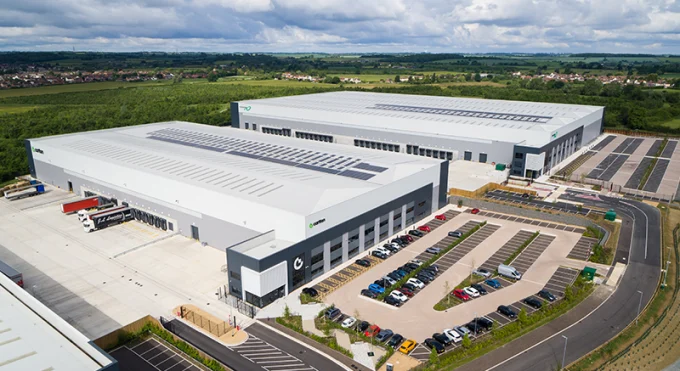
Despite a busy year where M&A added £1.2bn of assets to its portfolio, LondonMetric Property (LMP) saw a only modest increase in its EPRA NAV over the year ended 31 March 2026 (from 199.2p to 200.6p). Earnings per share improved by 2.4% to 13.5p and the full-year dividend is being increased by 3.8% to to 12.45p (covered 1.08x). The company is guiding towards a 3.3% increase in its quarterly dividend for the new financial year.
The total return on the property portfolio was 7.1% (MSCI UK All Property returned 5.4%).
The company is following a triple net “NNN” strategy, which it characterises as:
- No income leakage from repairs, maintenance, operating costs, insurance or taxes;
- No vacancy risk, instead long WAULTs secured against strong occupiers; and
- No deployment of capital into direct developments that promise future returns while quietly absorbing years of opportunity cost from uncertainty over planning, letting and/or project delivery. Describing this as gambling not investing.
The portfolio offers rental income of £432m, a WALT of 17 years, 98% occupancy, gross-to-net income ratio of 99%, and 69% of income subject to contractual rental uplifts. The company says that there is strong reversionary potential across its logistics assets.
The statement says that the portfolio is concentrated in “the winning sectors of logistics, convenience retail, entertainment and hospitality”. 64% of the portfolio is in London, the South East and the Midlands.
On the outlook, LMP says ” The global economic outlook remains highly uncertain, with elevated geopolitical risk continuing to influence markets. The escalation of conflict in the Middle East has renewed volatility in energy markets and reintroduced inflationary pressures, pushing bond yields and swap rates materially higher once again.
“In the UK, the outlook remains uncertain. Weak economic growth, political uncertainty, a softening labour market and declining consumer confidence all point to interest rates remaining higher for longer. That said, we continue to believe the consumer is in reasonably good shape: employment remains high, wage growth continues to outpace inflation and household balance sheets are relatively robust.
“This latest macro uncertainty is prolonging the sharp reduction in liquidity already seen across the property investment market. The impact has been most pronounced for larger lot sizes above £20m, where the buyer universe has narrowed significantly, with limited engagement from long only UK institutions and US private equity investors.
“New acquisition opportunities arise daily from pension fund reallocations, balance sheet management and strategic repositioning. We dismiss most of these at first sight as they fail to meet our strict investment criteria. After all, whilst many people are rewarded for activity, our approach can deliver attractive returns generated through inactivity.”
QuotedData’s Richard Williams said: “LMP’s quest, bordering on obsession, to grow income should be a joy to behold for shareholders. The M&A champion, which is currently in an offer period for Picton Property, grew income by 16.6% over the year, helped by its acquisition of Urban Logistics REIT and a 4.2% uplift on the wider portfolio. It again lowered its cost ratio, to just 7.7%, and is now a highly efficient REIT delivering another year of dividend growth for shareholders – its 11th consecutive annual rise.”
