
Cash pile grows as valuations climb
Strong performance from Global Opportunities Trust’s equity portfolio drove solid NAV growth in 2025. Shareholders also benefited as the trust’s discount to NAV narrowed, though it remains wide.
Noting higher valuations in the portfolio and broader market, the manager took profits and increased cash, leaving the trust ready to act if markets fall.
The trust is no longer self-managed, which should allow greater flexibility with the use of both gearing and derivatives. Currently, the manager sees opportunities in mid-cap companies with unique valuation drivers and low sensitivity to the economy.
Attractive, real, long-term total returns
GOT aims to provide shareholders with an attractive real long-term total return by investing in globally in undervalued asset classes, without reference to the composition of any stock market index.

At a glance
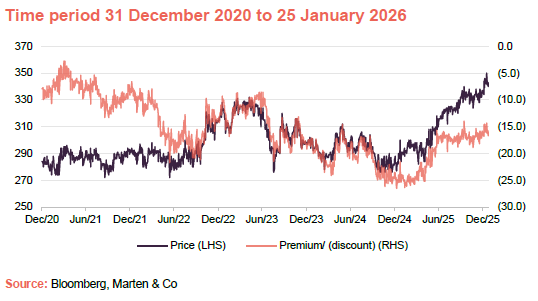
Share price and discount
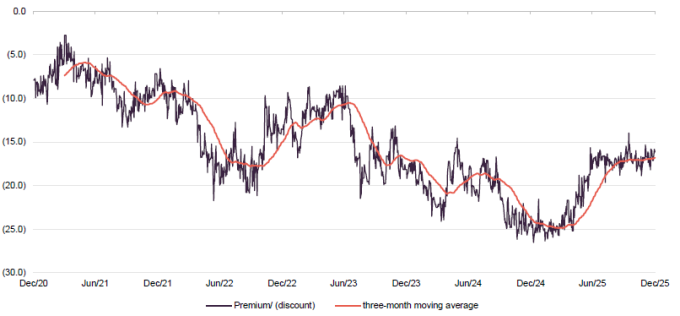
Over the 12 months ended 31 December 2025, GOT’s share price discount to its net asset value (NAV) moved within a range of 26.5% to 14.0% and averaged 20.1%.
As at 26 January 2026, GOT’s shares were trading on a discount of 16.7%.
We have been pleased to see the marked narrowing of GOT’s discount over the second half of 2025. However, there is further to go.
Performance over five years
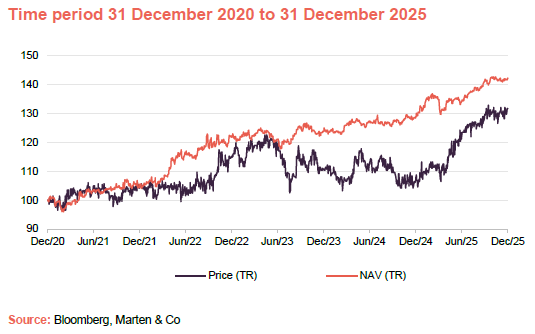
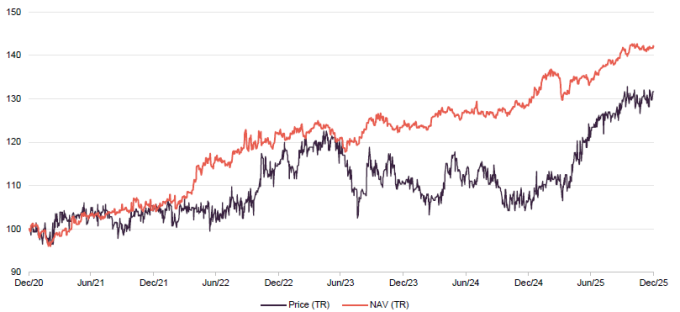
GOT’s NAV continues to make steady progress and, pleasingly, the share price has been starting to catch up since about April/May last year.
Looking at GOT’s returns in up and down months over the period since the investment policy was formally changed in December 2021, in months when the MSCI ACWI index was falling, GOT’s NAV rose by 1.0% on average, versus an average fall in the index of 2.6%. In months where the index was rising, GOT’s average return was 0.5%, which compares to 2.9% for the index.
| Year ended | Share price total return (%) | NAV total return (%) | MSCI ACWI total return (%) | World Govt. Bond Index1 total return (%) |
|---|---|---|---|---|
| 31/12/2021 | 4.6 | 5.1 | 19.6 | 11.9 |
| 31/12/2022 | 9.8 | 15.9 | (8.7) | (3.7) |
| 31/12/2023 | (3.6) | 1.6 | 15.8 | 3.0 |
| 31/12/2024 | (2.4) | 4.1 | 19.8 | 6.9 |
| 31/12/2025 | 21.9 | 10.2 | 13.9 | 8.7 |
Source: Bloomberg, Marten & Co, Note 1) Bloomberg Global Aggregate Treasuries Index
Fund profile – no longer self-managed
More information is available on the trust’s website globalopportunitiestrust.com
GOT aims to deliver strong long-term returns by investing globally in undervalued assets, without following any stock market index. The trust is intended for investors seeking long-term absolute returns, not those focused on short-term market movements. While value opportunities drive the portfolio, GOT is not limited to traditional value investing. Goodhart invests flexibly across all industries and company stages, including growth, quality, value, discounted assets, and special situations. This flexible approach is detailed in our initiation note on page 6.
Until recently, GOT was self-managed. From 2 January 2026, Juniper Partners Limited has acted as GOT’s AIFM, delegating portfolio management to Goodhart Partners LLP. Goodhart’s fee is 0.50% of NAV per year plus £30,000 for marketing, and ongoing company costs are estimated at 1.11% per year.
More flexible structure
Moving away from self-management allows GOT more flexibility with borrowing and using derivatives for efficient portfolio management.
Goodhart was founded in 2009. With Dr Sandy Nairn, previously GOT’s executive director, having stepped down, the board is now fully non-executive and independent from the manager. Goodhart is named after “Goodhart’s law”: when a measure becomes a target, it stops being a good measure. The team rejects strategies focused solely on beating benchmarks, criticising much of the asset management industry for prioritising asset gathering over effective money management. They also note that industry consolidation often leads to smaller, attractive opportunities being overlooked.
Manager’s view
Within GOT’s portfolio, defensive stocks chosen for their resilience performed well in 2025. GOT held several large companies with steady revenue growth and strong margins, which were expected to deliver high single-digit annual returns. However, many of these stocks rose by over 50% in just six months. Following its value-focused approach, the manager decided to take profits and sold positions in stocks like Imperial Brands and Tesco. Some of these have continued to rise, but GOT’s manager is comfortable, stressing that protecting against losses is more important than chasing higher returns.
The manager is now looking for “resilient +” midcap stocks with business models less tied to the economic cycle. Examples in the portfolio include Rovi, Viscofan, and Bakkafrost, though these positions are smaller due to the added risk of investing in smaller companies. The manager expects these stocks to hold up better in falling markets and possibly rise for company-specific reasons.
Stocks like Breedon, seen as too exposed to the UK economy, and Kalmar have been sold. While positions in defence and energy have been reduced, the manager has kept some exposure, believing these sectors could benefit from worsening global tensions. GOT holds large prime defence contractors, not the more speculative specialist firms, as their share prices have already surged. The manager expects rising defence spending to support prime contractors for years, with current share prices not yet reflecting future profit growth.
GOT’s Japanese exposure, held through AVI Japanese Special Situations, has been trimmed after strong performance, which the manager feels has limited further upside. However, there could be gains if Japanese investors return to their domestic market.
The manager is preparing for a scenario where GOT’s portfolio could rise in flat markets but only experience about 20% of the losses in a downturn. Concerned about the risk of falling markets, the manager has increased cash and liquid assets. There is a focus on the possibility of a true bear market, not just a short-term drop, which hasn’t been seen since the GFC and is outside the experience of many fund managers. In such times, it is not enough to avoid the most popular large-cap stocks, as market leadership can shift. GOT’s liquidity provides flexibility to act on new opportunities.
If markets fall sharply, the manager expects some rallies to occur before a true recovery comes through. GOT’s team includes both value and growth investors, giving it a wide range of opportunities. A setback could create chances to buy higher-growth midcap companies, especially those able to use AI to challenge established players.
Asset allocation
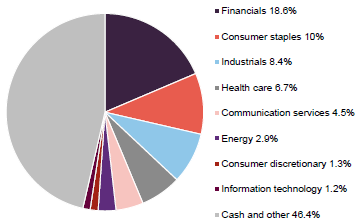
Figure 1: GOT portfolio split by sector as at 31 December 2025
Source: Global Opportunities Trust
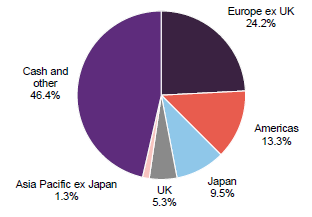
Figure 2: GOT portfolio split by region as at 31 December 2025
Source: Global Opportunities Trust
Since the end of May 2025, GOT has reduced its holdings in financials from 22.6% to 18.6% and in industrials from 15.6% to 8.4%. At the same time, its allocation to cash and other assets has increased from 35.4% to 46.4%.
Geographically, the main shift has been a decrease in UK exposure, with more funds moved to cash and other assets.
Top 10 holdings
Since our last update using data from May 2025, Lloyds Banking Group, Alibaba, Jet2, Total Energies, and Qinetiq have left the top 10 holdings. They have been replaced by Carlsberg, GQG Partners, Terveystalo, Philips, and Nestle. Lloyds performed strongly, with its share price rising over 80% last year, leading the manager to sell the entire holding. The Jet2 position was reduced, but the manager still sees value in the company due to its strong cash position. TotalEnergies and Qinetiq were also trimmed as part of a move to reduce exposure to energy and defence. The manager also took profits from the Alibaba stake.
In total, there were 25 equity positions in the portfolio at the end of December 2025.
Figure 3: GOT 10 largest holdings as at 31 December 2025
| Country | Sector | % of net assets 31/12/25 | % of net assets 31/05/25 | Change(%) | |
|---|---|---|---|---|---|
| AVI Japanese Special Situations Fund | Japan | n/a | 9.5 | 12.7 | (3.2) |
| Volunteer Park Capital Fund | Luxembourg | n/a | 7.1 | 6.9 | 0.2 |
| Unilever | United Kingdom | Consumer staples | 2.8 | 3.3 | (0.5) |
| Orange | France | Communication services | 2.8 | 2.6 | 0.2 |
| Carlsberg | Denmark | Consumer staples | 2.1 | – | 2.1 |
| GQG Partners | United States | Financials | 2.0 | – | 2.0 |
| Dassault Aviation | France | Industrials | 1.9 | 3.3 | (1.4) |
| Terveystalo | Finland | Health care | 1.8 | 1.9 | (0.1) |
| Koninklijke Philips | Netherlands | Health care | 1.8 | 0.7 | 1.1 |
| Nestle | Switzerland | Consumer staples | 1.7 | 1.3 | 0.4 |
| Total | 33.5 |
Source: Global Opportunities Trusts
Carlsberg
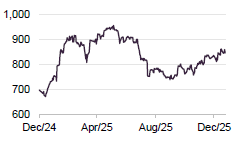
Figure 4: Carlsberg (DKK)
Source: Bloomberg
The Danish brewer Carlsberg (carlsberggroup.com) has over 180 brands and sells in more than 100 countries. Its medium-term aim is 4%–6% organic revenue growth and improved gross margins through strict cost control. During the first half of its 2025 financial year, premium beer revenues rose 5% and soft drinks grew 6%, boosted by the Britvic acquisition. This led to 4.7% growth in adjusted EPS for the half-year, with the company expecting further cost and revenue benefits from the Britvic deal.
GQG Partners
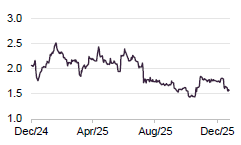
Figure 5: GQG Partners (AUD)
Source: Bloomberg
GQG Partners (gqg.com) is a US-based asset manager listed in Australia and known for managing part of Alliance Witan’s portfolio. In the first half of 2025, its funds saw net inflows of $8bn, but assets under management have since dropped from $172.4bn to $163.9bn, which has put pressure on its share price and created a more attractive entry point for GOT.
GOT is drawn to GQG’s defensive approach. Although this has led to its global equity strategy underperforming the MSCI ACWI over one, three, and five years to June, it could benefit if markets fall. GOT’s manager notes that GQG is not widely represented in the US mutual fund market, but strong performance in a downturn could attract significant new investment. With a small free float, any positive news could have an outsized impact on the share price.
Koninklijke Philips
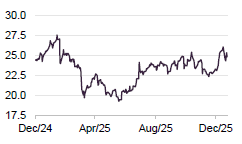
Figure 6: Koninklijke Philips (EUR)
Source: Bloomberg
Philips (philips.com) is a healthcare technology company offering products like patient monitors, ultrasound, imaging, diagnostics, MRI and CT scanners, as well as personal health items such as electric razors and toothbrushes. It spends over 9% of its 2024 revenue on research and development to keep its leading market positions.
Healthcare spending is supported by ageing populations, rising demand in emerging markets, and ongoing innovation. Philips aims to boost revenue growth from low to mid-single digits, increase margins from high single digits to low teens, and reduce debt. In the third quarter, sales grew by 3% year-on-year and EBITDA margins reached 12.3%.
Other new positions
Rovi
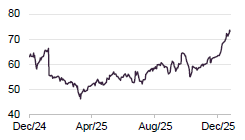
Figure 7: Rovi (EUR)
Source: Bloomberg
Laboratorios Farmaceuticos Rovi (rovi.es) is a Spanish biotech company focused on Heparin (a blood thinning medication) and related products. It develops and sells its own medicines and runs a contract manufacturing business, recently partnering with Roche to produce a new drug in Roche’s metabolic and cardiovascular range. In November 2025, Rovi forecasted operating revenue growth in the high single to low double digits for the year. The manager highlights the potential for higher returns as Rovi increases use of its expanded manufacturing capacity. Rovi made up 1.6% of the portfolio at the end of December 2025.
Viscofan
Figure 8: Viscofan (EUR)
Source: Bloomberg
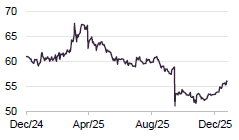
Viscofan (viscofan.com) is a Spanish company making sausage casings, with plants around the world. In its results for the third quarter of 2025, it reported 5.5% year-on-year revenue growth and a 7.3% rise in EBITDA.
In October 2025, its share price fell after allegations of environmental issues at its US plant in Danville, Illinois. Viscofan firmly denied these claims, calling them misleading. The share price drop allowed GOT to buy shares at what the manager considers an attractive price.
GOT’s manager sees Viscofan as well-positioned, noting that a key US competitor is private-equity-backed and underinvested. Viscofan made up 1.5% of the portfolio at the end of December 2025.
Performance
Figure 9: GOT share price and NAV performance over five years ended 31 December 2025
Source: Bloomberg, Marten & Co
Figure 9 shows that the NAV has continued to grow steadily, and the share price has started to catch up since April or May last year. As in our earlier note, we include a table comparing performance with some indices. However, it is important to note that the manager does not invest with benchmarks as a target.
Figure 10: GOT cumulative total returns over time periods ended 31 December 2025
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years(%) | 5 years(%) | 10 years(%) | |
|---|---|---|---|---|---|---|
| GOT share price | 1.5 | 8.7 | 21.9 | 14.6 | 31.7 | 76.2 |
| GOT NAV | 0.6 | 6.0 | 10.2 | 16.6 | 42.0 | 103.1 |
| MSCI ACWI | 3.3 | 13.3 | 13.9 | 58.0 | 72.5 | 231.9 |
| Bloomberg Global Aggregate Treasuries Index | 2.5 | 5.9 | 8.7 | 19.7 | 29.0 | 3.9 |
| UK CPI1 | 0.4 | 0.6 | 3.1 | 10.4 | 28.0 | 39.4 |
Source: Bloomberg, Marten & Co. Note 1) UK CPI is to end November 2025
GOT’s defensive approach means it usually lags behind equity indices when markets rise. However, its one-year performance is strong. Importantly, despite recent high inflation, GOT has provided positive real returns (after allowing for inflation) for shareholders over the short, medium, and long term.
We analysed GOT’s returns since its investment policy changed in December 2021. When the MSCI ACWI index fell, GOT’s NAV rose by an average of 1.0%, while the index dropped by 2.6%. In months when the index rose, GOT’s average return was 0.5% compared to the index’s 2.9%. This highlights GOT’s defensive nature.
Contributions to returns over 2025
Figure 11: Positive contributions to returns
| Stock | (%) | ||
|---|---|---|---|
| Alibaba | 1.9 | ||
| Lloyds Banking | 1.3 | ||
| Danieli | 1.2 | ||
| Orange | 1.2 | ||
| Dassault Aviation | 1.0 |
Source: Goodhart partners
Figure 12: Negative contributions to returns
| Stock | (%) | ||
|---|---|---|---|
| Azelis | (0.9) | ||
| Bakkafrost | (0.4) | ||
| Breedon Group | (0.3) | ||
| Jet2 | (0.2) | ||
| Whitbread | (0.1) |
Source: Goodhart partners
Danieli
Figure 13: Danieli (EUR)
Source: Bloomberg
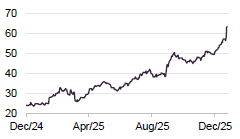
Last year Danieli (danieli.com) entered GOT’s top 10 holdings after strong share price gains driven by major contract wins, as shown in Figure 13. The family-run company supplies machinery for steel-making and steel products, benefiting from the industry’s push to cut carbon emissions and offering more efficient equipment than older plants. Its global customer base includes most leading steel producers. The manager has taken some profits, and Danieli made up 1.4% of the portfolio at the end of December 2025.
Premium/(discount)
Figure 14: GOT premium/(discount) over five years ended 31 December 2025
Source: Bloomberg, Marten & Co
Over the 12 months to 31 December 2025, GOT’s discount ranged from 26.5% to 14.0%, averaging 20.1%. On 26 January 2026, the shares traded at a 16.7% discount.
The narrowing discount in the second half of 2025 is encouraging, but there is still room for improvement. In uncertain markets, trusts like GOT, which have a good record of performing well in downturns and take a defensive approach, are likely to attract more interest.
GOT has the ability to buy back shares but is not doing so. The board wants to narrow the discount and grow the trust, but is concerned that buybacks could reduce liquidity and worsen the discount. Instead, it is focusing on raising awareness of the trust and its investment strategy.
SWOT/Bull-bear
| Strengths | Weaknesses |
|---|---|
| Free-ranging, flexible approach can adapt to all market conditions | Will not suit investors focused on short-term index movements |
| Experienced team working in supportive environment | GOT’s size limits the usefulness of share buybacks |
| Low overheads | |
| Opportunities | Threats |
| Overly wide discount ought to narrow | Wide discount presents arbitrage opportunity for an activist investor |
| Trump seems to be driving a stake through US exceptionalism – potentially broadening market returns | Possible that we will see an AI bubble which would not suit GOT’s IT underweight |
Source: Marten & Co
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | Has done a good job of protecting investors in periods of falling markets and delivered outperformance of similarly defensive peers | Will be left behind in ‘risk on’ markets |
| Dividends | Attractive dividend yield | Lack of formal dividend policy creates uncertainty |
| Outlook | More volatile markets likely suit this trust’s approach | Markets could have another leg-up at time when portfolio is heavily weighted to cash |
| Discount | Discount is far too wide, especially given makeup of the portfolio | Discount has been even wider in recent past |
Source: Marten & Co
Previous publications
Our initiation note – Designed to navigate a world in flux – was published on 25 June 2025.
| IMPORTANT INFORMATION | ||
|---|---|---|
| Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Global Opportunities Trust Plc. This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have | regard to the specific investment objectives financial situation and needs of any specific person who may receive it. The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note | until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note. This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited. |
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable, or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.
| QuotedData is a trading name of Marten & Co, which is authorised and regulated by the Financial Conduct Authority. 50 Gresham Street, London EC2V 7AY 0203 691 9430 www.QuotedData.com Registered in England & Wales number 07981621, 2nd Floor Heathmans House, 19 Heathmans Road, London SW6 4TJ |
|---|