
Global equity exposure with a little extra juice
HSBC Multi Factor Worldwide Equity UCITS ETF (HWWA) is a well-established active ETF that highlights the benefits of this asset class. Using a proven factor investing approach, explained later in this report, it has consistently delivered modest outperformance against its global equity benchmark.
Despite a brief setback during the “Liberation Day” tariff announcements in April, global equities had another strong year in 2025, with gains spread more widely than before. HWWA outperformed its benchmark over the year.
While risks remain, especially from unpredictable US policy, the outlook for global equities is positive as we head into 2026. For investors seeking global equities exposure with the potential for some outperformance, HWWA is worth considering. We examine this further in the following pages.
Global equities exposure with quantitative overlay
HWWA aims to outperform the benchmark MSCI All Country World Index. The investment manager identifies stocks from this index and ranks them based on certain factors. Shares are then quantitively selected to create a portfolio to maximise exposure to the highest-ranking stocks.
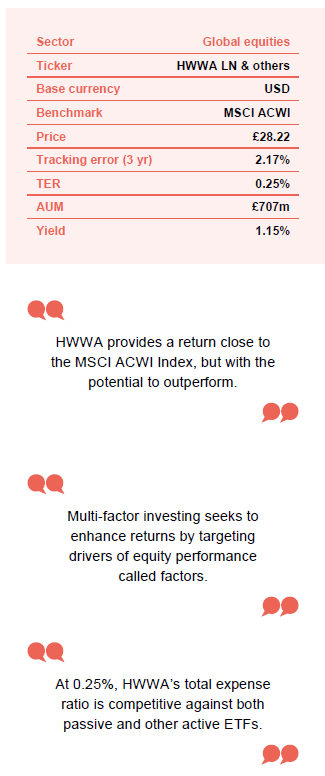
At a glance
Performance over five years
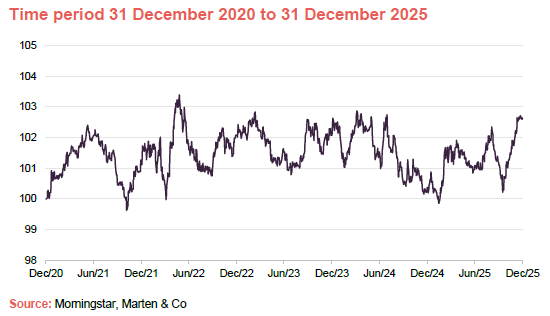
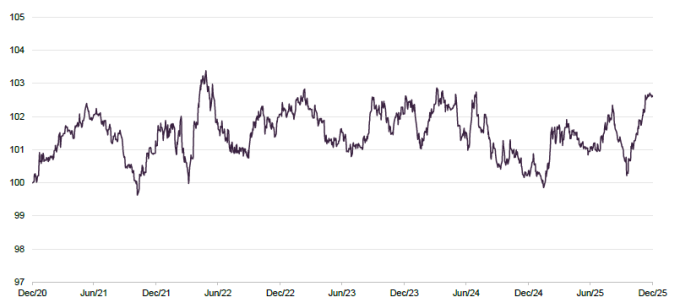
HWWA clearly tracks its benchmark, the MSCI ACWI, closely. However, it has proven its ability to provide modest outperformance over time, after fees.
NAV TR relative to MSCI ACWI
During the last five years, markets have faced numerous challenges (for example, COVID, higher inflation and interest rates, the outbreak of war in Ukraine and associated supply shocks, rising geopolitical tensions and dramatic changes in policy from the US) with the associated volatility. Against this backdrop, while HWWA’s relative performance has been volatile it has, for the overwhelming majority of the period, been able to stay ahead of the benchmark.
| 12 months ended | NAV total return (%) | Benchmark total return (%) |
|---|---|---|
| 31/12/2021 | 20.9 | 19.6 |
| 31/12/2022 | (7.8) | (8.7) |
| 31/12/2023 | 15.9 | 15.8 |
| 31/12/2024 | 17.8 | 19.8 |
| 31/12/2025 | 16.4 | 13.9 |
Source: Bloomberg, Marten & Co
HWWA: long-standing success through factor investing
Launched in 2014, with the current process instigated in 2017.
HWWA was launched by HSBC Global Asset Management in July 2014. It started with a traditional global equity strategy but shifted in October 2017, when HSBC adopted a multi-factor model. This move reflected a wider trend towards using factor investing, combined with quantitative analysis.
Multi-factor investing
Multi-factor investing is an approach that aims to enhance returns and manage risk by targeting several key drivers of equity performance, known as factors, within one strategy. Instead of traditional market-cap weighting, these models assign portfolio weights based on traits linked to long-term outperformance, such as value, quality, momentum, low volatility, and size. Since these factors perform differently at various times, combining them helps smooth out returns and reduces reliance on any one source.
This approach is rooted in decades of academic research and is popular with institutional investors seeking a middle ground between passive diversification and active risk control. Multi-factor portfolios use quantitative methods to select and weight stocks based on their exposure to these traits, while also managing risks like sector or regional concentration. The goal is to build a more resilient equity portfolio that has broad market exposure and aims to capture market inefficiencies.
Active ETFs, which tend to be low-cost and focus on liquid investments, are well matched to multi-factor investing. These strategies use systematic, rules-based models to balance exposures, making them highly data-driven and linked to an underlying index. Active ETFs like HWWA allow managers to adjust portfolio weights as factor signals change, without being rigidly tied to a fixed benchmark.
HWWA: Quantitative overlay aiming for outperformance
HWWA ranks the stocks in the MSCI ACWI and then quantitively selects stocks to make up the portfolio.
HWWA’s investment manager selects stocks from the MSCI All Country World Index, ranking them from least to most attractive using several key factors. The manager then uses a quantitative process to build a portfolio focused on the highest-ranked shares while aiming to reduce risk. This involves applying limits on sector and company weights to keep the portfolio balanced.
The portfolio is broadly diversified and avoids heavy concentration in any one area, while still targeting specific factor exposures.
HWWA aims to outperform the MSCI ACWI index, so its performance will move in line with global equities but with the goal of delivering better returns. While the portfolio is built using a systematic approach, the fund is actively managed through the manager’s research and judgement in selecting and weighting factors, rather than simply following index rules.
Like most European active ETFs, HWWA invests directly in its underlying securities instead of using derivatives, following a physical replication strategy.
Structure
HSBC Multi Factor Worldwide Equity UCITS ETF offers two share classes: distribution (ISIN: IE00BKZGB098) and accumulation (ISIN: IE0000378O66). These are listed on various exchanges and available in different currencies, as shown in Figure 1.
Figure 1: HSBC Factor Worldwide Equity UCITS ETF, available exchanges and currencies
| Distribution | Accumulation |
|---|---|
| London Stock Exchange: USD (HWWD LN)/ GBP (HWWA LN) | London Stock Exchange: USD (HWDA LN)/ GBP (HWWS LN) |
| Borsa Italiana: EUR (HWWA IM) | NYSE Euronext: (HWDA FP) |
| Deutsche Boerse AG – Xfra: (H41J GR) | |
| Deutsche Boerse AG – Xetra: (H41J GY) | |
| SIX Swiss Exchange: (HWWD SW) |
Source: HSBC Global Asset Management
We use the ticker HWWA throughout this note for consistency and as the default option for UK-based sterling investors. All performance comparisons and benchmark tracking are based on NAV, ensuring alignment with the fund’s global investment universe.
Tracking error
The three-year tracking error for HWWA to 31 January 2026 is 2.17% (tracking error measures how much a fund’s returns differ from its benchmark). The figure is typical for this type of active strategy – showing more variation than a passive ETF, but still staying fairly close to the benchmark. This is common for quantitative active ETFs, which aim to deliver returns similar to the benchmark with a small amount of outperformance from active management.
Fees
HWWA has a Total Expense Ratio (TER) of 0.25%, which covers management, custody, administration, registrar, and audit costs. This fee is included daily in the fund’s NAV but does not cover transaction costs from buying or selling investments. Given its active management, HWWA’s TER is competitive compared to passive global equity ETFs, which usually have a TER between 0.12% and 0.22%.
2025: another strong year for global equities
Markets rallied over 2025; the rally was global, rather than being dominated by the US.
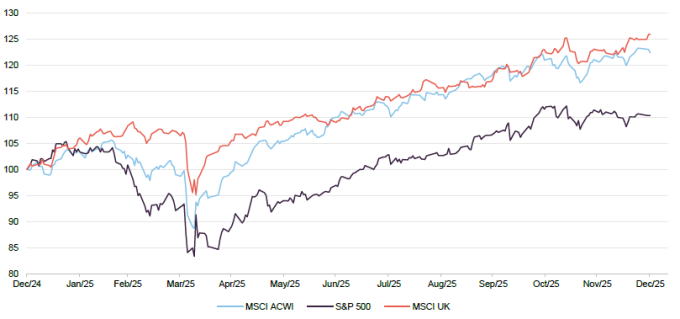
2025 was a strong year for markets, as shown in Figure 2. Global equities, measured by the MSCI ACWI Index, rose by over 20%. Markets were less dominated by one region than in recent years. While the US, represented by the S&P 500, still performed well, it did not overshadow other markets as much as before. The UK, for example, saw a recovery in sentiment and performance, with UK equities outperforming both US and global peers, as shown by the MSCI UK Index.
The chart highlights a brief period of weakness in April, when equities dropped after President Trump’s “Liberation Day” tariff announcements. However, this downturn was short-lived, with a 90-day tariff pause and ongoing negotiations helping markets recover. The rally in 2025 was global, not just led by the US.
Figure 2: Market performance over 2025, indices rebased to 100
Source: Bloomberg, Marten & Co
For the rest of the year, the easing of tariffs let investors shift their focus to company fundamentals. Balance sheets and profits stayed stable, helped by earlier cost controls and strong cash reserves, despite slower global trade. Inflation kept rising, but central banks started hinting at possible rate cuts to support growth.
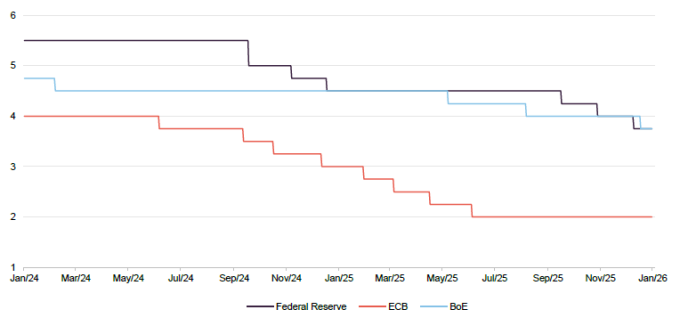
Figure 3 shows interest rates falling steadily in developed markets over the past two years. This environment is usually positive for global equities, suggesting another strong year for global markets and HWWA
Figure 3: US (Federal Reserve), eurozone (ECB) and UK (BoE) benchmark interest rates since January 2024
Source: Bloomberg, Marten & Co
Top 10 holdings
HWWA’s top 10 is closely aligned to the MSCI ACWI, but there are some important differences.
HWWA’s top 10 holdings, shown in Figure 4, are very similar to those in the MSCI ACWI Index, reflecting its construction and management style. However, there are some notable differences that highlight active management. HWWA has a higher concentration in the largest index components, mainly due to the role of momentum in its investment approach. This results in a strong focus on the “Magnificent Seven” US technology companies.
Figure 4: Top 10 holdings as at 31 December 2025
| Holding | Sector | Country | Allocation 31 December 2025 (%) | MSCI All Countries World Index (%) | Relative versus index |
|---|---|---|---|---|---|
| NVIDIA | Information technology | US | 5.1 | 4.9 | 0.2 |
| Apple | Information technology | US | 4.8 | 4.3 | 0.5 |
| Microsoft | Information technology | US | 4.1 | 3.7 | 0.6 |
| Alphabet | Communication services | US | 3.8 | 3.6 | 0.2 |
| Amazon | Consumer discretionary | US | 2.8 | 2.4 | 0.5 |
| Meta Platforms | Communication services | US | 1.6 | 1.5 | 0.1 |
| Broadcom | Information technology | US | 1.3 | 1.7 | (0.4) |
| Tesla | Consumer discretionary | US | 1.3 | 1.4 | (0.1) |
| Exxon Mobil | Energy | US | 1.1 | 0.6 | 0.5 |
| Johnson & Johnson | Health Care | US | 1.0 | 0.5 | 0.5 |
| Total of top 10 | 26.9 | 24.6 |
Source: HSBC Global Asset Management, Marten & Co
Asset allocation
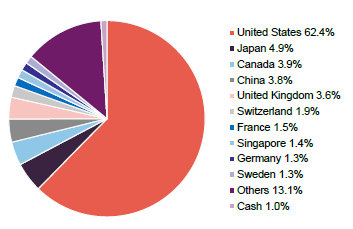
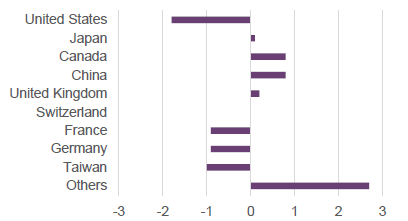
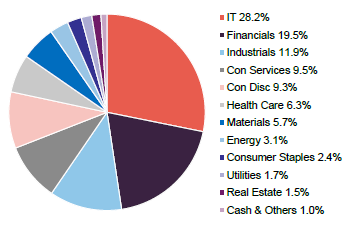
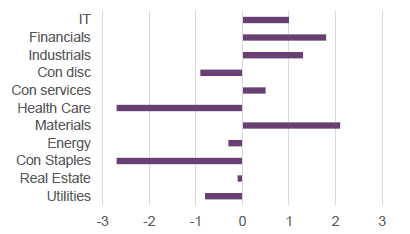
HWWA’s asset allocation is similar to the benchmark, with a strong focus on the United States and heavy weighting towards IT and financials.
Figure 5: HWWA geographic allocation as at 31 December 2025
Source: HSBC Global Asset Management
Figure 6: HWWA geographic allocation relative to MSCI ACWI, %
Source: HSBC Global Asset Management; MSCI
Figure 7: HWWA sector allocation as at 31 December 2025
Source: HSBC Global Asset Management
Figure 8: HWWA sector allocation relative to MSCI ACWI, %
Source: HSBC Global Asset Management; MSCI
Peer group
Figure 9: Total return NAV performance & fees over periods for selection of large-cap global equity active ETFs ending 31 December 2025
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | AUM (£m) | Total expense ratio (%) | |
|---|---|---|---|---|---|---|---|
| HSBC Multi Factor Worldwide Equity | 4.8 | 15.2 | 16.4 | 58.8 | 77.0 | 705 | 0.25 |
| AXA Climate Equity | 3.2 | 12.0 | 13.1 | 47.4 | – | 144 | 0.50 |
| BNP Paribas Easy ESG Enhanced World | 3.9 | 13.7 | 13.0 | – | – | 1,055 | 0.20 |
| Fidelity Global Equity Research Enhanced | 2.8 | 11.8 | 10.1 | 54.9 | 72.7 | 177 | 0.35 |
| First Trust Global Capital Strength ESG Leaders | 0.5 | 3.4 | 3.7 | 23.2 | – | 47 | 0.75 |
| Invesco Global Active ESG Equity | 4.8 | 13.7 | 14.1 | 67.4 | 102.5 | 1,457 | 0.30 |
| iShares World Equity Enhanced Active | 3.2 | 12.0 | 13.1 | 47.4 | – | 1,080 | 0.30 |
| JPM Global Research Enhanced Index Equity | 3.2 | 12.0 | 13.1 | 47.4 | – | 486 | 0.25 |
| Peer group median | 3.3 | 11.7 | 12.1 | 49.5 | 84.1 | 644 | 0.36 |
| HWWA rank | 1/8 | 1/8 | 1/8 | 2/7 | 2/3 | 4/8 | 2/8 |
Source: Morningstar, Bloomberg, Marten & Co
Figure 9 shows that HWWA has performed very well compared to other active ETFs in the global large-cap equity sector. As many active ETFs are new, there are fewer funds to compare against over the longer periods.
Comparing fees for active ETFs can be tricky, as different funds have varying levels of active management, which usually affects their level of charges. However, even with this in mind, HWWA’s total expense ratio is the joint second lowest among the funds shown in Figure 9.
Performance
HWWA’s performance closely follows the MSCI ACWI Index, as expected given its mandate. However, Figure 10 shows that active management has added value, with net returns outperforming the benchmark for most of the past five years.
Figure 10: HWWA’s NAV total return relative to MSCI ACWI index, rebased to 100, over five years to 31 December 2025
Source: Bloomberg, Marten & Co
Figure 11: Cumulative total return performance over periods ending 31 December 2025
| 1 month (%) | 3 months(%) | 6 months (%) | 1 year (%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|---|
| HWWA NAV | 0.3 | 4.8 | 15.2 | 16.4 | 58.8 | 77.0 |
| MSCI ACWI index | (0.6) | 3.3 | 13.3 | 13.9 | 58.0 | 72.5 |
| Relative performance | 0.9 | 1.5 | 1.9 | 2.5 | 0.8 | 4.5 |
Source: Bloomberg, Marten & Co.
Figure 11 shows that HWWA has outperformed the index across all periods from one month to five years, highlighting the benefits of active management.
Dividends
Dividends are passed through to shareholders, rather than being retained in the fund.
HWWA offers both income and accumulation share classes. The fund passes on cash dividends from its equity holdings to shareholders, either as payouts or by reinvesting them, rather than keeping the income. For the income class, dividends are usually paid quarterly.
The latest dividend was 9.18p per share in November 2025, following payments of 14.45p in August, 9.17p in May, and 6.74p in February. This brings the total distribution for the year to 39.54p, giving a yield of 1.4% based on the share price of £28.22 on 2 February. Investors should note that HWWA’s yield can be higher or lower than the index at any time.
Management
HWWA is managed by HSBC Investment Funds (Luxembourg) S.A., part of HSBC Global Asset Management. The fund uses a multi-factor global equity strategy within HSBC’s global investment framework.
Founded in 1973, HSBC Global Asset Management operates in over 20 countries and territories. As of 30 September 2025, it managed about US$852bn in assets and employed more than 660 investment professionals across developed and emerging markets. The firm serves a wide range of clients, including institutions, intermediaries and retail investors, through both segregated accounts and pooled funds.
HSBC combines global oversight with local market knowledge. Investment teams carry out due diligence in their regions and share research across the network. Leadership is integrated into HSBC’s overall governance, with the CEO of HSBC Asset Management reporting to HSBC’s global executive team.
IMPORTANT INFORMATION
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.