More than meets the eye
Alliance Witan (ALW) has had a frustrating period as global equity returns have become concentrated in a few large US AI-related stocks. Its diversified portfolio missed some of the rally, while its managers’ combined positioning arguably made it less responsive to rising markets than its manager, Willis Towers Watson (WTW), intended.
However, ALW’s portfolio companies have outpaced its benchmark in fundamental business growth, as discussed on page 6. Future returns could therefore come from continued business growth, rather than relying solely on improved sentiment and higher valuations.
WTW has reshaped manager allocations, as discussed on page 10, reducing those whose positioning had become too defensive and increasing exposure to managers better placed to benefit from stronger markets.
Global stock-picking portfolio
Alliance Witan aims to be a core equity holding, delivering long-term returns above inflation through capital growth and a rising dividend. It invests mainly in global shares across industries and sectors, using a ‘manager of managers’ approach. This aims to reduce the risks of relying on a single ‘star’ manager or an investment style that moves in and out of favour.
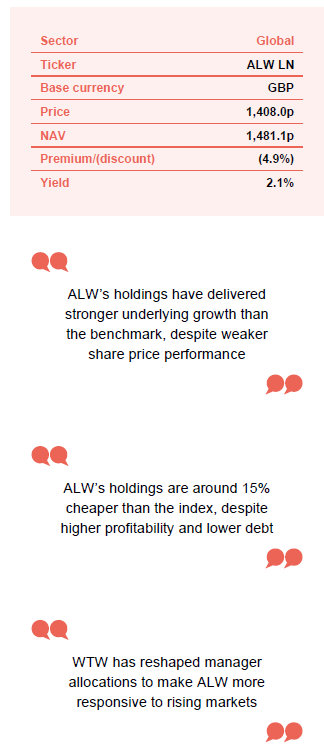
At a glance
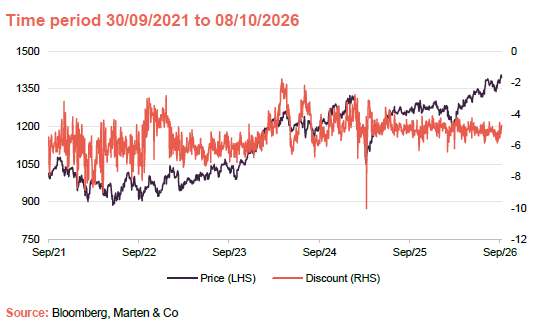
Share price and discount
ALW’s share price has risen steadily over five years, despite periods of volatility. Its discount to NAV has remained relatively stable at around 5% over the past year, supported by the board’s commitment to share buybacks.
Performance over five years
ALW has delivered positive absolute returns but has lagged the MSCI ACWI, particularly since early 2024 as market gains became concentrated in US technology stocks. Over five years, its NAV total return was 50.3%, against 75.5% for the benchmark.
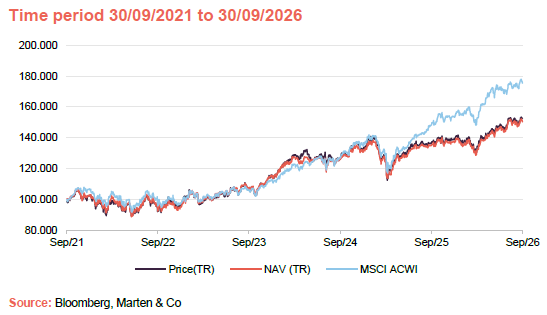
| Year ended | Share price total return (%) | NAV total return (%) | MSCI ACWI total return (%) |
|---|---|---|---|
| 30/09/22 | (7.0) | (7.5) | (4.2) |
| 30/09/23 | 15.4 | 16.0 | 10.5 |
| 30/09/24 | 17.5 | 17.4 | 19.9 |
| 30/09/25 | 8.1 | 7.2 | 16.8 |
| 30/09/26 | 12.1 | 11.3 | 18.3 |
Fund profile
“a core equity holding for investors that delivers a real return over the long term”
Alliance Witan Trust (ALW) aims to be a core investment for retail investors, professionally advised private clients and institutions, delivering long-term real returns through capital growth and a rising dividend.
Manager Willis Towers Watson (WTW) has selected 11 expert stock pickers, each managing a global portfolio of up to 20 best ideas. GQG Partners also manages a more diversified emerging markets portfolio of up to 60 stocks.
WTW combines these portfolios, balancing exposure across regions, sectors and investment styles while emphasising stock selection’s contribution to returns.
WTW’s global chief investment strategist, Craig Baker, chairs ALW’s investment committee alongside co-portfolio managers Stuart Gray and Mark Davis. WTW’s specialist portfolio management, equity manager research and operational due diligence teams support them.
The trust measures performance against the MSCI All Country World Index in sterling (MSCI ACWI), but index weightings do not influence stock selection.
ALW’s history, as Alliance Trust, dates back to 1888. WTW’s “manager of managers” approach began on 1 April 2017. ALW is an AIC Dividend Hero, having increased its dividend in each of its last 59 financial years.
Market backdrop – strong markets, narrow leadership
US equities remain near record highs
Global equity markets have advanced in 2026 despite persistent inflation, higher bond yields and renewed geopolitical uncertainty. US equities remain near record highs despite sharply higher oil prices caused by the war in Iran and long-dated US government bond yields reaching their highest levels in over two decades.
But returns have been concentrated in a few large US AI-related companies
However, returns have been concentrated in relatively few companies linked to artificial intelligence (AI). In the first half of the year, ALW’s benchmark, the MSCI ACWI index, returned 12.7%, against ALW’s net asset value total return of 7.0%. The board highlighted this unusually concentrated market as an important reason for ALW’s underperformance, as its diversified portfolio did not fully benefit from all areas of AI-related momentum.
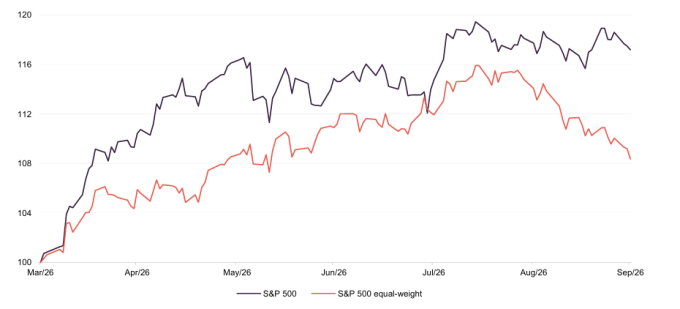
US information technology returned 29.5% in the year to the end of September, well ahead of most other sectors. And in September, technology was one of only two US sectors with positive returns. Indeed, the equal-weighted version of the S&P 500 (where each constituent has the same weight) fell sharply even as the conventional, technology-heavy index was steady. This is illustrated in Figure 1, which shows the clear outperformance of the conventional index over the equal-weighted version over the past six months, as markets recovered from their falls in the first quarter of the year.
Figure 1: US market six months to 30 September 2026, indices rebased to 100
This enthusiasm reflects a genuine structural shift. AI infrastructure spending continues to grow rapidly, driving strong demand for suppliers of computing power, semiconductors and data infrastructure. Areas such as power have also benefitted, though less visibly than technology.
This has created challenges for ALW. The trust has significant exposure to AI beneficiaries: Microsoft, NVIDIA and Taiwan Semiconductor Manufacturing were among its largest holdings at the end of August (see page 11). However, it has deliberately avoided matching the index’s increasingly concentrated exposure.
ALW’s potential edge: opportunities beyond the market leaders
WTW believes the market currently shows unusually wide divergence in valuations
Beyond technology’s headline strength, WTW sees unusually wide differences in valuations and expectations, creating distinct potential sources of return. Some AI companies may justify their valuations through rapid earnings growth; others could struggle as investors demand evidence that heavy investment is delivering adequate returns. At the same time, businesses outside the immediate AI spotlight have considerably more scope to exceed lower expectations.
ALW managers see three broad areas of AI opportunity
AI could become a broader source of returns, and ALW’s managers identify three broad opportunities. First are the suppliers of semiconductors, power generation and data centres, where demand should remain strong as AI adoption spreads. AI appears to be the next general-purpose technology. Demand may pause while businesses assess their needs and investment returns, but adoption remains at an early stage, leaving substantial scope for growth.
Second are companies that use AI to improve their businesses’ financial performance. Redesigning workflows, rather than adding AI tools to existing processes, could lower costs, increase productivity and widen profit margins. AI developments will also generate demand for capabilities that are not yet possible or even envisaged.
Third are businesses where markets may have been too quick to assume AI disruption. Companies with exclusive datasets, established customer relationships, valuable brands or physical networks may be hard to displace, while AI could strengthen their businesses. Several ALW managers seek companies whose share valuations have fallen sharply on disruption fears, but whose businesses they consider more resilient than markets expect. EdgePoint cites S&P Global, whose exclusive data cannot simply be reproduced by an AI model because it cannot be scraped from the internet.
The focus on a few very large companies has left many smaller and mid-sized businesses overlooked. ALW manager Vulcan argues that some high-quality companies trade at unusually low valuations simply because they sit outside the dominant AI theme. One example is Equifax, a data, analytics and technology company whose shares have suffered from AI disruption concerns despite its extensive and exclusive financial data and strong competitive position. Another is specialist insurance broker Ryan Specialty, whose shares Vulcan believes have been unfairly penalised by falling commercial property insurance prices.
Meanwhile, GQG sees investment spending, both AI-related and more broadly, spreading into industrial companies, utilities and financial businesses, with earnings growth beginning to accelerate beyond the technology giants.
ALW’s holdings are cheaper than the index despite having a higher return on equity
Earlier this year, WTW calculated that its holdings were around 15% cheaper than the benchmark on conventional valuation measures, despite 35% higher return on equity, 15% higher return on invested capital and around 30% less debt.
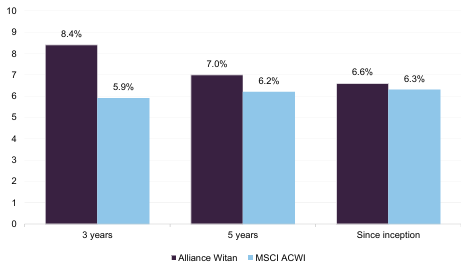
WTW also showed that ALW’s holdings had stronger underlying growth than the index, but their relative valuations had fallen. Some recent relative underperformance therefore reflects investors paying more for index winners, rather than deterioration in ALW’s businesses. Figure 2 illustrates this using WTW’s fundamental return attribution tool, which is its means of breaking down the portfolio’s share price return into fundamental return from underlying business growth and multiple return from changes in valuation.
Figure 2: Fundamental growth return of ALW’s companies versus the index, annualised, to 30 June 2026
Unusually concentrated index leadership and wide differences between companies may offer stock-picking managers more opportunities than a market with similarly valued companies. If portfolio companies keep growing earnings, cash flows and underlying value, share prices should eventually reflect this, even without a major shift in sentiment.
The valuation gap could also narrow if market leadership broadens, investors become more selective about AI, or neglected companies show that disruption fears were overstated.
Strategy review
WTW reviewed its investment approach following underperformance
ALW’s continued underperformance prompted WTW, supported by the board, to review manager selection, stock choices, portfolio construction and risk management, including each manager’s concentrated mandate. The review considered whether changes could improve shareholder outcomes in a market increasingly dominated by a few stocks and price momentum.
In September, WTW confirmed the review’s conclusion: ALW’s fundamental investment approach remained sound and should add significant long-term value. However, unusually high concentration in individual stocks and investment themes had become a defining market feature. WTW also cited wider research suggesting that changes in market structure had reduced market efficiency, increasing the need for a broader range of investment tools.
WTW has introduced an additional risk model
WTW has introduced an additional risk model to better understand overall risk and risk relative to its benchmark. It has yet to specify other tools or freedoms under consideration.
Asset allocation
ALW’s asset allocation mainly reflects its underlying managers’ stock choices. However, WTW can adjust manager allocations to improve investment returns or diversification. It normally allocates capital to avoid any dominant investment style, aiming to keep stock selection as the main driver of performance.
hi
Figure 3: ALW asset allocation by region as at 31 August 2026
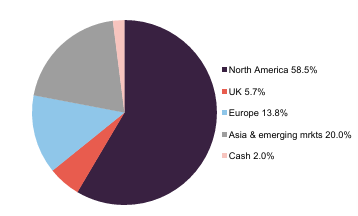
Figure 4: ALW stock portfolio asset allocation relative to benchmark as at 31 August 2026
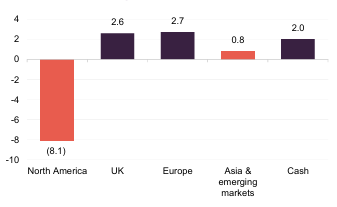
Since our March note, based on data at 28 February 2026, the North America allocation has risen slightly but remains a sizeable 8.1% underweight against the benchmark. UK and Europe remain modest overweights, although in both cases by less than in February.
Financials remain the largest sector allocation and biggest overweight against the benchmark. Information technology remains the largest underweight, and the size of this underweight has increased since our last note. Industrials and consumer discretionary weightings have risen slightly.
Figure 5: ALW asset allocation by sector as at 31 August 2026
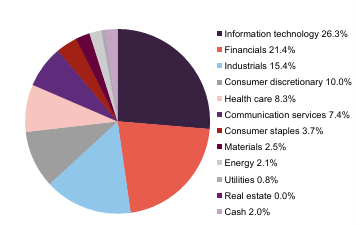
Figure 6: ALW stock portfolio asset allocation by sector relative to benchmark as at 31 August 2026
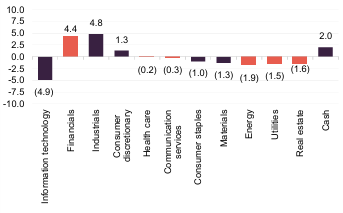
ALW’s portfolio had 72% active share at end-August 2026, versus 73% at end-February.
The managers
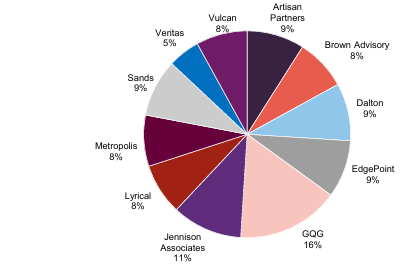
Figure 7: Portfolio split by underlying manager 31 August 2026
WTW looks beyond recent returns, assessing managers’ skills and investment processes for sustained results, including how they identify opportunities, build portfolios and control risk.
Sub-managers are unchanged so far in 2026. WTW has adjusted allocations to counter the portfolio’s tilt towards less market-sensitive stocks.
Figure 8: Change in quarterly manager allocation to end June 2026
| 31 March 2025 (%) | 30 June 2025 (%) | 30 September 2025 (%) | 31 December 2025 (%) | 31 March 2026 (%) | 30 June 2026 (%) | |
|---|---|---|---|---|---|---|
| GQG (combined portfolio) | 19 | 19 | 17 | 17 | 18 | 16 |
| Sands | 5 | 5 | 6 | 6 | 6 | 9 |
| Lyrical | 6 | 7 | 7 | 7 | 8 | 9 |
| SGA | 10 | 11 | – | – | – | – |
| Veritas | 15 | 14 | 12 | 11 | 8 | 5 |
| Vulcan | 7 | 7 | 8 | 8 | 8 | 7 |
| Metropolis | 10 | 10 | 11 | 11 | 10 | 8 |
| Dalton | 6 | 6 | 6 | 6 | 7 | 8 |
| ARGA | 8 | 8 | – | – | – | – |
| Jennison Associates | 6 | 6 | 7 | 7 | 8 | 13 |
| EdgePoint | 8 | 7 | 8 | 8 | 9 | 8 |
| Artisan Partners | – | – | 8 | 9 | 9 | 9 |
| Brown Advisory | – | – | 10 | 10 | 9 | 8 |
Reducing Veritas, GQG and Metropolis
During 2025, the underlying managers’ stock choices, particularly GQG’s shift towards defensive companies, increased ALW’s underweight position in US large-cap technology. The portfolio favoured established, lower-risk businesses the managers considered undervalued, leaving it poorly positioned for a rally driven by technology giants.
WTW responded by reducing allocations to Veritas, GQG and Metropolis. This shows how individual managers’ decisions can combine to create a portfolio bias that WTW needs to address. Adjusting allocations reduced these exposures while leaving stock choices to the individual managers.
Increasing Jennison, Sands, Lyrical and Vulcan
The capital released was used to increase allocations to Jennison, Sands, Lyrical and Vulcan, making the portfolio more sensitive to market movements. However, the four managers offer different sources of potential return.
Jennison is the most growth-focused. It seeks market-leading companies with distinctive business models, strong competitive positions and growth that is accelerating or reaching a turning point. The team will pay higher valuations where it believes growth can last but will sell when the investment case changes or it expects growth to slow.
Sands is also a growth investor but focuses more on long-term structural change. It seeks innovative businesses capable of sustained above-average growth by disrupting industries, developing products or entering large new markets. Compared with Jennison, it places less weight on shorter-term changes in growth rates and more on lasting opportunities.
Lyrical offers a different exposure. Its US-focused value strategy searches for the cheapest available stocks, distinguishing undervalued businesses from those cheap for good reason. It favours low valuations, reasonable quality and earnings growth prospects. This gives ALW exposure to overlooked US businesses whose valuations could rise, rather than relying solely on highly valued growth companies.
Vulcan combines value and quality investing. It seeks businesses with lasting competitive advantages, dependable cash flow after spending needs and relatively stable underlying values, buying when shares trade at an attractive discount. Avoiding permanent capital losses is central to its approach. Its focus on larger US companies meant a higher allocation gave WTW another way to increase ALW’s US exposure while maintaining valuation discipline.
Together, these changes show that WTW’s response to the performance issue went beyond adding growth stocks or exposure to the AI theme. It sought to make the portfolio more responsive to a rising market through managers with different approaches, while keeping stock selection as the main driver of returns.
Top 10 holdings
ALW’s largest holdings are often selected by several underlying managers. Since our last report, SAP and HCA Healthcare have replaced Unilever and Philip Morris in the top 10. The top 10 has become more concentrated in recent months, now accounting for just over a quarter of the portfolio.
Figure 9: ALW’s 10 largest holdings as at 31 August 2026
| Holding | Sector | Country | 31 August 2026 (%) | 31 January 2026 (%) | Percentage point change |
|---|---|---|---|---|---|
| Microsoft | Information technology | United States | 4.1 | 3.4 | 0.7 |
| Taiwan Semiconductor | Information technology | Taiwan | 3.8 | 2.2 | 1.6 |
| Alphabet | Communication services | United States | 3.3 | 3.1 | 0.2 |
| Amazon | Consumer discretionary | United States | 3.0 | 2.3 | 0.7 |
| NVIDIA | Information technology | United States | 2.8 | 1.3 | 1.5 |
| Mastercard | Financials | United States | 2.6 | 1.9 | 0.7 |
| Samsung Electronics | Information technology | South Korea | 2.0 | 1.3 | 0.7 |
| Visa | Financials | United States | 1.6 | 1.5 | 0.1 |
| SAP | Information technology | Germany | 1.6 | 0.4 | 1.2 |
| HCA Healthcare | Health care | United States | 1.2 | 1.0 | 0.2 |
| Total of top 10 | 26.0 | 19.6 |
Performance
ALW held up well in 2022 and 2023 but then struggled
ALW held up relatively well during 2022’s market weakness and had a stronger 2023. Since early 2024, however, it has lagged as the global equity rally became concentrated in a handful of US mega-cap technology stocks. Its diversified, multi-manager portfolio struggled to match an index driven by these companies. Short-term performance has recently improved: six-month returns are in line with the benchmark, while three-month returns are ahead.
Figure 10: ALW NAV total return performance relative to benchmark over five years to 30 September 2026
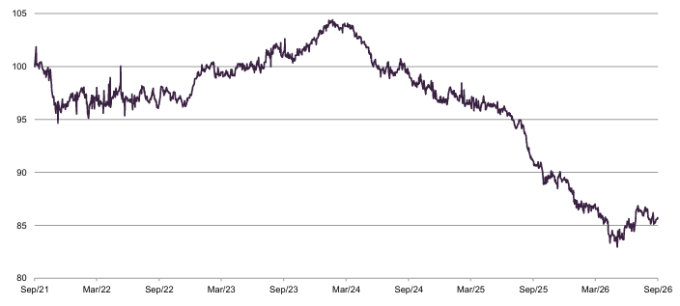
Surging shares in the largest AI companies largely explain peers’ substantial underperformance against the MSCI ACWI over five years. Figure 11 shows ALW outperformed its peers over this period.
Figure 11: Cumulative total return performance over periods ending 30 September 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| ALW share price | 3.2 | 17.0 | 12.1 | 42.4 | 52.7 |
| ALW NAV | 2.6 | 16.4 | 11.3 | 40.1 | 50.3 |
| MSCI ACWI | 1.5 | 18.2 | 18.3 | 65.7 | 75.5 |
| Peer group median NAV1 | 2.3 | 16.1 | 11.3 | 48.6 | 36.9 |
| Peer group median share price | 3.2 | 16.2 | 11.9 | 55.5 | 36.6 |
Dividend
ALW pays quarterly dividends and is an AIC Dividend Hero
ALW’s 2025 dividend was 28.32p per share, up 6.1% on 2024. Its first two quarterly dividends for 2026 are each 7.33p per share, against 7.08p for the corresponding 2025 payments, putting it on course for a 60th consecutive annual increase. This is one of the investment trust sector’s strongest dividend records, recognised by its AIC Dividend Hero status.
ALW is on course for its 60th consecutive annual dividend increase
ALW is not primarily an income fund. It aims to deliver total returns through capital growth and a rising dividend. The board expects the dividend yield to remain around 2%.
Revenue earnings of 18.5p per share in 2025 did not cover the 28.32p dividend; reserves funded the shortfall. With approximately £5.2bn of distributable reserves at 30 June 2026, the board considers the dividend policy sustainable.
Premium/(discount)
In the year to 30 September 2026, ALW’s discount stayed within a narrow range of 4.1% to 6.4%, averaging 5.0%. On 12 October 2026, it was 4.9%.
Figure 12: ALW premium/(discount) over five years to 30 September 2026
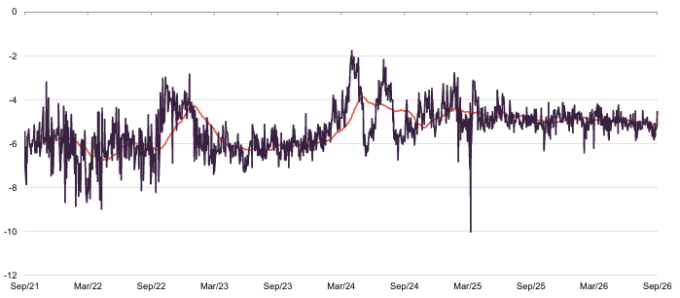
ALW’s board aims to keep its discount relatively stable, normally buying back shares when it exceeds 5%. While the latest annual report’s broader aim is to keep shares close to net asset value, chair Dean Buckley reaffirmed the 5% threshold at the April 2026 AGM.
Figure 13 shows buybacks fell in December compared with earlier in 2025, then remained fairly steady for several months. September’s figure was markedly higher.
Figure 13: ALW shares repurchased by month to 30 September 2026
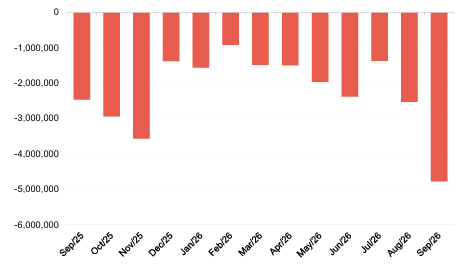
The board seeks annual shareholder approval to repurchase up to 14.99% of ALW’s issued ordinary shares. Repurchased shares are held in treasury.
SWOT analysis
Figure 14: SWOT analysis for ALW
| Strengths | Weaknesses |
|---|---|
| ALW’s multi-manager structure provides access to a range of specialist stock pickers and investment styles, reducing dependence on any single manager or approach. WTW can also adjust the amount of capital allocated to each manager as portfolio-level risks develop.
Over three years to June 2026, fundamental growth (per ALW’s fundamental return attribution tool) was 8.4% p.a. for ALW’s holdings versus 5.9% for the MSCI ACWI, while the portfolio also traded on a lower forward valuation despite generating a higher return on invested capital. ALW benefits from considerable scale, competitive costs and a strong shareholder proposition. The board expects the ongoing charges ratio to fall to around 0.51% in 2027, while the trust is on course for its 60th consecutive annual dividend increase. |
Recent relative performance has been disappointing. ALW has lagged the MSCI ACWI materially over three and five years, with its diversified portfolio failing to participate fully in the unusually concentrated rally in AI-related mega-cap stocks.
Combining independently selected portfolios can create unintended aggregate exposures. During 2026, the combined positioning of several managers left ALW with a lower sensitivity to rising markets and less exposure to some of the stocks and sectors driving index returns, requiring WTW to rebalance manager allocations. The multi-manager structure is more complex than a conventional single-manager fund. WTW must monitor not only the individual stock pickers but how their portfolios interact, and several managers can independently develop similar biases at the same time. |
| Opportunities | Threats |
| A broadening of market leadership could be beneficial to ALW’s performance. The extreme concentration of returns in a small number of AI-related stocks has been difficult for diversified active managers, but greater differentiation between winners and losers should create a more favourable environment for fundamental stock selection.
There appears to be significant latent value in the portfolio. ALW’s companies have continued to perform well at an operational level, which has not been reflected in their valuations. A combination of continued earnings growth or a partial closing of the valuation gap could provide two sources of future return. WTW has already adjusted manager weights to address the portfolio’s lower-beta bias and is evolving its approach to portfolio construction and risk management. Together with lower fees, this offers scope to improve participation in rising markets without abandoning ALW’s underlying stock-picking philosophy. |
Market leadership could remain highly concentrated. If the largest AI beneficiaries continue to dominate returns, ALW’s more diversified approach and underweights to some index heavyweights could continue to weigh on relative performance.
The expectations embedded in parts of the AI market remain high. A slowdown in AI-related investment, disappointing returns on capital or weaker economic growth could affect existing holdings, while persistent inflation and higher interest rates could put pressure on equity valuations more broadly. Individual managers can make mistakes, and diversification between stock pickers does not guarantee that their errors or style biases will offset one another. |
Bull vs. bear case
Figure 15: Bull vs. bear case for ALW
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | Recent relative performance has improved, with ALW ahead of the index over the three months to the end of August. More importantly, the underlying companies have continued to grow their perform well at an operational level, providing the foundations for a potential catch-up in share prices. | While absolute returns have been good, in relative performance terms, ALW has lagged the benchmark significantly during the last three years, which has eaten into its longer-term relative performance record. ALW’s NAV returned 8.0% p.a. over five years to the end of August versus 11.3% for the benchmark, and there is no guarantee that stronger underlying fundamentals will be rewarded quickly. |
| Dividends | ALW has increased its dividend for 59 consecutive years, one of the longest records in the investment trust sector. The board says the dividend is sustainable and can continue to grow, supported by portfolio income and substantial distributable capital reserves. | The dividend yield is relatively modest, at around the low-2% level, so ALW is unlikely to appeal to investors primarily seeking high income. The portfolio’s income alone does not currently cover the full dividend, meaning continued growth partly relies on the board’s ability and willingness to supplement distributions from capital reserves. |
| Outlook | Market leadership is showing some signs of broadening, while scrutiny of the enormous sums being invested in AI could increase differentiation between companies. This should create a richer environment for ALW’s stock pickers, both among genuine AI winners and companies where disruption fears have been overdone. | The current market regime could persist and, if returns continue to be dominated by a handful of mega-cap AI stocks, ALW’s diversified and valuation-aware portfolio could continue to lag an increasingly concentrated index. |
| Discount | The board has demonstrated its willingness to use share buybacks to keep ALW’s discount relatively stable and close to NAV. | Despite a clear commitment to using buybacks to manage ALW’s discount, the discount could come under pressure if investment performance disappoints or sentiment towards investment trusts weakens. |
| Other | ALW combines a diversified line-up of specialist stock pickers with WTW’s portfolio oversight, while lower fees and a 59-year record of dividend growth strengthen its credentials as a long-term core global equity holding. | The multi-manager model introduces an additional layer of complexity. Recent experience has shown that separately selected managers can develop similar portfolio characteristics, leaving WTW with the task of monitoring and correcting for aggregate biases whilst simultaneously avoiding undermining individual managers’ convictions. |
Previous publications
For more information about ALW, see our previous notes, listed in Figure 16 below. You can read them by clicking on the notes in Figure 16 or visiting our website.
Figure 16: QuotedData’s previously published notes on ALW
| Title | Note type | Published |
|---|---|---|
| A trust for all seasons | Initiation | 25 November 2020 |
| The fruits of diversification | Update | 04 August 2021 |
| Stability in troubled waters | Update | 17 November 2022 |
| Coming into its own | Annual overview | 16 November 2023 |
| A new powerhouse | Update | 19 September 2024 |
| A new giant for a new market reality | Annual overview | 12 August 2025 |
| Returns based more in reality than hope | Update | 12 March 2026 |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Alliance Witan Plc by Marten & Co.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.