
Primed to perform?
The extra firepower that AVI Japan Opportunity Trust (AJOT) has at its disposal following the combination with Fidelity Japan has been put to good use. The company has significant stakes in many undervalued and overcapitalised businesses and is working to unlock the latent value within them. It helps greatly that more businesses are open to engagement, meaning that much of AJOT’s work to unlock value takes place behind closed doors. However, as we proceed through another AGM season, AJOT’s manager has submitted a number of proposals that could also translate into further NAV growth for the trust.
Unlocking value in Japanese smaller companies
AJOT aims to achieve capital growth in excess of the MSCI Japan Small Cap Index by investing in a concentrated portfolio of over-capitalised small-cap Japanese equities. Asset Value Investors (AVI) leverages its four decades of experience investing in asset-backed companies to engage with company management and help to unlock value in this under-researched area of the market.
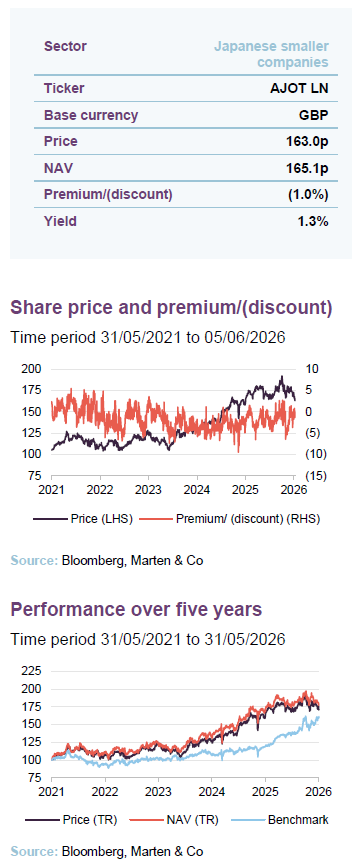
| Year ended | Share price total return (%) | NAV total return (%) | MSCI Japan Small Cap TR (%) | MSCI AC World total return (%) |
|---|---|---|---|---|
| 31/05/2022 | 7.0 | 11.1 | (6.4) | 5.4 |
| 31/05/2023 | 13.3 | 7.8 | 7.1 | 3.3 |
| 31/05/2024 | 2.3 | 12.3 | 8.0 | 20.8 |
| 31/05/2025 | 34.3 | 28.5 | 11.3 | 8.0 |
| 31/05/2026 | 3.2 | 2.7 | 33.7 | 30.7 |
Fund profile
More information is available at the fund’s website www.ajot.co.uk
AJOT is an investor in Japanese companies. Its focus is on good-quality small- and mid-cap listed companies that have a large portion of their market capitalisation in cash, listed securities or other realisable assets. AJOT’s manager seeks to engage proactively with these companies to unlock their value potential.
AJOT’s AIFM and investment manager is Asset Value Investors Limited (AVI). The lead manager working on AJOT’s portfolio is Joe Bauernfreund, one of a growing team focused on Japan, the majority of whom are Japanese-speakers.
AVI and its employees are aligned with shareholders
AVI was established in 1985 to manage what is now AVI Global Trust (AGT) and has been investing in Japan for more than four decades. AJOT was launched in October 2018 to focus on the opportunities presented by that market. At the end of April 2026, AVI and its employees owned over £4.4m worth of shares in AJOT.
In November 2025, AJOT completed a merger with Fidelity Japan Trust (FJV), issuing 110.7m AJOT shares in exchange for assets of around £184m. AJOT offers its shareholders annual exit opportunities at a small discount to NAV, which has helped to keep the trust’s shares trading close to NAV. The last of these completed in January 2026, with about 26.9m shares repurchased at a 2% discount to NAV (adjusted for the costs of providing the tender).
AJOT compares its performance to the MSCI Japan Small Cap Total Return Index, expressed in sterling terms, but the index does not inform AJOT’s portfolio construction. Consequently, AJOT has a very high active share relative to the performance benchmark.
Japan
Since we last published, Prime Minister Sanae Takaichi secured a landslide win in the snap general election that she called in early February. That gave the Liberal Democrat Party a clear majority in parliament, providing a more predictable political backdrop.
Figure 1: MSCI Japan versus MSCI ACWI
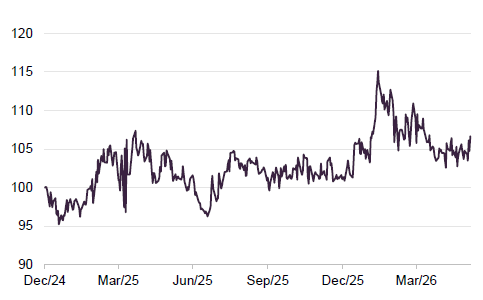
Figure 2: MSCI Japan Small Cap versus MSCI Japan
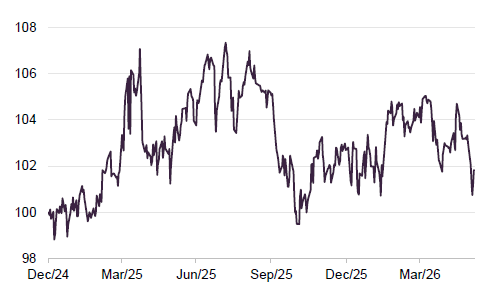
The Japanese market has done well, outperforming the MSCI ACWI, while Japanese smaller companies have marginally outpaced their larger counterparts. This has occurred despite the headwinds of a weak yen, the knock-on effects of the Iran war on energy costs (Japan imports almost all of its oil from the Gulf region), and tensions between Japan and China that have affected Chinese imports of Japanese goods.
AVI believes that relative to the wider market, AJOT’s portfolio is less sensitive to sectors that are heavily impacted by higher fuel costs
AVI believes that AJOT’s portfolio is less sensitive than the wider market to sectors that are most affected by higher fuel costs. For example, while Eiken Chemical sits in the chemical sector, it does not use petroleum feedstock in its operations. Mitsubishi Logistics may be the most sensitive, but the attraction of that investment is the considerable surplus real estate on the balance sheet rather than the operating business, which has been able to mitigate higher fuel costs through surcharges, and AVI says that AJOT’s investment case is less affected.
As in other countries, a surge in defence spending and the vast sums being invested in AI are driving related sectors. Commodities prices have been rising too, which is boosting mining stocks and companies that supply into that industry. Wages are rising, which suggests that inflation is becoming more entrenched. Unfortunately, that does not seem to have fed through into consumer spending. Rising interest rates have been supportive of financials but have not been increased since December 2025.
The yen remains weaker than many had expected, which is holding back returns for sterling-based investors. However, there is growing impetus for this to change, as a stronger yen would help ease the impact of imported inflation.
Japanese retail investors are being encouraged to invest in equities, partly on the basis that rising inflation means that it is worth looking for alternatives to cash deposits. That has been a factor supporting the stock market’s rise.
Corporate governance progress continues
The trend of improving corporate governance within Japan is undiminished
AVI says that the trend of improving corporate governance within Japan is undiminished. The new AGM season is underway, and AVI says it will be as active as ever in seeking to get shareholder-friendly resolutions passed.
The FJV deal gave the trust more firepower to take larger stakes in existing holdings as well as fund some new ones. There are now four or five companies where AJOT owns between 20% and 40% of stock. However, at the start of May 2026, Japan changed the rules on investors building up large shareholdings in companies, bringing in something akin to the UK’s Takeover Panel rules. This means that breaching 30% would trigger a mandatory bid for a company, making another 40% stake unlikely.
Investors in Japanese equities need to declare stakes of 5% or more. AVI says that these declarations can be a catalyst for a re-rating, as other investors anticipate positive news. AVI says that companies are generally much more open to engagement than they were when AJOT launched.
Even mainstream investors are focusing on corporate governance
The manager tries to build consensus by talking to as many other shareholders as possible, while being careful to avoid forming concert parties. AVI says that it often finds it is invested alongside likeminded investors and that mainstream investors have become more engaged in corporate governance issues.
AVI emphasises that there is much more upside in the strategy. It is still identifying attractively valued investments and, fundamentally, there is much more that companies can do to boost margins, improve returns on equity, and make balance sheets more efficient.
There may be further improvements to Japan’s corporate governance regime, too. AVI reports that Japan’s Financial Services Agency (FSA) is conducting its first review of the Corporate Governance Code since 2021. The outcome of this is expected later this year.
Investment process – how the portfolio is selected
Start with a simple quantitative screen
There are about 4,000 listed companies in Japan. AVI’s focus is on small- and mid-cap companies – those with market caps in a typical range of £50m to £4bn – where it can take meaningful stakes and leverage these to drive change.
AVI begins by screening, on at least a monthly basis, the market for companies with excess cash/listed securities. The data is not always easily accessible – it takes a lot of work for the analysts to find the true figures – for example, sometimes the cash has been lent to the parent company.
Not all of these are great businesses – many are effectively zombie companies existing just to provide employment or to service pension payments. Given that it can take time for activism to bear fruit, a poor-quality investee company could destroy value faster than AVI can unlock it.
Exclude loss-making and highly cyclical businesses
The next step, therefore, is to exclude loss-making and highly cyclical businesses. AVI wants to invest in companies of reasonably good quality, with resilient business models and the prospect of healthy profit growth. The targets are solid and sometimes high-margin businesses. AVI quantifies the fundamental value of these companies using measures such as EV/EBIT.
Identify route to unlocking value
The next question is how might AVI go about unlocking value; for example, are there like-minded shareholders? This step includes dialogue with other key stakeholders.
About 80–120 companies make it through AVI’s screening criteria. The team carries out in-depth research on about five to 10 companies per month. AJOT ends up making roughly one to three new investments each quarter.
Portfolio construction
From the target list, the manager maintains a single-digit number of “ready to go” opportunities on which it has performed detailed due diligence.
Each stock in the portfolio should have the potential to outperform the market on its quality and growth merits. Additional alpha then comes from the events that unlock the underlying value.
15–25 positions
AJOT is managed with about 15–25 positions and AVI is happy for AJOT to be at the low end of this. The manager applies a risk overlay to ensure that the portfolio is not over-exposed to any one sector or group of companies.
Starting with a hypothetical blank canvas, the manager would deem it appropriate to allocate roughly equally to each opportunity, given the uncertainty around how engagement will evolve. However, in reality, portfolio sizes vary based on liquidity and the manager’s conviction in the likelihood of successful engagement and the possibility of a corporate event. If some positions are relatively low in weight, this is due to availability of capital rather than a desire to have small tail positions. At the end of February 2025, around 70% of the portfolio was invested in the 10 largest positions.
Ahead of a purchase, the analysts will prepare a detailed internal note on the suitability of a stock and an allocation decision will be made based on business quality, scope for upside through engagement, and liquidity.
AVI is prepared to be patient – it can take time to get alignment amongst stakeholders. The manager would exit a position if it became clear that the desired result was not achievable or if it felt that the quality of the stock had deteriorated markedly. The expected holding period is three to five years. However, turnover has recently been higher than this due to several privatisations and corporate events.
Given the approach, AJOT’s portfolio differs markedly from benchmark indices.
AVI’s approach to engagement
No companies are truly alike, and thus AVI’s approach to engagement must be tailored to the idiosyncrasies of each company’s business model, and the governance issues that AVI is trying to remedy. However, AVI does not generally aim to take a hostile or overly aggressive approach to activism; rather, it aims to work with their management in private to find co-operative solutions to these companies’ problems. On average, AVI is meeting each investee company around seven times per annum.
Improving aspects of ESG is a core focus, as would be expected; as is improving balance sheet efficiency. However, AVI also aims to persuade company management to define and focus on core business segments, and to develop long-term strategies for achieving revenue growth and margin expansion.
AVI is prepared to go public with its concerns if they cannot resolve them in private
The team will seek to escalate the intensity of its campaigns if it is not seeing sufficient progress. For the majority of AJOT’s holdings, AVI’s campaigns will not be made public until after the outcomes have been announced, if at all. In rare cases, AVI may choose to initiate public engagement to apply additional pressure on management teams. AVI may submit shareholder proposals to drive changes in the board’s behaviour.
Investment restrictions
There are no limits on sector weightings within the portfolio. It is not expected that, at the time of investment, any single holding (including exposure by way of any derivative instrument) will represent more than 10% of AJOT’s gross assets. However, AJOT has discretion to invest up to 15% of its gross assets in a single stock if a suitable opportunity arises.
There are no restrictions on AJOT’s exposure to stocks with any given market capitalisation, but the portfolio will normally be weighted towards small- and medium-sized companies.
Derivatives can be used for efficient portfolio management purposes and to provide gearing.
Asset allocation
On 30 April 2026, reflecting the manager’s high-conviction approach, AJOT had 28 holdings, seven more than when our last note was published, but in-line with AJOT’s usual range.
The average stock in the portfolio is valued on 8.9x EV/EBIT and has net cash as a percentage of market cap of 12.4%. Based on the manager’s assessments, around 38% of the average stock’s market cap was accounted for by net cash, investment securities and stakes in other companies that were not needed for the business.
Sector allocations reflect AVI’s stock selection decisions. Compared to when we last published (using data as at 30 September 2025) the exposure to the consumer discretionary sector has risen from 16% to 24% and industrials from 22% to 28%; by contrast, exposure to consumer staples has fallen by five percentage points.
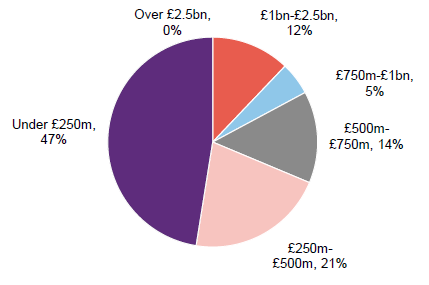
The split by market cap indicates a continued shift towards smaller companies, as flagged in previous notes, with exposure to companies with market caps of less than £250m rising from 31% to 47% since we last published.
Figure 3: AJOT sector breakdown as at 30 April 2026
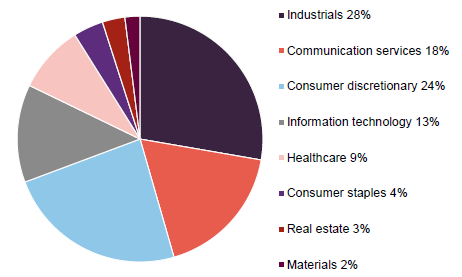
Figure 4: AJOT portfolio split by market cap as at 30 April 2026
10 largest holdings
Since we last published, using data as at end September 2025, three positions – Raito Kogyo, Rohto Pharmaceutical, and Aoyama Zaisan Networks – have exited the top 10, to be replaced by Maruzen Showa Unyu, Asiro, and Sanyo Shokai.
In February 2026, specialist construction company Raito Kogyo announced a share buyback programme alongside some good results. AVI says that this was one of several key measures – including its M&A strategy, ESG commitments, and a reconsideration of its price-to-book target – that helped drive a 20% uplift in its share price, and we believe that AJOT sold shares into this rally.
Rohto Pharmaceutical is still a large position in the portfolio. AVI has announced that it will submit a shareholder proposal to dismiss the company’s chairman Kunio Yamada at Rohto’s June 2026 AGM.
Clothing business Atsugi’s share price was weak over Q1, falling briefly out of AJOT’s top 10, but the shares rebounded in April. This is a business that it has held it since July 2024, and was loss-making for much of the past decade. AVI feels that it is very overcapitalised. Wealth management consultancy Aoyama Zaisan Networks has derated since November on the back of a profit warning related to a planned tax reform.
Figure 5: 10 largest holdings at 30 April 2026
| Holding | Industry | AVI ownership1 (%) | EV/EBIT1 (x) | NFV as % of market cap1 | ROI in JPY1 (%) | Percentage of NAV 30/04/26 | Percentage of NAV 30/09/25 | Change (%) |
|---|---|---|---|---|---|---|---|---|
| Mitsubishi Logistics | Logistics | 4.5 | 4.6 | 80 | 14.1 | 9.1 | 8.1 | 1.0 |
| SharingTechnology | Service matching platform | 28.7 | 11.8 | 15 | 24.8 | 8.6 | 7.3 | 1.3 |
| Kurabo Industries | Conglomerate | 5.0 | 2.2 | 83 | 53.7 | 8.3 | 7.8 | 0.5 |
| Eiken Chemical | Diagnostics | 8.2 | 29.5 | 8 | 61.7 | 8.3 | 9.9 | (1.6) |
| Broadmedia | Online education | 38.0 | 11.7 | 33 | 26.5 | 6.7 | 6.3 | 0.4 |
| Atsugi | Apparel, stockings | 5.7 | 7.8 | (2.1) | ||||
| Maruzen Showa Unyu | Logistics | 3.4 | 8.0 | 24 | 9.7 | 5.7 | 2.6 | 3.1 |
| Wacom | Digital pens | 13.7 | 7.0 | 12 | 15.4 | 5.5 | 10.3 | (4.5) |
| Sanyo Shokai | Apparel | 12.1 | 6.9 | 53 | 6.2 | 5.5 | 1.4 | 3.1 |
| Asiro | Media and HR platforms | 35.4 | 9.2 | 10 | 27.7 | 5.4 | – | 5.4 |
| Total | 7.82 | 383 | 68.8 | 85.5 |
Maruzen Showa Unyu
Figure 6: Maruzen Showa Unyu (JPY)
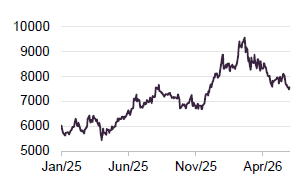
Maruzen Showa Unyu (maruzenshowa.co.jp/en) is a third-party logistics business that has been held in AJOT’s portfolio for a while. The run-up in its share price, following the publication of its Q2 results (covering the period to the end of September) in November 2025, helped push it into AJOT’s top 10 holdings. Results for the year ended 31 March 2026 showed decent (over 30%) EPS growth on modest sales growth. However, the share price has since been impacted by rising fuel costs associated with the Iran war. More recently, investor sentiment may have also been affected by the company’s plan to adopt “poison pill” measures to counter potential takeover bids. These measures will be voted on at the upcoming AGM.
Asiro
Figure 7: Asiro (JPY)
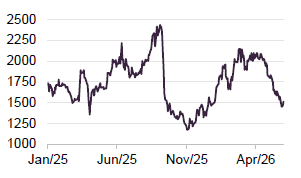
Asiro (en.asiro.co.jp) operates media platforms that connect law firms and clients (BenNavi), and job-seekers with recruitment agencies. It also has a legal insurance business. AVI has built a large stake in the business. Recent quarterly figures were disappointing, but the company is seeking to address this.
Asiro believes that advances in AI will be a net benefit to its businesses.
The company has improved its dividend payout ratio from 30% to 40% and will buy back shares.
Sanyo Shokai
Figure 8: Sanyo Shokai (JPY)
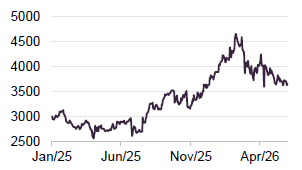
Sanyo Shokai (sanyo-shokai.co.jp/en) is a manufacturer of clothes and accessories, which it sells mainly through department stores, although it does have a growing ecommerce business. The company bought back 8% of its stock over the past financial year (cancelling almost all of its stock held in treasury along the way), which helped boost earnings per share (up 11% year-on-year, despite falling sales and profits as it realised profits on sales of investment securities), and hiked its dividend by 5%. It is forecasting only modest sales and EPS growth for FY27.
The company has been reviewing its inefficient balance sheet and is freeing up surplus land for sale at its head office in Shinjuku-ku, Tokyo.
An activist investor, Sapphireterra Capital LLC (Sanyo Shokai’s second-largest shareholder after AVI), is asking Sanyo Shokai to pay a special dividend of JPY1,200 per share. However, the company is opposing this, saying that it wants to use its balance sheet to support brand development, overseas expansion, and M&A. Proxy advisory firm ISS is recommending that shareholders vote against the special dividend proposal.
Other stocks
Synchro Food
In a departure from its usual approach, AJOT has for the first time put a member of the AVI team onto the board of an investee company – Synchro Food. AJOT first invested in the company in March 2025. Last September, AVI requisitioned an EGM, seeking to dismiss one director and appoint Kaz Sakai (see page 16) in his place. The vote passed on 26 December 2025 (fellow shareholders LIM Advisors and VIS Advisors were supportive of the proposal, and the chairman and the CEO of Synchro Food were dismissed).
Synchro Food operates a B2B platform (inshokuten.com) for restaurant businesses, matching firms with suppliers, staff, and other services. AVI felt that ill-disciplined capital allocation was weighing on investor sentiment.
Broadmedia
AJOT’s outsized stake in online education business Broadmedia was, in part, the result of a tender offer that AJOT made for Broadmedia stock in December 2025 at JPY2200 per share. The stock hit a high of JPY2444 in April 2026, helped by improving profitability, but has fallen back since.
Eiken Chemical
Eiken Chemical was the subject of bid rumours in February 2026, which drove its share price sharply higher. However, the shares have fallen back since.
Foster Electric
Figure 9: Foster Electric (JPY)
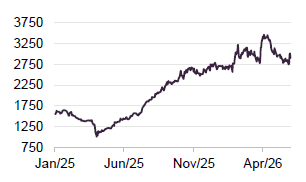
Sitting just outside AJOT’s list of top 10 holdings, Foster Electric (foster-electric.com/investors) is a manufacturer of loudspeakers, audio equipment, and electronical equipment. The business did see improving sales and profits last year, but more recent figures have been weaker.
Value-driven investor Axium Capital has been building a substantial stake in the business over recent quarters, and it said in March that it held 22.5% of the company. AVI announced a 5% stake at the end of January and said it might make proposals to the company.
In February, Foster Electric said it would form an audit and supervisory committee for the first time. It also raised its dividend forecast to JPY80 (FY25 JPY 60).
Performance
Up-to-date information on AJOT and its peers is available on our website
Although the short-term period has been more difficult, AJOT’s NAV and share price returns are still ahead of its performance benchmark, the MSCI Japan Small Cap index, over the long-term.
The nature of AJOT’s investment approach means that returns are driven by the manager’s stock selection and the success of its campaigns to unlock value. There will be periods where AJOT’s returns diverge meaningfully from the index, and therefore its performance is best considered over the long term.
Figure 10: Total return cumulative performance over various time periods to 31 May 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| AVI Japan Opportunity share price | (12.2) | (1.3) | 3.2 | 41.7 | 71.7 |
| AVI Japan Opportunity NAV | (9.5) | (2.4) | 2.7 | 48.3 | 77.6 |
| Comparator benchmark | (0.5) | 15.4 | 33.7 | 60.6 | 61.0 |
Figure 11: AJOT NAV total return performance relative to MSCI Japan Small Cap index for the five years to 31 May 2026
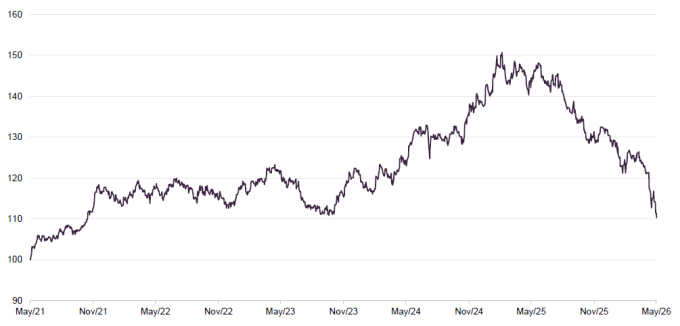
AVI says that the biggest detractors from AJOT’s returns over the six months to the end of March were Aoyama Zaisan, Synchro Food, and Atsugi (all of which are discussed above), as well as Wacom and DTS.
Digital pen business Wacom’s share price fell by 9.6% over the six-month period, but most of that fall happened in March 2026 and may just reflect wider economic concerns. The company has since announced its full-year results for the 12 months ended 31 March 2026. These showed a 4.9% fall in revenue, but its profitability was much improved on the prior year.
DTS’s share price fall was 21.6% over the period. It seems most likely that this was driven by fears over the potential impact of agentic AI on its IT services business. Actual results to 31 March 2026 were positive, with sales up 7.4% and profits increasing by 9.6%.
Dividend
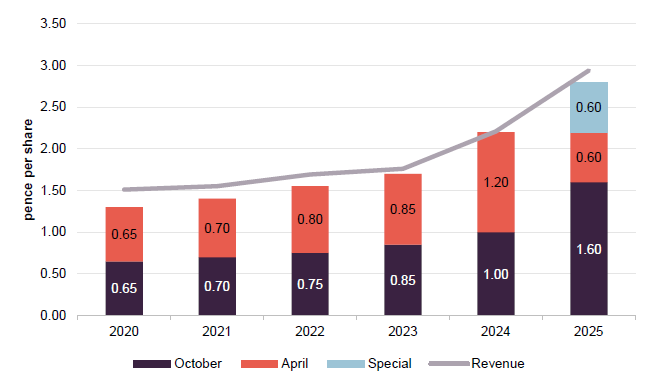
AJOT is not managed to produce any target level of income. The board distributes substantially all of AJOT’s net revenue, taking the form of semi-annual dividends declared in April and October.
AJOT’s dividends have tended to be covered by earnings, and this has allowed it to build a revenue reserve, which at the end of December 2025 stood at £2.1m or 0.95p per share.
Figure 12: AJOT dividend history – accounting years ended 31 December
Premium/(discount)
Over the 12 months ended 31 May 2026, AJOT’s shares traded between a 2.7% premium and a 6.6% discount. The average discount over the period was 1.6%. At 8 June 2026, AJOT was trading at a 1.0% discount.
AJOT’s robust discount controls, including its annual tender offer, have helped it trade relatively close to NAV. Once the dislocation of the combination with FJV was behind it, AJOT has often traded at a premium and been able to issue shares.
Figure 13: AJOT premium/discount for the five years to 31 May 2026
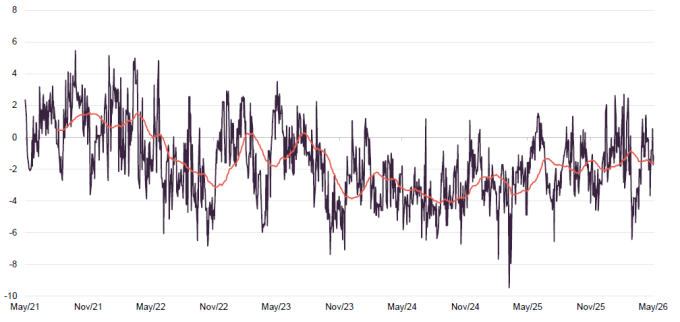
Figure 14 shows the issuance and repurchase of shares by month since the end of March 2025. On 3 April 2025, AJOT proposed the combination with Fidelity Japan Trust and on 27 November 2025, 110,674,880 new AJOT shares were issued in exchange for £184m of assets from FJV.
Figure 14: Number of shares issued/(repurchased) by month
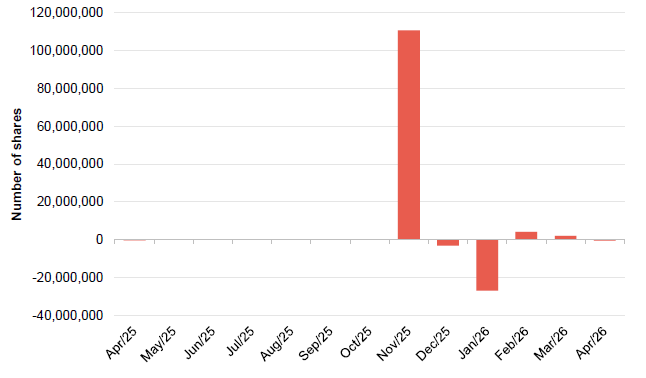
On 9 December 2025, AJOT announced the latest of its annual tender offers, providing shareholders with an uncapped exit at a 2% discount to NAV (less costs). That tender was approved by shareholders on 13 January 2026, and 26,899,713 shares (10.91% of the issued share capital) were repurchased. Since then, AJOT has both issued and repurchased shares.
At the AGM held in May 2026, shareholders gave the directors authority to issue up to 20% of AJOT’s then share capital over the following 15 months, or the next AGM, whichever is the earlier. Shares will only be issued (or reissued from treasury) at a price equal to NAV plus a premium at least sufficient to cover the costs associated with issuing the shares.
The board was also granted permission to repurchase up to 14.99% of the ordinary shares. Shares repurchased may be held in treasury.
Structure
Fees and costs
In connection with the FJV merger, AVI agreed to a new tiered management fee structure – based on the lower of market capitalisation and net assets, as before – but whereby the fee on the first £300m is 1.0%, 0.95% on the next £50m, and on assets above £350m, 0.90%. AVI continues to invest a quarter of its fees back into AJOT shares.
Tiered fee based on lower of market cap and NAV
The ongoing charges ratio for the financial year ended 31 December 2025 was 1.4%, down from 1.5% for FY24. However, the AJOT board estimated that – based on the new fee arrangements – the ongoing charges ratio should be about 1.25% on a normalised basis.
The fee structure is one that we like, as it gives the manager an incentive to work with the board to keep the discount narrow.
Capital structure
At 31 May 2026, AJOT had 247,873,823 ordinary shares in issue, 25,475,429 of which were held in treasury. Therefore, the number of shares admitted to trading and with voting rights was 222,398,394. There are no other classes of share capital. No ordinary shares were held in treasury at that date.
The company’s accounting year end is 31 December, and its AGMs are usually held in April/May.
AJOT has an unlimited life; however, as detailed above, shareholders have a regular opportunity to exit the company at a price close to NAV.
Major shareholders
Figure 15: Major shareholders as at 12 March 2026
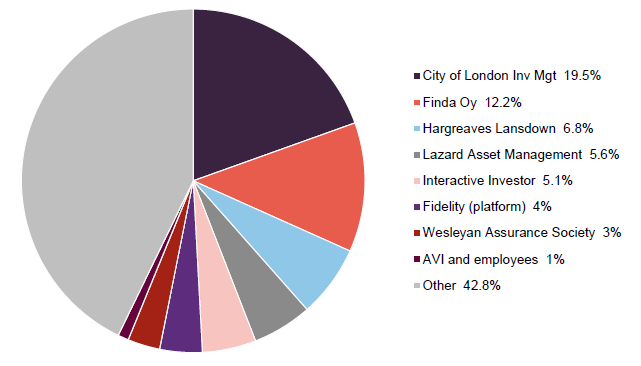
The data in Figure 15 was taken from the annual report. Since then:
- AVI has acquired a further 85,000 shares in connection with its commitment to invest at least 25% of its investment management fee into AJOT shares.
- Finda Oy has reduced its stake to 2m shares or 8.99% of AJOT.
Gearing and hedging
AJOT had a JPY6.6bn (roughly £31m) revolving credit facility that matured on 2 April 2026. Interest was charged at TONAR plus 1.55%. At the end of March 2026, the company had net gearing of 6%. There has been no announcement since 2 April, but we would expect that the facility has been renewed on similar terms.
AJOT does not currently intend to hedge its underlying currency exposure, but the board and manager keep this under review.
Management team
Joe Bauernfreund (CEO and CIO)
Joe is chief executive officer and chief investment officer of AVI. He is the sole manager of AVI Global Trust and AVI Japan Opportunity Trust, and responsible for all investment decisions across AVI’s global and Japan strategies. Before joining AVI in 2002, Joe worked for six years at a real estate investment organisation in London. He has a Masters in Finance from the London Business School.
Nicola Takada Wood (managing director Japan)
Nicola joined AVI in January 2025 from Redwheel, where she was portfolio manager and portfolio advisor of the Japan strategy. Prior to that, she was responsible for Japanese equity sales at Mizuho International and Japanese sales trading at Goldman Sachs (Japan). Nicola has a BSc from University of London, SOAS.
Kaz Sakai (head of Japan research)
Kaz started working with AVI in May 2020, researching Japanese companies while completing his MBA at Harvard Business School. He formally joined AVI’s investment team in June 2021. Prior to Harvard, he was engagement manager at McKinsey & Company’s Strategy and Corporate Finance Practice in Tokyo.
Kaz holds a BSc in Geochemistry from the University of Tokyo and an MBA from Harvard Business School.
Shuntaro Shimizu (senior investment analyst)
Shuntaro joined AVI in August 2023 from Bain & Company, where he worked within its management consultancy division. Prior to that, he worked within the Bank of Japan. He has a Bachelor of Law degree from the University of Tokyo and an MBA from Stanford Graduate School of Business.
Ross McGarry (senior investment analyst)
Ross joined AVI in June 2020. He researches South Korean holding companies and asset-backed Japanese companies.
Before joining AVI, Ross completed a one-year programme at Nomura on a UK M&A Investment Banking Industrial Placement. He has a BSc in Economics from the University of Bath.
Jason Bellamy (senior engagement consultant)
Jason joined AVI in March 2020. He works closely with the analyst team and collaborates on the engagement efforts in Japan. Jason brings more than 30 years’ experience in the financial services industry, working for and engaging with global companies, government bodies, regulators and international investors including Sumitomo Mitsui Trust Bank, First Trust Advisors and Aberdeen Standard Investments. He is based in Tokyo.
Jason has a BSc in Economics from The London School of Economics & Political Science (University of London).
Luke Hutcherson (investment analyst)
Luke joined AVI in February 2023. He researches asset-backed Japanese companies and South Korean holding companies. Before joining AVI, Luke completed internships at Tico Capital Management and Ernst & Young. He has a BCom in Finance & Accounting from the University of Sydney and an MSc in Financial Analysis from London Business School.
Yuiko Ozawa (investment analyst)
Yuiko joined AVI in March 2026 after three years working for McKinsey & Company. She has a BA in Sociology from Sophia University.
Ben Levy (ESG analyst)
Ben joined AVI in April 2025. He is responsible for the integration of ESG and sustainability assessments into the investment process.
Prior to joining AVI, Ben was a sustainable finance consultant at Guidehouse where he also served as APAC Co-ordinator for the Partnership for Carbon Accounting Financials. Ben has an MA in Economics from University of Glasgow and an MSc in Climate Change, Management & Finance from Imperial College Business School. He also holds the CFA Certificate in ESG Investing.
Board
Following the recent recruitment of Claire Binyon, AJOT has five directors, all of whom are non-executive and independent of the manager. No director sits on another board together with another member of AJOT’s board. All of the directors stand for re-election at each AGM.
Figure 16: Directors’ length of service, fees, and shareholding
| Role | Appointed | Length of service (years) | Fees (£) | Shareholding | |
|---|---|---|---|---|---|
| Norman Crighton | Chairman | 27/07/2018 | 7.9 | 50,000 | 26,575 |
| Claire Binyon | Director | 27/05/2026 | – | 40,100 | – |
| Andrew Rose | Director | 12/02/2025 | 1.3 | 40,100 | 60,000 |
| Margaret Stephens | Chair of the audit committee | 05/09/2018 | 7.8 | 43,300 | 10,000 |
| Tom Yoritaka | Director | 12/02/2025 | 1.3 | 40,100 | – |
Norman Crighton
Norman Crighton is an experienced public company director, having served on the boards of nine closed-end funds and one operating company. Presently, Norman is also non-executive chair of RM Infrastructure Income plc and non-executive director of Gore Street Energy Storage Fund plc.
Norman has extensive fund experience, having previously been Head of Closed-end Funds at Jefferies International and Investment Manager at Metage Capital Limited, leveraging his 35 years of experience in investment trusts. His career in investment banking covered research, sales, market making and proprietary trading, servicing major international institutional clients over 15 years. His work in many countries included restructuring closed-end funds, as well as several IPOs. As a fund manager, Norman managed portfolios of closed-end funds on a hedged and unhedged basis covering developed and emerging markets.
Claire Binyon
Claire is a chartered accountant and experienced non-executive director with a distinguished career including senior roles in corporate finance, strategic planning, and M&A, across blue-chip multinationals and listed companies in a wide range of sectors.
She currently serves as non-executive director and audit & risk committee chair of Murray International Trust Plc and non-executive director and audit committee chair of JPMorgan American Investment Trust Plc. She previously held non-executive roles as chair of NHBS Ltd and as a non-executive director of IG Design Group Plc (AIM-listed). Her executive career included senior corporate development and strategy leadership positions at InBev, Cadbury, DS Smith, and Fenner (a Michelin group company) amongst others.
Claire is a Fellow of the Institute of Chartered Accountants in England and Wales (FCA), having qualified with Ernst & Young.
Andrew Rose
Andrew retired from Schroders in 2019 after a distinguished 38-year career specialising in Japanese equities. His career included 11 years in Tokyo over three separate secondments, where he was involved in various research and fund management responsibilities across the market capitalisation spectrum. His specific responsibilities included managing several open- and closed-end Japanese equity funds, as well as institutional portfolios.
After retirement from full-time fund management, Andrew served as a non-executive director and member of the Audit and Supervisory Committee at Uhuru Corporation in Tokyo for three years.
Andrew is a British citizen, fluent in reading and speaking Japanese, and resides in the United Kingdom.
Margaret Stephens
Margaret has recently served on the board of Sequoia Economic Infrastructure Income Fund Limited. She previously served as non-executive board member and chair of the audit and risk committee of VH Global Energy Infrastructure Plc and was a partner of KPMG until 2016, having qualified as a Chartered Accountant in 1988. From 2007, she played a key role in building KPMG’s Global Infrastructure Practice, also leading UK and international due diligence and structuring services on major merger and acquisition transactions and public private partnerships. Margaret was a trustee director of the Nuclear Liabilities Fund and chair of the audit committee until January 2024, non-executive board member and chair of the audit and risk assurance committee of the Department for Exiting the European Union and was also a board trustee of the London School of Architecture. Margaret is British and resident in the United Kingdom.
Tom Yoritaka
Tom is a venture capital investor, software executive, and board member with over 30 years of experience in the technology industry in the UK, North America and Japan. He invests in early-stage technology and science-backed startups, and working closely with founders and co-investors, many of whom are leading venture capital funds or C-suite executives of multinational companies. He also sits on the Board of Trustees of SOAS University of London, as well as on boards of various technology industry organisations in the UK.
Previously, Tom served in software product and corporate development executive roles at Cisco Systems, Yahoo! and Microsoft in the US. Early in his career, he worked as a strategy consultant at The Boston Consulting Group in the US and Japan.
Tom is fluent in English and Japanese. He holds dual British/American citizenship and resides in the United Kingdom.
SWOT analysis
Figure 17: SWOT analysis for AJOT
| Strengths | Weaknesses |
|---|---|
| Good track record of achieving positive corporate governance outcomes | Strategy means that performance is lumpy, and short-term returns are behind peers |
| Increased firepower following FJV deal | AJOT has little exposure to hot sectors such as defence and AI capex |
| Opportunities | Threats |
| No shortage of targets | Recent small-cap outperformance could be curtailed by GDP growth hit from energy price spikes |
| Weak yen could rebound, boosting sterling returns |
Bull vs. bear case
Figure 18: Bull vs. bear case for AJOT
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | AJOT has submitted many proposals and engaged with investee companies and could be poised to reap the rewards of these | Some companies are experiencing difficult trading conditions which is weighing on share prices |
| Dividends | AJOT’s strategy can produce attractive dividends as companies increase payout ratios | Income is a byproduct of the approach and AJOT often targets companies that, amongst other things, are not paying decent dividend income |
| Outlook | AJOT has significant stakes in many companies which should help it achieve its agenda | Wider market outlook could be impacted by a weakening macroeconomic backdrop |
| Discount | Annual exit opportunity has helped keep discount tight | Annual exit opportunity could encourage a short-term mindset, with the potential for a sudden rapid shrinking of assets |
Previous publications
Readers interested in further information about AJOT may wish to read our previous notes listed below. You can read them by clicking on the links in Figure 19 or by visiting our website.
Figure 19: QuotedData’s previously published notes on AJOT
| Title | Note type | Date |
|---|---|---|
| Progress on a number of fronts | Initiation | 20 July 2021 |
| The tortoise triumphs | Update | 15 February 2022 |
| Maintaining its firepower | Annual overview | 21 October 2022 |
| Good governance, better returns | Update | 19 July 2023 |
| The sun has risen | Annual overview | 20 February 2024 |
| Pushing on an opening door | Update | 6 August 2024 |
| Reforms at a tipping point | Annual overview | 24 March 2025 |
| Hi Fidelity! | Update | 23 October 2025 |
IMPORTANT INFORMATION
This marketing communication has been prepared for AVI Japan Opportunity Trust Plc by Marten & Co, which is authorised and regulated by the Financial Conduct Authority (FCA). It constitutes non-independent research as defined under the UK MiFID II regime and the onshored Commission Delegated Regulation (EU) 2017/565.
This communication is intended for use by investment professionals as defined in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005. Marten & Co is not authorised to provide advice to retail clients. Accordingly, if you are not a professional investor, or are otherwise restricted from receiving this information, you should disregard it. The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it.
The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information.
This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.