
Stronger together
BlackRock Throgmorton (THRG) and BlackRock Smaller Companies Trust (BRSC) have announced plans to merge, creating a larger, more liquid, and lower-cost trust. The combined trust is to be managed by BRSC’s Roland Arnold and THRG’s Dan Whitestone, both highly experienced in UK smaller companies, and is expected to provide a platform for future growth.
The portfolios are already well aligned with 75% overlap in their stocks, which should make the merger process smooth. The management fee is to be cut, lowering the ongoing charges ratio by nearly 20 basis points to 0.63%, making the combined trust one of the most cost-effective among its peers.
We support the proposal, which also includes shareholder-friendly measures such as a performance-related tender offer every three years, and removes Saba from the register.
Portfolio of UK small- and mid-cap companies
THRG aims to deliver capital growth and a strong total return by mainly investing in UK small and mid-sized companies listed on the London Stock Exchange.
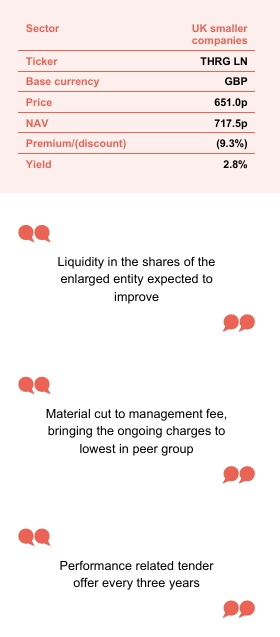
At a glance
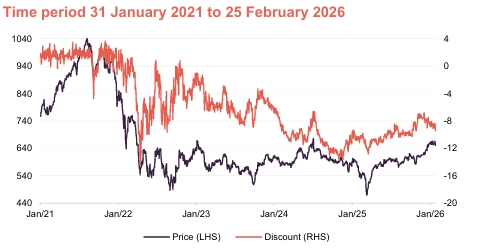
Share price and discount
THRG’s discount to net asset value (NAV) has averaged 9.7% over the past 12 months. Its shares had been trading at a premium to NAV before interest rates rose in 2022 and growth and UK investment strategies became less popular.
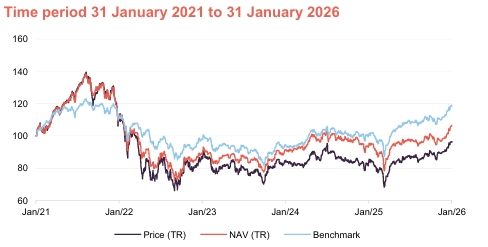
Performance over five years
THRG’s NAV total return has slipped below its benchmark over five years. Over the 10 years to January 2026, however, it has achieved NAV total returns of 129%, compared to the benchmark‘s 86%.
| Year ended | THRG share price total return (%) | THRG NAV total return (%) | BRSC share price total return (%) | BRSC NAV total return (%) | Deutsche Numis Sm Co’s +AIM, ex IC total return(%) |
|---|---|---|---|---|---|
| 31/01/2022 | 11.7 | 12.5 | 12.8 | 16.4 | 11.6 |
| 31/01/2023 | (22.8) | (20.2) | (21.4) | (16.0) | (12.4) |
| 31/01/2024 | (1.4) | 2.2 | (1.1) | (2.4) | (3.3) |
| 31/01/2025 | 0.7 | 4.3 | 5.1 | 2.4 | 7.8 |
| 31/01/2026 | 12.5 | 11.1 | 4.1 | 6.2 | 16.1 |
The merger proposal
On 20 February 2026, BlackRock Throgmorton (THRG) and BlackRock Smaller Companies (BRSC) announced plans to merge the two UK smaller companies trusts. BRSC, the larger trust, will absorb THRG, which will be wound up. THRG investors will receive new BRSC shares and both sets of shareholders will have the option to realise part of their holdings in cash. This note reviews the proposal, the outlook for the enlarged company, and key points for shareholders to consider before voting.
Rationale
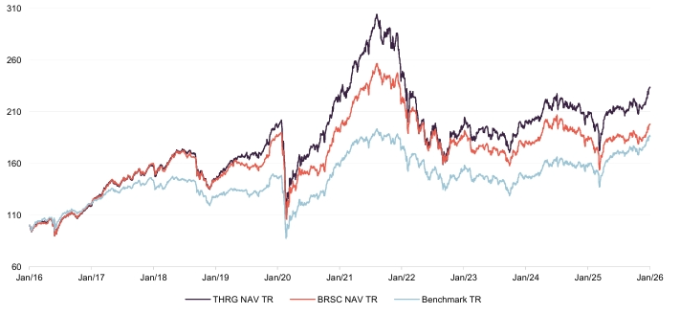
Both THRG and BRSC has outperformed their benchmark over the longer term
The proposal followed a review by THRG’s board aimed at boosting long-term value after a period of weak performance, which began when interest rates rose in 2022 and growth and UK investment strategies became less popular. Previously, both THRG and BRSC had outperformed their Deutsche Numis Smaller Companies plus AIM (excluding Investment Companies) benchmark, as shown in Figure 1.
Over the 10 years to January 2026, THRG and BRSC achieved NAV total returns of 129% and 97%, compared to the benchmark‘s 86%.
Figure 1: THRG and BRSC 10-year NAV total return performance versus benchmark1 to 31 January 2026 (rebased to 100)
Enlarged entity expected to have net assets of £780m
Merging the two trusts, which have similar investment strategies and overlapping portfolios, would create a larger entity with about £780m in net assets (assuming all cash exit options are taken up, see page 5 for details). This should improve share liquidity for both sets of shareholders and give the combined trust more flexibility in managing its discount to NAV, which has averaged 9.7% for THRG and 12.3% for BRSC over the past year.
Long-term prospects
The UK smaller companies sector has faced challenges in recent years, leading to lower valuations and weaker short-term performance for the two trusts. Despite this, both companies believe the sector remains strong with good long-term growth potential.
Valuations are at historical lows, and with possible tailwinds such as lower interest rates and continued corporate and private equity interest in the UK, the enlarged company would be well placed to benefit if sentiment improves.
To be co-managed by Roland Arnold and Dan Whitestone
As noted earlier, the combined company will be co-managed by BRSC’s Roland Arnold and THRG’s Dan Whitestone, ensuring continuity and bringing together two highly experienced UK smaller companies managers. Roland, with 20 years’ experience in UK small- and mid-cap investing, will have the final say on portfolio positioning. Dan will support him with ongoing research, drawing on his experience in UK and international markets.
Progressive dividend to be paid quarterly
The group’s dividend policy aims to build on BRSC’s record of increasing its annual dividend every year since 2003 (BRSC is an AIC “Dividend Hero”), but with plans to move to quarterly payments instead of twice a year.
THRG board members Angela Lane and Louise Nash are expected to join the enlarged BRSC board as non-executive directors, bringing the total to seven members.
Revision to investment policy
75% overlap in portfolios
The enlarged trust will continue aiming for long-term capital growth by mainly investing in UK small- and mid-cap companies, in line with both companies’ existing mandates. With a 75% overlap in stocks between THRG and BRSC, no major changes to the portfolio are planned. The trust will remain focused on quality growth companies with strong management, leading market positions, pricing power, solid balance sheets, healthy margins, strong earnings growth, and high cash conversion.
There are a few changes anticipated following the merger:
- The managers will no longer be able to short sell stocks, a feature of THRG’s policy that has had limited use in recent years.
- The managers can now invest up to 15% of the portfolio in smaller companies listed outside the UK, focusing on areas like technology that offer opportunities not available in the UK. This will be led by Dan and aims to boost returns without adding extra volatility.
No short selling, but 15% can be invested in overseas
The managers will still be able to use gearing, typically between 0% and 15% of net assets, with a maximum of 20% at the time of investment.
Figure 2: THRG’s top 10 holdings at 31 December 2025
| Company | (%) |
|---|---|
| XPS Pensions | 3.5 |
| Serco Group | 3.2 |
| Rosebank Industries | 3.1 |
| Morgan Sindall | 3.0 |
| Boku | 2.9 |
| Tatton Asset Management | 2.8 |
| Great Portland Estates | 2.6 |
| IntegraFin | 2.5 |
| Ig Group Holdings | 2.4 |
| Hochschild Mining | 2.4 |
| Total top 10 | 28.4 |
Figure 3: BRSC’s top 10 holdings at 31 December 2025
| Company | (%) |
|---|---|
| Serco Group | 3.0 |
| XPS Pensions | 3.0 |
| IntegraFin | 2.9 |
| Great Portland Estates | 2.8 |
| Boku | 2.7 |
| GreenCore Group | 2.7 |
| Tatton Asset Management | 2.6 |
| Morgan Sindall | 2.6 |
| Sigmaroc | 2.2 |
| Pollen Street Group | 2.0 |
| Total of top 10 | 26.5 |
Cash exit facility for both sets of shareholders
The merger will use a s110 reconstruction and a members’ voluntary winding up of THRG. New BRSC shares will be issued to THRG shareholders based on the relative formula asset values (NAV minus costs) of both trusts. Both THRG and BRSC shareholders can choose a cash exit at a 1% discount to NAV, capped at 38% of THRG’s and 28% of BRSC’s issued shares. To fund the cash exits, pools will be created that are made up of assets to be sold and turned into cash. This process is expected to take up to eight weeks.
Saba to fully exits positions
Saba Capital, which owns about 17.8% of THRG and 10.4% of BRSC, will fully exit its positions and has committed to do so. The current standstill agreement with Saba, which stops it from making proposals or calling meetings, will be extended to 30 June 2030 for the enlarged BRSC.
Other proposed shareholder-friendly measures include a performance-based 100% tender offer every three years if the company underperforms its benchmark, with the first possible offer in 2029 at a 4% discount to NAV after costs. Management fees paid to BlackRock will be reduced to 0.5% on the first £500m of NAV, 0.475% between £500m and £750m, and 0.45% above £750m, representing a significant cut for both trusts. The performance fee for THRG shareholders will be removed.
Reduced management fee would contribute to a lowering of the OCR to 0.63%
These changes and the greater scale achieved through the merger are expected to lower the ongoing charges ratio to about 0.63%, compared to BRSC’s 0.8% and THRG’s five-year average of 0.82% (including performance fees). This would be the lowest ongoing charges ratio in the AIC’s UK Smaller Companies sector for trusts without a performance fee.
BlackRock will help cover merger costs by waiving its management fee for six months, saving around £1.9m.
Shareholders of both trusts will vote on the merger at meetings on 26 March 2026 (BRSC) and 30 March 2026 (THRG), with at least 75% approval needed.
Previous publications
Read our previous publications on THRG by clicking the links in the table.
Figure 4: QuotedData’s previously published notes on THRG
| Title | Note type | Publication date |
|---|---|---|
| Vision, execution and adaptability | Initiation | 11 September 2018 |
| Throg’s shorts shine | Update | 16 January 2019 |
| Impressive run continues | Annual overview | 18 July 2019 |
| Look past the short-term noise | Update | 17 December 2019 |
| Separating the wheat from the chaff | Annual overview | 10 June 2020 |
| Infectious enthusiasm | Update | 14 December 2020 |
| Confidence rewarded | Annual overview | 29 September 2021 |
| Powering on | Update | 17 December 2021 |
| The strong have only gotten cheaper | Annual overview | 29 November 2022 |
| Growth in all things | Update | 22 November 2023 |
| Throgmorton’s fuse is lit | Flash update | 20 March 2024 |
| Get it while the price is good | Annual overview | 11 June 2024 |
| More bang for your buck | Update | 16 April 2025 |
Important Information
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on BlackRock Throgmorton Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.