Tomorrow’s UK market leaders
The Mercantile Investment Trust (MRC) offers an actively managed portfolio of UK-listed medium-sized and smaller companies that its investment manager believes could become market leaders. Skilled, well-resourced managers can add value in this market, as MRC’s long-term record demonstrates. Its end-August factsheet shows average annual outperformance of 2.66% against its benchmark over 10 years, with a total share price return of 137% versus 85% for the index.
Negative sentiment towards the UK weighs on valuations, despite its many growing businesses. UK shares are cheap relative to peers, particularly medium-sized and smaller companies. The government appears to recognise the problem, with initiatives underway aimed at increasing ownership of UK shares and the capital available to UK businesses. A shift in investor attitudes towards UK shares could have a disproportionately large impact on MRC’s returns.
MRC targets long-term capital growth from UK medium-sized and smaller companies, and dividend growth at least matching inflation over five to ten years. It uses long-term borrowing to increase potential returns.
Long-term capital and dividend growth
MRC targets long-term capital growth from UK medium-sized and smaller companies, and dividend growth at least matching inflation over five to ten years. It uses long-term borrowing to increase potential returns.
At a glance
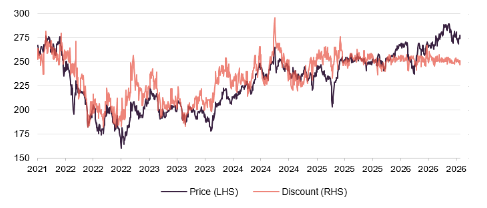
Share price and discount
MRC’s share price fell sharply in 2022 as rising interest rates weighed on UK medium-sized and smaller companies. It has since recovered much of the lost ground, although the share price discount to NAV remains wider than before the sell-off.
Time Period 30/09/2021 to 30/09/26
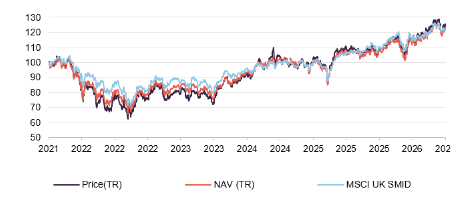
Performance over five years
MRC’s gearing amplified the negative returns in 2022. However, the trust has since recovered the ground lost relative to the MSCI UK SMID Index. Its NAV delivered a total return of 15.5% over the year to 30 September 2026, compared with 11.3% for the index.
Time Period 30/09/2021 to 30/09/26
| 12 months ended | Share price total return (%) | NAV total return (%) | MSCI UK SMID Index TR (%) | MSCI UK Index TR (%) |
|---|---|---|---|---|
| 30/09/2022 | (35.8) | (30.8) | (26.7) | 3.8 |
| 29/09/2023 | 23.0 | 19.4 | 17.4 | 14.2 |
| 30/09/2024 | 29.4 | 22.0 | 16.9 | 12.2 |
| 30/09/2025 | 6.7 | 5.7 | 9.0 | 17.2 |
| 30/09/2026 | 14.9 | 15.5 | 11.3 | 17.3 |
Fund profile
More information is available on the trust’s website: mercantileit.co.uk
Mercantile invests in attractively priced, high-quality smaller and medium-sized UK businesses with strong growth prospects that can exceed market expectations.
JPMorgan Funds Limited (JPMF), MRC’s AIFM, has delegated day-to-day portfolio management to JPMAM (UK) Limited (JPMAM). Guy Anderson and Manasij Hajra (from 1 November 2026) are co-managers.
MRC’s benchmark is the FTSE All-Share Index excluding FTSE 100 companies and investment trusts, with net dividends reinvested. This report instead uses the MSCI UK SMID Index, which has broadly similar returns and overlapping constituents.
Market background
UK small- and mid-cap (SMID) stocks outperformed large caps for many years. However, since late 2021, the prospect and then reality of rising interest rates has driven underperformance that has yet to reverse.
Figure 1: MSCI UK SMID relative to MSCI UK
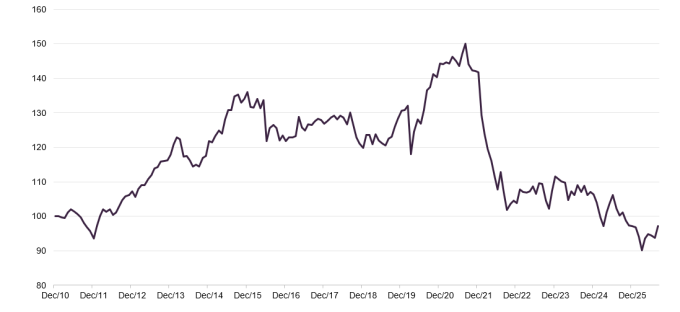
This has left UK small- and mid-cap stocks trading at lower valuation multiples than large caps, an unusual situation given their generally perceived higher growth potential.
Figure 2: Valuation multiples across various markets
| P/E (current)(x) | P/E (FY26)(x) | P/E (FY 27)(x) | Price/book (FY26) (x) | EV/EBITDA (FY26) (%) | Dividend yield (FY26) (%) | |
|---|---|---|---|---|---|---|
| MSCI UK SMID | 12.88 | 11.51 | 10.66 | 2.15 | 8.28 | 3.32 |
| MSCI UK | 14.11 | 13.26 | 12.73 | 2.38 | 9.74 | 3.22 |
| MSCI Europe ex UK | 17.64 | 16.94 | 15.42 | 2.60 | 13.82 | 2.74 |
| MSCI USA | 23.76 | 21.38 | 18.77 | 5.70 | 17.80 | 1.04 |
| MSCI ACWI | 20.67 | 18.25 | 15.98 | 3.86 | 15.28 | 1.52 |
UK stocks are also cheaper than peers, as Figure 2 shows, after years of underperformance. Figure 3 suggests this began around the announcement of a proposed Brexit referendum, accelerated during COVID and has since stabilised.
Figure 3: MSCI UK relative to MSCI ACWI
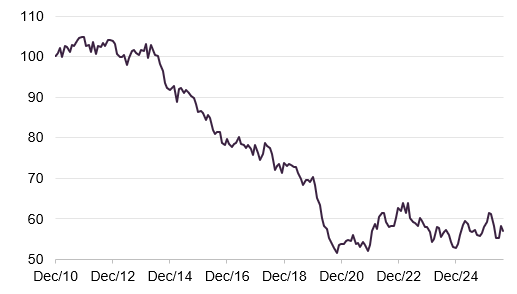
Figure 4: UK 10-year gilt yields
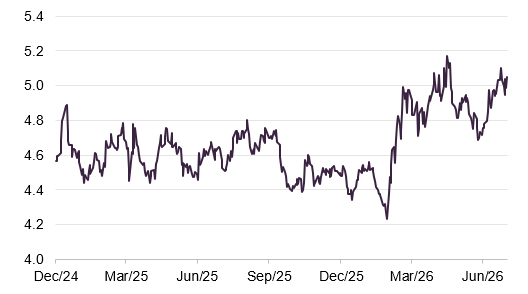
Rising energy costs following the outbreak of the Iran war have fuelled concerns about UK government finances, pushing up long-term government bond yields.
JPMAM notes that wages are still growing slightly faster than inflation. Despite persistently weak consumer confidence, spending remained resilient until recently. UK GDP continues to grow modestly.
Attractive valuations and confidence in portfolio companies’ prospects have encouraged the managers to keep MRC’s borrowing towards the upper end of its recent range. However, the portfolio is less sensitive to market movements, with a three-year beta of 0.93 at the end of July 2026. This offsets some of the extra volatility introduced by borrowing.
Investment approach
The trust’s premise is that, over the long term, mid and small caps will outperform large caps through stronger earnings growth and less analyst coverage
MRC’s managers believe medium-sized and smaller companies can deliver stronger long-term earnings growth than larger companies. Their investment universe includes businesses in rapidly growing markets, innovators and disruptors, and those able to adapt quickly to changing conditions.
Fewer external analysts cover these companies, creating information gaps that favour active managers, particularly well-resourced teams such as JPMAM. Smaller companies are also more likely to be acquired, potentially adding to returns.
The team uses external research but prioritises its own analysis. Its 400–500 meetings with company management each year provide insight into the health of UK businesses.
MRC’s portfolio should combine quality, growth and value
The process centres on selecting individual companies through detailed research. The managers seek investments combining quality, growth and value.
Quality assessments cover profitability, returns on capital employed, financial strength and management capability. MRC’s managers believe management quality becomes increasingly important among smaller companies.
Management meetings explore growth prospects, planned investment and likely returns. They also provide useful information about suppliers and customers.
Growing businesses with positive earnings momentum
The managers seek growing businesses with improving earnings, assessing prospects over at least three to five years. Potential investments should be capable of exceeding current market expectations.
The third element is value. The managers consider measures including price-to-earnings and price-to-book ratios, but prioritise free cashflow yield: the cash a business generates relative to its price.
The team monitors UK market news and meets daily to discuss developments, their potential portfolio impact, areas needing further analysis and new investment ideas. Portfolio managers and analysts also conduct ongoing company research to identify emerging themes or changes in individual businesses.
The managers consider a wide range of investment ideas, assess them and incorporate them into a full portfolio review roughly every six weeks. This focuses on checking each of the roughly 75 holdings in the portfolio and that the investment case remains valid, distinguishing short-term “noise” from meaningful news or change.
The managers assess financially material ESG factors to identify potential headwinds or tailwinds that could significantly affect a company’s share price.
They also consider portfolio-wide risks: weightings relative to the benchmark, underlying geographic and sector exposure, investment styles and major themes such as AI.
Portfolio stocks average about a 1% active weight, meaning their weighting relative to the benchmark. The managers size positions on this basis rather than by absolute weight. The smallest positions tend to be about 0.3%, as smaller holdings would barely affect MRC’s performance, and the largest 3%-4%. The largest active positions are typically 2.5%-3.5%.
Position sizes also reflect how easily shares can be traded. MRC has a minimum company market value of £100m, but in practice its smallest holdings are worth about £300m.
MRC’s managers run their winners
The managers retain successful investments while valuations remain reasonable, including stocks promoted to the FTSE 100. However, promotion increases a stock’s active weight relative to MRC’s benchmark, which may prompt a reduction.
All MRC’s large-cap holdings entered the portfolio as mid-sized companies, except Games Workshop, owner of Warhammer, which began as a small company. It has loyal customers, many lifelong fans, and high margins in its traditional business. The managers believe it has improved income from its intellectual property, which, alongside international expansion, is driving sales growth. Some overseas markets remain largely untapped. An Amazon partnership should generate direct revenue and could accelerate customer growth.
There is no hard limit on large-cap exposure, but the managers aim to keep it around 20%.
The managers never add to existing FTSE 100 holdings. They may, however, invest outside the benchmark in AIM stocks, which have accounted for about 5% of the portfolio over time.
Strict sell discipline
If the investment case no longer holds, the managers sell and reinvest in new opportunities. Their analysis of past trading decisions supports this approach.
Asset allocation
MRC’s asset allocation is driven by the managers’ stock selection decisions.
Figure 5: MRC asset allocation by sector as at 31 August 2026
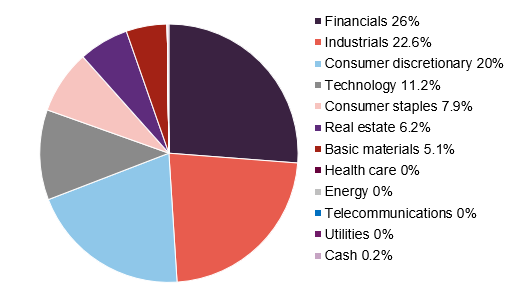
Figure 6: MRC asset allocation by sector as at 31 December 2025
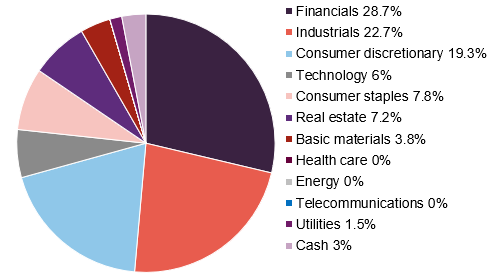
The managers note that technology’s benchmark weighting is low by international standards, but holdings such as Softcat and Computacenter make it one of the portfolio’s largest overweight positions.
Figure 7: MRC sector weights relative to benchmark as at 31 August 2026
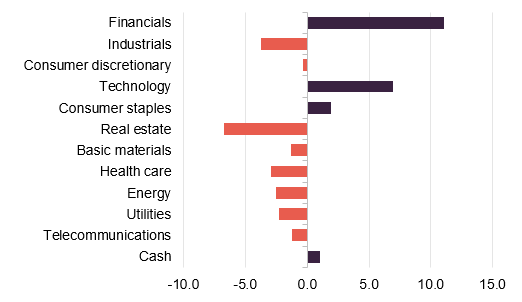
Figure 8: MRC sector weights relative to benchmark as at 31 December 2025
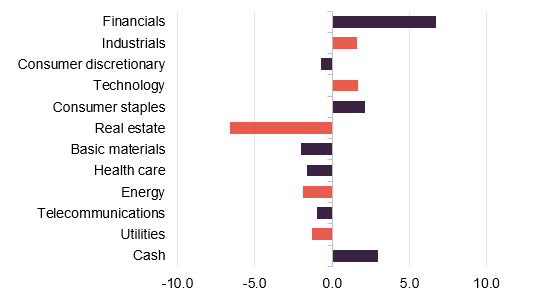
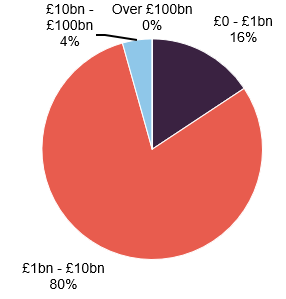
MRC’s portfolio has shifted slightly towards smaller companies this year. Since end-2025, exposure to stocks with market values above £10bn has fallen, while exposure to those below £1bn has risen.
Figure 9: MRC split by market cap at 31 August 2026
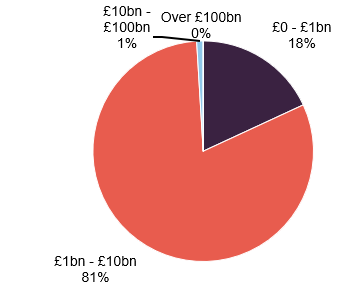
Figure 10: MRC split by market cap at 31 December 2025
MRC aims to represent an investment in some of the most promising UK listed companies, but it is not a pure play on the domestic economy – an analysis of the portfolio at the end of April 2026 suggested that 52% of the revenue of the companies in the portfolio was derived from the UK (the equivalent for the FTSE100 was 24%).
Figure 11: MRC revenue split
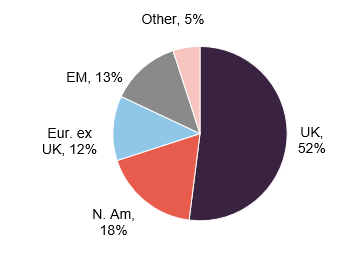
Figure 12: MRC versus benchmark as at 31 July 2026
| MRC (%) | Benchmark (%) | |
| ROIC | 14.5 | 10.8 |
| ROE | 14.3 | 11.4 |
| EPS breadth1 | 10.9 | 0.9 |
| EPS change | 1.6 | (0.8) |
| Forward earnings yield | 7.7 | 8.1 |
| Historical free cash flow yield | 7.8 | 7.9 |
Based on the analysis shown in Figure 12, MRC has a bias to businesses earning higher returns on investment and faster earnings growth, but is not having to pay up to access these stocks.
Top 10 holdings
Around a third of MRC’s portfolio is invested in its 10 largest positions. Figure 13 compares the position at end August 2026 with that at MRC’s year end on 31 January. There has been little change to the composition of the top 10, although since the year end, Rotork (which was a 2.5% position on 31 January 2026, but was reduced over the early summer on fears of slowing demand) has been bid for at a 73% premium to the prevailing share price and has left the portfolio. Computacenter, whose share price is up over 80% year to date, has moved up into the top 10.
Figure 13: MRC top 10 equity holdings at 31 August 2026
| Sector | % as at 31 August 2026 | % as at 31 January 2026 | Change (%) | |
|---|---|---|---|---|
| Softcat | Technology | 4.5 | 2.5 | 2.0 |
| ICG | Financials | 3.5 | 3.1 | 0.4 |
| Bellway | Consumer discretionary | 3.2 | 3.5 | (0.3) |
| Computacenter | Technology | 3.2 | 1.1 | 2.1 |
| Cranswick | Consumer staples | 3.2 | 3.3 | (0.1) |
| Hill & Smith | Basic materials | 3.2 | 2.4 | 0.8 |
| Balfour Beatty | Industrials | 3.1 | 3.2 | (0.1) |
| Serco | Industrials | 3.0 | 4.4 | (1.4) |
| Lion Finance | Financials | 2.7 | 2.7 | – |
| Plus500 | Financials | 2.6 | 3.8 | (1.2) |
| Total of top 10 | 32.2 |
Softcat
Figure 14: Softcat (GBp)
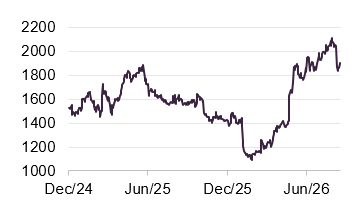
Softcat (softcat.com) helps major technology manufacturers reach small and medium-sized businesses. It mainly operates in the UK, serving over 10,000 customers. The managers highlight its strong cash generation, low asset requirements and valuation at a discount to its historical rating.
MRC bought Softcat at its November 2015 IPO, and the managers still consider it worthy of being the largest holding, reflecting their approach of holding on to winners. They trimmed the position in 2021, added in 2022 and trimmed again after the 2024 rebound. More recently, they have bought more during weakness.
JPMAM attributes Softcat’s strong organic growth record to the long-term trend towards technology adoption, supported by a strong sales culture and staff incentives. The managers believe Softcat can increase its roughly 5% market share in a fragmented industry, helped by its broader and deeper technology expertise.
In May 2026, Softcat raised its forecast for underlying operating profit growth to the mid-teens for the financial year ending 31 July 2026. However, it warned that memory shortages were affecting order flows.
ICG
Figure 15: ICG (GBp)
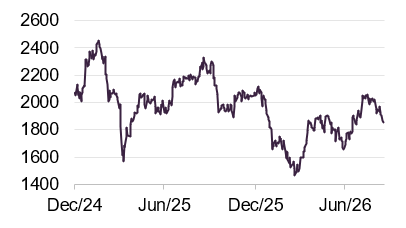
ICG (icgam.com) is a global alternative asset manager with $126bn of assets under management at 30 June 2026. Fee-earning assets totalled $88bn, up 10% over the year and 12% annually over five years. It focuses on structured capital, private equity secondaries, private debt, credit and real assets. MRC’s managers note that negative publicity around private credit may be largely justified for the asset class overall, weakening sentiment towards ICG.
However, as in 2021, when rising interest rate concerns hit alternative asset managers, fears about ICG’s ability to attract assets have proved misplaced. JPMAM notes that ICG has maintained good performance and grown assets ahead of expectations. Discussions with ICG’s management suggest no significant issues within its private credit portfolios. Its relatively limited North American presence probably helps, as most concerns centre on that region. JPMAM remains happy to weather the storm.
Bellway
Figure 16: Bellway (GBp)
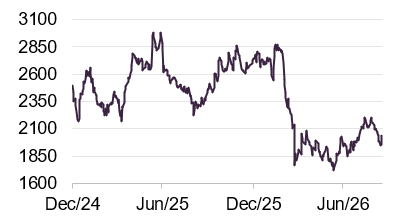
Bellway (bellwayplc.co.uk) is a housebuilder in a sector MRC’s manager sees as challenged. Housing demand is weak, mortgage rates remain higher than many would like, and costs are rising faster than house prices, squeezing margins. Fears that the Iran war would push rates higher explain the sharp share price fall shown in Figure 16.
However, JPMAM highlights Bellway’s strong record of allocating capital. It has continued investing through poor conditions, adding 8,578 plots to its landbank in the year to 31 July 2026. MRC’s managers point to a reasonably strong balance sheet, with adjusted borrowing relative to equity below 5% at end-July. Bellway aims to use capital more efficiently, which should improve returns on capital and increase shareholder returns, including a planned £50m buyback later this year. Its shares trade about 30% below book value. The managers note that history suggests investing in housebuilders during downturns pays off.
Other stocks
Elsewhere in the portfolio, MRC holds several UK industrial businesses, including Diploma, a distributor of varied industrial products. Diploma has grown sales and profits over the years through acquisitions and growth in its existing business. MRC’s managers rate CEO Johnny Thompson, who joined in 2019 and accelerated its acquisition strategy.
MRC’s more recent industrial investments include Renishaw, XP Power and Volex. These have performed well, partly helped by substantial spending on equipment and infrastructure to support AI.
Performance
Figure 17: MRC NAV relative to MSCI UK SMID Index in total return terms over five years to 30 September 2026
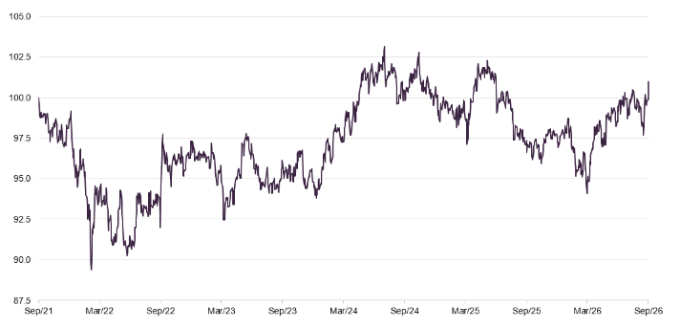
Figure 18: Total return performance over periods ending 30 September 2026
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| MRC share price | 5.7 | 21.5 | 14.9 | 58.8 | 25.3 |
| MRC NAV | 6.0 | 21.3 | 15.5 | 48.9 | 23.1 |
| MSCI UK SMID Index | 3.4 | 13.0 | 11.3 | 41.8 | 21.9 |
| Peer group median NAV1 | 6.0 | 17.3 | 12.0 | 45.8 | 23.1 |
| Peer group share price median | 5.7 | 20.3 | 13.1 | 56.7 | 25.3 |
The five-year figures reflect the 2022 market fall as interest rates rose. Small and mid-sized stocks were hit disproportionately, weighing on MRC’s returns, with borrowing amplifying the impact. Since then, MRC has recovered all its lost ground relative to the MSCI UK SMID index.
The managers say takeover activity has strongly influenced the trust’s relative performance this year. MRC benefited from some deals but missed others, including last year’s battle to acquire Spectris. It also did not hold easyJet this year.
Performance attribution
JPMAM has supplied us with some performance attribution statistics that cover the 12-month period ended 31 July 2026 and relate to returns relative to the trust’s benchmark.
Contributors
Figure 19: Relative performance positive attribution, 12 months to 31 July 2026
| Relative weight (%) | Stock return (%) | Impact (%) | |
|---|---|---|---|
| Balfour Beatty | 2.13 | 61.71 | 0.81 |
| Lion Finance Group | 1.91 | 58.98 | 0.75 |
| Softcat | 2.61 | 22.08 | 0.65 |
| Hill & Smith | 2.22 | 42.28 | 0.60 |
| Computacenter | 0.93 | 104.39 | 0.59 |
| Total | 3.40 |
Balfour Beatty’s share price has risen steadily, supported by a growing order book. It focuses on UK energy transition and security, defence and transport, and US buildings, all benefiting from long-term trends. It recently raised its earnings guidance. Hill & Smith has benefited from similar trends.
Lion Finance, formerly Bank of Georgia, is growing strongly in Georgia and Armenia, particularly through digital products, while benefiting from higher net interest margins.
Computacenter’s latest trading statement said it expects first-half profit to double year-on-year.
Detractors
Figure 20: Relative performance negative attribution, 12 months to 31 July 2026
| Relative weight (%) | Stock return (%) | Impact (%) | |
|---|---|---|---|
| 3i Group | 2.73 | (28.72) | (1.69) |
| Telecom Plus | 1.33 | (51.78) | (1.33) |
| ICG | 4.25 | (9.11) | (1.03) |
| Dunelm Group | 1.43 | (34.24) | (1.00) |
| Bellway | 2.64 | (17.70) | (0.88) |
| Total | (5.93) |
3i is a FTSE 100 private equity manager and long-standing MRC holding. Its portfolio is dominated by Action, a European discount retailer. Concerns over growth, particularly in its French business, drove a sharp share price fall. MRC’s managers reduced the position.
Household utility provider Telecom Plus faced increased customer losses, lower energy use over winter 2025/26 and stronger broadband competition. It is no longer held in the portfolio.
In hindsight, MRC’s portfolio was too exposed to UK consumer spending ahead of last year’s budget. The government’s tax increases caught it out, hurting holdings including Dunelm and Bellway.
Peer group comparison
The AIC’s UK all companies sector has five trusts with varied investment approaches. Some hold large companies, which have outperformed medium-sized and smaller companies, as discussed in the market background section. MRC’s closest competitor is probably Schroder UK Mid Cap.
Figure 21: UK all companies peer group NAV total return performance over periods ending 30 September 2026
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| MRC | 6.0 | 21.3 | 15.5 | 48.9 | 23.1 |
| Aurora UK Alpha | 3.5 | 12.5 | 2.9 | 25.8 | 31.7 |
| Baillie Gifford UK Growth | 4.6 | 19.3 | 9.6 | 43.0 | 12.9 |
| Fidelity Special Values | 8.8 | 17.3 | 20.2 | 71.0 | 80.2 |
| Schroder UK Mid Cap | 9.9 | 16.4 | 12.0 | 45.8 | 18.2 |
| Peer group median | 6.0 | 17.3 | 12.0 | 45.8 | 23.1 |
| MRC rank | 3/5 | 1/5 | 2/5 | 2/5 | 3/5 |
Markets have not rewarded quality and growth in recent years. The peer group table shows value-focused Fidelity Special Values leading over longer periods, particularly since higher interest rates returned in 2022. It has also benefited from favouring larger companies, which have outperformed small and mid-sized companies. Against this backdrop, MRC’s second place ranking over most periods is encouraging. It could take the lead once small and mid-sized company valuations recover.
Figure 22: UK all companies peer group, comparison as at 19 October 2026
| Market cap(£m) | Discount(%) | Dividend yield(%) | Ongoing charge(%) | |
|---|---|---|---|---|
| MRC | 1,715 | (10.3) | 2.9 | 0.49 |
| Aurora UK Alpha | 265 | (11.8) | 1.9 | 0.35 |
| Baillie Gifford UK Growth | 218 | (9.8) | 2.8 | 0.76 |
| Fidelity Special Values | 1,553 | (0.2) | 2.0 | 0.68 |
| Schroder UK Mid Cap | 164 | (6.4) | 2.9 | 0.92 |
| Peer group median | 265 | (9.8) | 2.8 | 0.68 |
| MRC rank | 1/5 | 4/5 | 1/5 | 2/5 |
MRC’s size as the largest trust in the peer group and competitive management fee help keep running costs relatively low. Aurora UK Alpha’s are lower, but it charges a performance fee with no base management fee.
Fidelity Special Values has sustained a much narrower discount, sometimes trading at a premium, likely reflecting its stronger recent track record. MRC’s improved performance may also lead to a better rating.
None of these trusts aims for a high dividend yield, though MRC’s is near the top of the range.
Dividend
MRC aims to grow its dividend at least in line with inflation over five to 10 years. It has a good record: over the 10 years to January 2026, its dividend rose 90.7%, compared with a 40.2% rise in the Consumer Prices Index.
MRC’s dividend has grown by an average of 8.3% a year over 32 years
MRC has at least maintained its dividend since 1992, with increases in each of the past 13 years, making it an “AIC next generation dividend hero”.
MRC declares quarterly dividends, paid in August, November, February and May. It usually declares three equal dividends followed by a larger fourth payment.
Figure 23: MRC ordinary dividends (pence per share)
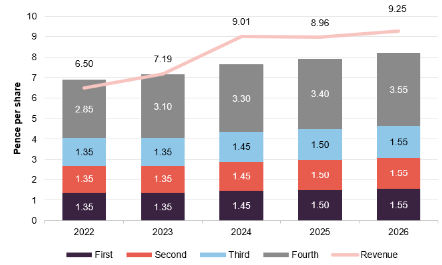
At end-January 2026, MRC’s revenue reserves totalled £104.3m, or almost 16.6p per share. It offers a dividend reinvestment plan.
Premium/(discount)
Figure 24: MRC premium/(discount) over five years ending 30 September 2026
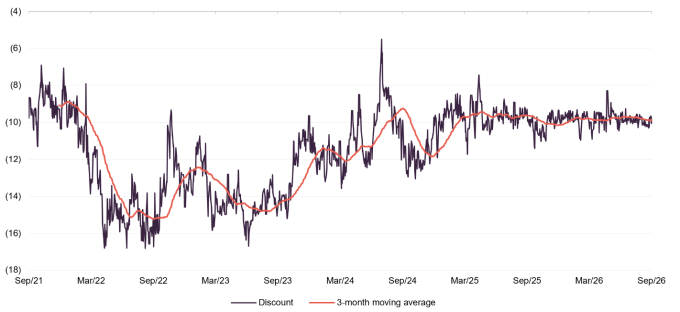
Over the year ending 30 September 2026, MRC’s shares traded at a discount of 8.3% to 11.4%, averaging 9.9%. On 16 October 2026, the discount was 10.3%.
Like many trusts, MRC’s discount widened as interest rates rose in 2022. UK political turmoil, notably the Truss/Kwarteng “Mini” budget that September, further weakened demand for UK equities and MRC. As discussed in the market background section, UK equities remain unpopular. The board has increased share buybacks, successfully keeping the discount around 10% over the past couple of years.
At the AGM on 21 May 2026, shareholders renewed the board’s authority to buy back up to 14.99% of MRC’s issued share capital, excluding shares held in treasury.
Figure 25: MRC share buybacks by month over the past year
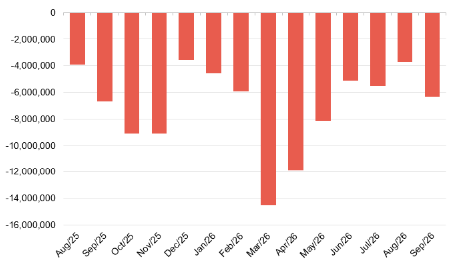
Figure 25 shows share buybacks over the past 12 months. Higher levels in March and April probably reflect investors’ concerns about the Iran war’s impact on the UK economy. Slower buybacks recently could suggest improving sentiment towards the UK.
Structure
Capital structure
At 16 October 2026, MRC had 944,492,180 ordinary shares, including 325,433,989 held in treasury, leaving 619,058,191 with voting rights. Its year-end is 31 January. Annual general meetings are usually in May.
Gearing
The board’s policy allows 10% net cash to 20% gearing in normal markets. MRC’s net gearing was 16.6% on 2 October 2026.
MRC has £175m of 6.125% debenture stock repayable on 25 February 2030, £1.08m of 4.25% perpetual debenture stock, and £150m of senior unsecured privately placed loan notes. The notes carry fixed interest rates: £55m at 1.98%, repayable on 8 September 2041; £50m at 2.05%, repayable on 8 September 2051; and £45m at 1.77%, repayable on 8 September 2061.
The notes’ terms limit net borrowings to 35% of adjusted assets and require minimum net assets of £725m.
Fees and costs
JPMorgan Funds Limited (JPMF) is MRC’s AIFM and company secretary, with a six-month notice period. Its management fee is 0.45% of MRC’s market capitalisation, encouraging the manager to keep the discount narrow. There is no performance fee.
MRC’s scale keeps average running costs low. Its ongoing charge ratio was 0.49% for the financial year ended 31 January 2026, slightly above the previous year’s 0.48%.
Management team
Guy Anderson
Guy leads JPMAM’s UK mid- and small-cap investment team and oversees UK growth mandates. He joined in 2012 after investment analyst roles at Breeden European Capital and Pendragon Capital. He holds an M.Eng (Hons) in Engineering from the University of Oxford and is a CFA charterholder.
Manasij (Manny) Hajra
Anthony Lynch has supported Guy as MRC’s co-manager for 14 years. On 15 October, it was announced that Anthony would step down at month-end for new responsibilities at JP Morgan, with Manny Hajra replacing him.
Manny is a London-based portfolio manager in JPMAM’s International Equity Group and UK mid- and small-cap investment team. He joined JPMAM as a graduate trainee in 2019 and has helped manage MRC’s portfolio for seven years. He has co-managed the JPM UK Equity Growth Fund with Guy since February 2023, holds a BA in Economics from the University of Cambridge and is a CFA charterholder.
Board
Following Richard Wilson’s appointment, MRC has six non-executive directors, none connected to the manager.
Rachel Beagles became chair in May 2025 when her predecessor retired. Graham Kitchen became senior independent director at the same time.
At the 21 May 2026 AGM, shareholders approved raising the overall cap on directors’ fees from £400,000 to £450,000.
Figure 26: Directors
| Role | Appointed | Length of service (years) | Fee | Shareholding | |
|---|---|---|---|---|---|
| Rachel Beagles | Chairman | 1 June 2021 | 5.2 | 78,000 | 115,743 |
| Graham Kitchen | Senior independent director, chair of the management engagement and remuneration committees | 1 July 2018 | 8.2 | 46,750 | 94,180 |
| Damian Maltarp | Chair of the audit and risk committee | 1 June 2021 | 5.2 | 56,000 | 28,000 |
| Heather Hopkins | Chair of the marketing and communications committee | 1 July 2018 | 8.2 | 46,750 | 25,406 |
| Julia Goh | Director | 1 January 2023 | 3.7 | 42,000 | 20,000 |
| Richard Wilson | Independent non-executive director | 3 August 2026 | 0.1 | 42,000 | 0 |
Rachel Beagles
Rachel has over 20 years’ investment company experience, including six years on the AIC board, three as chair. She was managing director and co-head of pan-European banks equity research and sales in Deutsche Bank’s corporate and investment banking division. Since 2003, she has held non-executive directorships across sectors including investment companies, asset management and fintech. She is a non-executive director of Alliance Witan Plc.
Graham Kitchen
Graham has managed UK equity funds for over 20 years, including OEICs, investment trusts and pension funds. He headed global equities at Janus Henderson Investors from 2011–2018, previously leading UK equities at Threadneedle Investments and holding roles at Invesco Asset Management. A CFA Charterholder, he holds non-executive roles as chairman of AVI Global Trust Plc and director of affordable housing provider Places for People.
Damien Maltarp
Damien has over 25 years’ financial experience and is chief financial officer at Gamma Communications plc. He previously worked at London Stock Exchange Group plc as Group Financial Controller, and BT Group Plc as enterprise CFO, previously wholesale & ventures CFO and investor relations director. Damien spent 10 years in equity analysis, including at JPMorgan Cazenove and Credit Suisse. He is a chartered accountant and ICAEW fellow.
Heather Hopkins
Heather has 20-plus years’ experience in data analytics, research, financial services and international business, specialising in retail distribution. She founded and is managing director of NextWealth Limited, providing research and consultancy to platforms, asset managers and financial advice firms on retail investment distribution’s future. She is also a director of Orbis Investments (U.K.) Limited.
Julia Goh
Julia’s London financial services career includes senior global markets roles as managing director at Barclays Investment Bank and global head of prime services risk at Credit Suisse. She began in markets as a risk manager at Nomura International after accountancy training at Coopers & Lybrand. Singaporean-born, she moved to London in 1987. She holds a BSc from the London School of Economics and Political Science, an MSc from Bayes Business School and the Institute of Directors’ Certificate in Company Direction and is an ICAEW fellow.
Julia is an independent non-executive director and audit committee chair at ICBC Standard Bank Plc, and non-executive director and audit and risk committee chair at Schroder AsiaPacific Fund Plc. She also advises Phoenix Merchant Partners as a senior adviser and is a director of Children of the Mekong charity.
Richard Wilson
Richard has over 35 years’ asset management experience. He started in 1988 as a UK equity manager at HSBC Asset Management, formerly Midland Montagu, then became managing director of global equities at Deutsche Asset Management, formerly Morgan Grenfell. He joined Gartmore Investment Management as head of international equity investments in 2003 and F&C Asset Management in 2004. As F&C’s chief executive, he oversaw its acquisition by BMO Financial Group, later becoming chief executive of BMO Global Asset Management. Previously a non-executive director of Insight Investment Management Limited, he now holds the same role at Albion Crown VCT Plc.
SWOT and bull/bear analysis
Figure 27: SWOT analysis for MRC
| Strengths | Weaknesses |
|---|---|
| MRC has a good long-term track record of outperformance of its benchmark | UK SMID stocks have generated poor performance over five and 10 years relative to large caps and peers in other developed countries |
| The portfolio has been entrusted to an experienced, well-resourced team | Adverse sentiment to the UK is weighing on valuations and successive governments have presided over declining interest in UK equities |
| MRC offers an attractive, growing, and well-covered dividend | The UK offers limited exposure to the AI capex theme that has been driving markets |
| MRC is a decent size, which comes with good liquidity and low ongoing charges | |
| Opportunities | Threats |
| The degree of undervaluation of UK SMID-cap equities relative to history and to peers suggests that there is upside | Market falls could be amplified by MRC’s relatively high gearing |
| MRC’s discount is under control but could narrow if sentiment improves | Persistent high inflation, rising borrowing costs, and weak government finances dampen enthusiasm for UK equities |
Figure 28: Bull vs. bear case for MRC
| Aspect | Bull | Bear |
| Performance | Good track record relative to benchmark | Benchmark has lagged other indices by some distance, and this has held back MRC’s returns relative to trusts with more large-cap exposure |
| Dividends | Good track record of increasing dividends faster than inflation over the long term, plus revenue reserves to support a progressive dividend | Whilst the commitment to a progressive dividend is attractive, this is not a UK equity income trust. The dividend yield is lower than most trusts in the UK equity income sector and likely to remain so |
| Outlook | Low starting point for valuations supports the case for a re-rating in time | Concerns about the UK economy persist, and MRC is sensitive to this |
| Discount | Current discount should close when sentiment improves, board has demonstrated that it will use buybacks to limit discount volatility in the meantime | Discount has been wider in the past and could spike out in times of market turbulence |
IMPORTANT INFORMATION
This marketing communication has been prepared for The Mercantile Investment Trust Plc by Marten & Co, which is authorised and regulated by the Financial Conduct Authority (FCA). It constitutes non-independent research as defined under the UK MiFID II regime and the onshored Commission Delegated Regulation (EU) 2017/565.
This communication is intended for use by investment professionals as defined in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005. Marten & Co is not authorised to provide advice to retail clients. Accordingly, if you are not a professional investor, or are otherwise restricted from receiving this information, you should disregard it.
The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it. The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.