
25 years and going strong
Private equity has been operating through an unusually difficult period, which has been extended by war in the Middle East and the ongoing debate around the impact of artificial intelligence on software valuations – slowing M&A activity and delaying exits. Against this backdrop, Patria Private Equity Trust (PPET) has delivered strong NAV total returns, beating its peer group hands down over the past 12 months (see the performance section), helped by some notable exits (see asset allocation section) – marking its 25th anniversary in style.
Despite the headwinds, PPET’s manager remains constructive on the outlook, emphasising that the underlying performance of portfolio companies remains strong, with healthy revenue and earnings growth continuing across much of the portfolio. It also believes that this period of uncertainty has created attractive investment opportunities by reducing entry valuations and sees the last two to three years as potentially strong private equity vintages. To this end, the company has continued to deploy capital through the cycle and should be rewarded when exit activity normalises and valuation confidence returns.
Private equity fund of funds with a European bias
PPET aims to achieve long-term total returns through a diversified portfolio of leading private equity funds and direct investments, the majority of which will have a mid-market European focus.
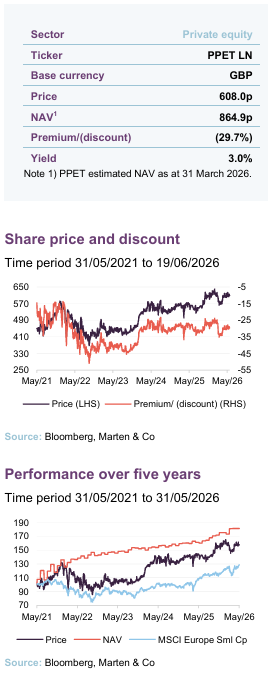
| Year ended | Share price total return (%) | NAV total return (%) | MSCI Europe Small Cap TR (%) | LPX Europe total return (%) |
|---|---|---|---|---|
| 31/05/2022 | 10.8 | 38.7 | (7.9) | (11.8) |
| 31/05/2023 | (7.6) | 6.9 | (4.8) | (10.6) |
| 31/05/2024 | 38.4 | 5.6 | 16.3 | 18.6 |
| 31/05/2025 | 0.8 | 3.0 | 6.9 | (4.3) |
| 31/05/2026 | 10.5 | 12.5 | 18.3 | (3.8) |
Source: Bloomberg, Marten & Co
Fund profile
Read more about the trust on its website: patriaprivateequitytrust.com
PPET invests in leading private equity funds and private companies in Europe. It makes primary commitments to and secondary purchases of private equity funds (mostly limited partnership vehicles, LPs), and it also makes “direct” investments into private companies via co-investments and single-asset secondaries.
The private equity sector has an enviable long-term track record and PPET is no exception to this. However, most investors cannot access the asset class directly. Listed private equity vehicles such as PPET allow anyone exposure to private equity through a liquid listed vehicle that can be bought and sold on a daily basis.
Mid-market deals consistently outperform large- and mega-cap LBOs
The underlying companies that PPET backs tend to be growing, cash generative businesses in the mid-market range (companies with an EV of €100m–€1bn), which PPET’s manager says is under-serviced by the private equity industry when compared to the large- and mega-cap space. This means that not only is there less competition for the highest-quality companies, but the companies have greater opportunity for value creation and less reliance on IPO as an exit route. This gives PPET an edge, given its longstanding relationships with Europe’s mid-market-focused managers.
Patria says that the returns on mid-market deals tend to beat market averages. It quotes an Preqin report that found small- and mid-market funds outperformed larger buyout funds by a median 266bps on a net IRR basis and a +0.1x net TVPI. Patria also observes that there is a deeper pool of potential investments than in the large cap segment, entry prices tend to be lower, there are more opportunities to create value, and there is greater optionality around exits for firms of this size.
The trust turns 25 years old this year, having been launched in 2001 as Standard Life European Private Equity (later Standard Life Private Equity and then abrdn Private Equity Opportunities). In April 2024, Aberdeen Group Plc sold its European private equity business to Patria Investments, and the company changed its name once more. The senior team managing the portfolio, led by Alan Gauld, was unchanged, but it now benefits from the greater resources that Patria can offer; Patria Investments has AUM of about $60bn.
Market update
Concerns over AI disruption of software businesses has hit valuations
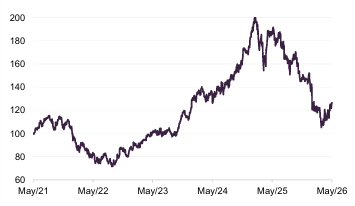
Concerns around AI disruption of software businesses have intensified this year after Anthropic launched a range of productivity tools that compete with existing software programmes. This has led to an indiscriminate sell-off of software stocks and impacted on the valuation of private companies in this sector and, in turn, private equity trusts with exposure to them. This includes PPET, which has around a fifth of its portfolio exposed to software companies.
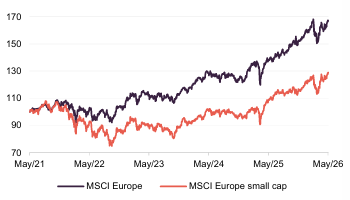
Figure 1: MSCI Europe and MSCI Europe Small Cap total return
Source: Bloomberg, Marten & Co
Figure 2: MSCI Europe Software Index
Source: Bloomberg, Marten & Co
PPET’s manager believes that the sell-off has been too broad-brush, with the whole software sector treated as one and the finer detail ignored. For example, its states that the type of software, the customer it serves, and the data set it uses all determine how exposed any given business is.
Broad brush software sell-off ignores nuances across the sector
It says that disruption potential is real in application software – the tools that run day-to-day workflows, serve customers and manage operations – citing contact centres where AI conversation agents have already replaced swathes of human agents and adoption is only expected to accelerate. However, it stresses that others in the software sphere are well protected.
Consistently overlooked, the manager believes, is the meaningful barrier to disruption that proprietary and regulated data holds and that large language models alone cannot easily replicate. In “high-stakes” business processes – such as those in financial services, healthcare and legal sectors – certainty, auditability and regulatory compliance have created a competitive advantage and make them less vulnerable to disruption from general-purpose AI models. This has reinforced their competitive advantages, the manager says.
Significant uncertainty in software valuations now exists. Until it becomes clearer which companies will benefit from AI adoption and which may be disrupted by it, valuations are likely to remain volatile. And whilst this will slow transaction activity in the near-term, PPET’s manager believes that businesses that successfully integrate AI into trusted software platforms are likely to strengthen their competitive positions and create significant value in the long-term.
Software buyouts at lowest level since Covid
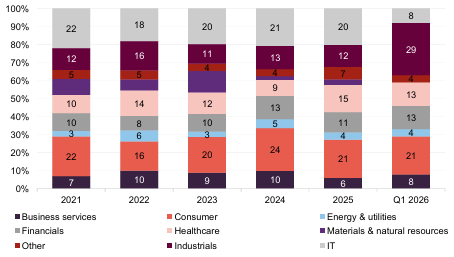
Unsurprisingly, deal activity in the sector has dried up. Buyouts in the software sector have fallen to their lowest levels since Covid, with just $50bn recorded in the first five months of 2026, from $88bn in the same period last year, according to PitchBook. As Figure 3 shows, deal activity has rotated out of software and into industrials.
Figure 3: Deal activity by sector (deal count)
Source: Preqin
Despite software valuations having contracted, PPET has continued to commit capital to specialist technology investors, including software-focused private equity managers such as Hg and Expedition, stating that a compelling investment thesis is forming. It believes that attractive opportunities remain available across the sector and that these private equity firms have proven skills in identifying businesses capable of embedding AI within existing workflows and delivering tangible productivity improvements to customers.
Around a fifth of PPET’s portfolio is exposed to software companies which may mean that it is, in effect, starved of an exit opportunity in the near term. For example, uncertainty put paid to the planned London IPO of Norwegian software company Visma this year, which was PPET’s third-largest holding at the end of 2025.
Exit opportunities scarce
War in the Middle East is the latest global event to have impacted the private equity exit landscape, with the market also contending with inflation, higher interest rates, war in Ukraine, and tariff uncertainty in recent years. Pricing has softened during the past few years, with the implied cash yield for global buyout funds averaging 14.2% between 2022 and 2025, compared to 26.5% between 2013 and 2021, according to Preqin.
Lower entry valuations and less competitive deal environments improve future return profile
PPET’s manager stresses that the prolonged period of uncertainty that has impacted market liquidity and valuation confidence has not yet affected business fundamentals, with PPET portfolio companies continuing to deliver healthy revenue and earnings growth. Among its top 100 underlying portfolio companies, the average revenue growth over the 12 months to 30 September 2025 was 12.4% and the average EBITDA growth over the same period was 13.1%.
Although geopolitical events may delay exits and reduce short-term liquidity, the manager states that periods of uncertainty improve future investment opportunities by creating lower entry valuations and less-competitive deal environments, while giving investors more time to conduct detailed due diligence. In its view, some of the strongest private equity vintages are created during periods when market sentiment is weak and transaction activity is subdued.
This is why PPET has continued to invest during this period (see page 13 for details of recent transactions), balanced with other capital allocation objectives including share buybacks.
Investment process
PPET’s board oversees strategy, provides guidance to the manager, and challenges the investment approach at least annually, while day-to-day management is delegated to Patria Capital Partners.
PPET’s portfolio construction committee drives the top-down element of the investment process
The investment process combines top-down and bottom-up analysis. A semi-annual Portfolio Construction Committee (PCC) assesses the European macroeconomic environment, shaping long-term asset allocation and geographic focus. Although allocation changes gradually, the PCC develops country-level convictions on where the strongest opportunities exist.
PPET’s European remit includes the UK. The manager estimates its universe contains around 1,500 European private equity funds, of which roughly 800 are considered “institutional grade” and theoretically suitable. Through origination efforts and regional specialists, PPET tracks these funds closely. Since European private equity firms typically raise capital every three to five years, around 150 funds are reviewed annually, though only a small number pass the screening process.
PPET identifies around five to 10 preferred funds in each market, with the strongest candidates forming the investment pipeline. The strategy has a bias toward northern Europe, where private equity markets are most developed. Detailed due diligence generally lasts around three months for primary fund investments, and one month for secondaries and direct investments.
PPET looks for “operational alpha”
A key selection principle is “operational alpha” — the value created by managers actively improving portfolio companies rather than acting as passive financial investors. Preferred managers typically possess substantial in-house industrial expertise that can support portfolio businesses. PPET also evaluates whether managers have differentiated strategies or sourcing capabilities, as well as strong and experienced investment teams. Sector specialists with consistent strategies are favoured, while any strategic or size drift may trigger a review. The manager also avoids excessive concentration risk within fund portfolios.
PPET looks for motivated and stable underlying managers
Team stability and alignment are important considerations. PPET prefers motivated managers with strong succession planning and generally avoids firms operating an “investment bank” model, where staff turnover is often higher. Whilst the manager reviews a broad range of fund sizes and managers, its focus is on companies with enterprise values between €100m and €1bn.
Historical performance is analysed carefully, albeit recognised as backward looking and comprises only around 20% of a manager’s score. A high proportion of loss-making investments is viewed negatively, though the manager acknowledges that some losses are inevitable in private equity and prefers managers that demonstrate learning and improvement over time.
Long-term bias towards Europe
Although PPET is not exclusively focused on Europe, it maintains a strong long-term preference for European companies, where the manager sees a deep pool of family and founder-owned businesses that private equity firms can help to further grow. The team believes Europe’s fragmented landscape — including differences in language, culture, and regulation — creates barriers to entry that favour established firms with local presence over competitors using a “fly-in” model. This often reduces competition in the European mid-market and allows acquisitions at more attractive entry valuations. Europe is also viewed as a leader in ESG, with European private equity firms generally at the forefront of industry practices.
Fees on the underlying funds
PPET focuses on potential returns, net of fees
PPET devotes significant attention to analysing fund structures, ensuring fees are market-standard, managers are appropriately incentivised, and interests are aligned with investors. However, investment decisions prioritise the best risk-adjusted net returns after fees, rather than simply the lowest headline costs.
PPET itself does not charge a performance fee in addition to the fees paid to underlying managers. More detail on PPET’s fee structure can be found on page 19.
Managing commitment levels
PPET carefully manages over-commitments to minimise cash drag. Total outstanding commitments were £836.0m at the end of March 2026
Patria manages the portfolio to maintain a diversified maturity profile, using detailed cash flow modelling to forecast drawdowns and distributions. The manager does not hedge currency exposure, believing the cost outweighs the potential benefit. Uninvested cash is held in euros, sterling, or US dollars to reflect underlying exposures. We discuss the fund’s borrowing facilities on page 20.
PPET has followed an over-commitment strategy since inception in 2001. As of 31 March 2026, outstanding commitments totalled £836.0m, although approximately £82.3m is considered unlikely to be drawn.
Portfolio construction
PPET targets returns of 1.7x cost/15% IRR
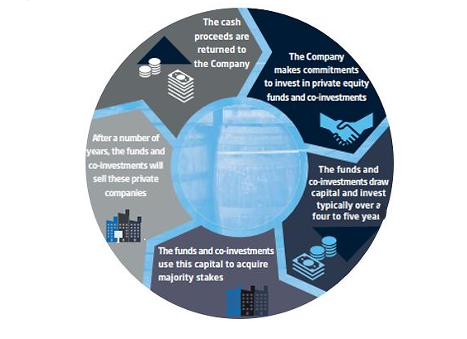
The investment process typically results in six to eight new primary fund commitments annually, each around €30m. Target net returns are at least 1.7x invested cost over the investment life and a 15% IRR.
Figure 4: PPET’s investment cycle
Source: Patria
Secondaries and direct investments
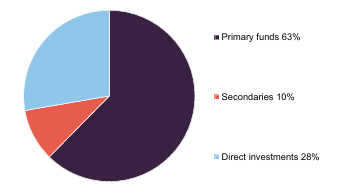
Secondaries were previously a growing component of the portfolio, but their weighting has declined in recent years as PPET has increased its focus on direct investments. In these transactions, PPET invests directly alongside underlying private equity firms rather than solely through LP fund commitments. At the end of December 2025, direct investments made up 28% of the portfolio.
Direct investments and secondaries provide several advantages: greater control over deployment timing, the ability to invest later once a company’s progress is clearer, more targeted exposure to attractive sectors or specific deals, and lower look-through ongoing charges because these investments typically involve lower or no management fees.
The portfolio is monitored closely. PPET team members often sit on fund advisory boards, providing strategic oversight without participating in day-to-day management, and meet underlying managers quarterly. The manager says that it receives a high level of transparency into underlying portfolios, although not all company-level information can be disclosed publicly. Instead, PPET publishes aggregate metrics such as earnings growth and leverage levels.
PPET generally holds investments to maturity but may sell positions in the secondary market if expected returns fall below target levels or if it believes maximum value has already been realised.
Asset allocation
PPET’s portfolio was valued at £1,412m at the end of December 2025, providing exposure to more than 700 underlying companies, with a continued focus on mid-market investments.
As of the end of 2025, 63% of the fund’s NAV was invested in LPs managed by 17 core European private equity managers, which comprise the primaries component of the portfolio. The weighting towards direct investments has steadily increased over the last few years to 28% across 37 companies at the end of 2025. The manager says that direct investments provide a more concentrated exposure to the team’s highest-conviction portfolio companies while lowering fee drag, because co-investments typically come with no fee or carried interest attached. It intends to continue increasing its exposure to direct investments, arguing that if executed well, they should perform better than primary fund investments.
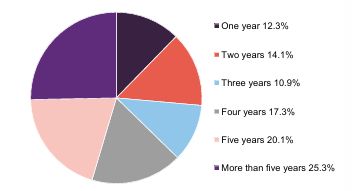
Figure 5: NAV split by holding period at 31 December 2025
Source: PPET
Figure 6: NAV split by investment type at 31 December 2025
Source: PPET. Note: Does not sum to 100 due to rounding.
The portfolio remains well-diversified by vintage, with around 62% of the underlying portfolio (including 22 direct investments) held for four years or more, with around a quarter have been held in excess of five years old (this being the sweet spot for realisations). This represents approximately £885m of portfolio value that is theoretically “ripe for exit” when market conditions improve.
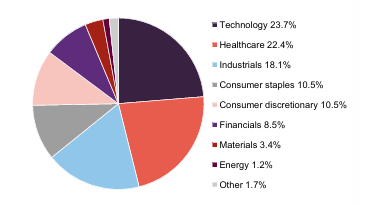
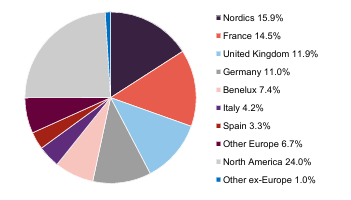
Whilst it remains well-diversified across region and sector, it still shows a strong preference for northern Europe, as well as a preference for less-cyclical businesses such as those in healthcare, technology, consumer stables, and industrials.
Figure 7: Sectoral exposure (%), 31 December 2025
Source: PPET
Figure 8: Geographic exposure (%), 31 December 2025
Source: PPET
At the end of September 2025, the 100 largest underlying companies accounted for 60.3% of PPET’s portfolio. The median valuation multiple (EV/EBITDA) of these companies was 13.7x. The median leverage multiple (debt/EBITDA) was 3.9x. The average revenue growth over the last 12 months was 12.4% and the average EBITDA growth over the same period was 13.1%.
Figure 9: PPET portfolio over the 12 months to 30 September 2025
| Top companies | Portfolio allocation (%) | Median valuation multiple (P/EBITDA) | Median leverage multiple | Average revenue growth (%) | Average EBITDA growth (%) |
|---|---|---|---|---|---|
| 10 | 15.8 | 14.8x | 3.2x | 15.8 | 20.3 |
| 30 | 33.0 | 14.6x | 3.6x | 13.2 | 13.7 |
| 50 | 43.0 | 13.8x | 3.6x | 11.6 | 12.5 |
| 100 | 60.3 | 13.7x | 3.9x | 12.4 | 13.1 |
Source: Patria
Top 10 fund exposures
Changes to fund allocations tend to be driven by realisations, the pace of reinvestment, and the frequency of revaluation by the underlying managers. There are two new names in the top 10 since our last note: Investindustrial VII and Nordic Capital Evolution Fund.
The €3.8bn Investindustrial VII fund launched in 2019 and at the end of September 2025 held 13 companies. It targets mid-market companies within the industrial manufacturing, healthcare and services, and consumer sectors, with a particular focus on Southern Europe. Its largest portfolio companies include crane manufacturer Fassi Group, and Italian food and retail chain Eataly. PPET had an outstanding commitment of £7.1m to the fund at the end of September.
Nordic Capital Evolution Fund raised €1.2bn in 2021 with a focus on mid-market growth companies across northern Europe in sectors such as technology, healthcare, and financial services. At the end of September, it held 11 companies including Swedish multidisciplinary installation group Hjo Installation and fintech Qred. PPET had an outstanding commitment of £4.1m to the fund at the end of September.
Figure 10: 10 largest private equity funds, as at 30 September 2025
| Fund name and vintage | Strategy | Geography | Value 30/09/25£m* | Value 31/03/25£m* | % of NAV 30/09/25 | % of NAV 31/03/25 | NAV change (%) | Net mult.130/09/25 | Net mult.131/03/25 |
|---|---|---|---|---|---|---|---|---|---|
| Altor Fund V (2019) | Nordic Middle Market | Northern Europe | 38.7 | 30.7 | 3.1 | 2.6 | 0.5 | 1.5x | 1.4x |
| Nordic Capital Fund IX (2018) | Complex buyouts global healthcare | Northern Europe | 34.4 | 36.2 | 2.7 | 3.0 | (0.3) | 1.8x | 1.7x |
| Structured Solutions IV Primary Holdings (2021) | Various | Europe & North America | 33.2 | 34.0 | 2.6 | 2.8 | (0.2) | 1.3x | 1.3x |
| Altor Fund IV (2014) | Nordic Middle Market | Northern Europe | 31.8 | 31.2 | 2.5 | 2.6 | (0.1) | 1.7x | 1.7x |
| Triton Fund V (2019) | Mid-market buyouts | Northern & Western Europe | 27.6 | 29.0 | 2.2 | 2.4 | (0.2) | 1.7x | 1.5x |
| PAI Europe VII (2019) | Upper mid-market buyouts | Western Europe | 27.4 | 29.8 | 2.2 | 2.5 | (0.3) | 1.5x | 1.5x |
| American Industrial Partners VII (2019) | Industrials buyout | North America | 26.9 | 25.8 | 2.1 | 2.2 | (0.1) | 1.8x | 1.7x |
| Investindustrial VII (2020) | Industrial buyouts | Southern Europe | 26.9 | 23.5 | 2.1 | 2.0 | 0.1 | 1.6x | 1.6x |
| IK Fund IX (2020) | Mid-market buyouts | Northern Europe | 26.6 | 25.2 | 2.1 | 2.1 | – | 1.3x | 1.2x |
| Nordic Capital Evolution Fund (2021) | Mid-market buyouts | Northern Europe | 26.1 | 21.9 | 2.1 | 1.8 | 0.3 | 1.2x | 1.2x |
| Total of top 10 | 23.7 |
Source: PPET
New fund commitments
Over the six months to end March 2026, PPET made three new fund commitments for a total commitment of €84m, comprising:
- A €25m primary investment into Triton Smaller Mid-Cap III – a Pan-European lower mid-market fund focused on majority buyouts in business services, industrial tech, and healthcare sectors.
- A €42m commitment to Patria CoInvestment Partnership Fund I – a fund focused on European midmarket coinvestments and managed by PPET’s manager Patria. Commitments to the fund are excluded from the calculation of PPET’s management fee to avoid double charging.
- A €17m primary fund commitment to One Peak Growth IV, a Pan-European fund focused on the technology sector.
Other commitments
PPET made a second tranche payment of £7m for the secondary transaction of Project Captain, a diversified portfolio of 13 fund interests and one direct investment.
Underlying holdings
Figure 11 shows PPET’s 10 largest underlying holdings at the end of 2025. Since then, PPET has made the partial sale of its direct investment in Action, generating proceeds of £19.1m, roughly halving its exposure to the discount retailer. PPET’s manager says that it took advantage of a liquidity window (as it also did in 2023) to right-size the investment within its portfolio, rather than selling on company fundamentals.
The manager believes Action’s growth prospects remain strong – despite recent softness in France and Germany and question marks over its expansion into the US – and so has maintained a sizable exposure to participate in future upside. The realisation was achieved at 100% of the 31 December 2025 valuation.
PPET’s underlying holding in another food retailer – Spanish grocer Uvesco – was fully exited through the sale to a Spanish consortium in February.
Figure 11: 10 largest underlying holdings, at 31 December 2025
| Company | Business | Fund | % of NAV 31 Dec 25 | % of NAV31 Mar 25 | % change |
|---|---|---|---|---|---|
| Action | Consumer staples – non-food discount retailer | Co-investment | 3.0 | 2.5 | 0.5 |
| Wundex | Healthcare – home-based treatments | Direct | 2.3 | 1.9 | 0.4 |
| Visma | Technology – enterprise resource planning | Direct | 2.2 | 2.1 | 0.1 |
| Vitrea | Healthcare – rehabilitation | Direct | 1.5 | ||
| Uvesco | Consumer staples – Spanish food retailer | Direct | 1.4 | 1.6 | (0.2) |
| NAMSA | Healthcare – medical device provider | Direct | 1.4 | 1.6 | (0.2) |
| NOBA | Financial – digital consumer bank | Direct | 1.4 | ||
| Trioworld | Industrials – polyethylene film manufacturer | Direct | 1.3 | ||
| CFC Underwriting | Industrials/B2B Services – Insurance software and underwriting | Direct | 1.3 | 1.4 | (0.1) |
| Groupe NGE | Industrials – public works construction | Direct | 1.3 | ||
| Total of top 10 | 17.1 |
Source: PPET
Between the publication of our last note (which used data as at the end of March 2025) and the end of 2025, there were four new entrants into PPET’s top 10 underlying holdings: Vitrea, NOBA, Trioworld and Groupe NGE. These replaced European Camping Group, Froneri, CDL Nuclear Technologies and access.
Vitrea is a leading pan-European rehabilitation provider, serving more than 100,000 patients per year through 75 facilities across Germany, Austria, Switzerland and the Czech Republic.
NOBA is a digital consumer bank operating across the Nordics and parts of Europe. The company focuses on consumer lending, savings products, mortgages, credit cards, and SME financing, with an emphasis on flexible, customer-centric financial services.
Trioworld is one of the leading manufacturers of polyethylene film globally with 18 factories across Sweden, Denmark, France, the UK, the Netherlands, Germany and Canada, as well as three recycling sites in Sweden, Denmark and France. Operations are organised into five reporting divisions: Stretch Film, Industrial Film, Consumer Packaging, Health Care Film, and Carrier Bags.
Groupe NGE is a major French construction and civil engineering group specialising in infrastructure projects. It works across transportation, rail, utilities, energy, telecommunications, and urban development, delivering large-scale public works projects throughout France and internationally.
New direct investments
Over the six months ended 31 March 2026, PPET made three new direct investments, and one follow-on direct investment.
Figure 12: PPET co-investments over the six months to 31 March 2026
| Co-investment name | Investment | Company description |
|---|---|---|
| Omilia | £9.2m | Provides conversational AI solutions for use in customer care settings. Investment alongside Expedition Growth Capital. |
| AlphaPet | €7.0m | German-based digital platform for premium pet food in Europe. Investment alongside Capiton. |
| Bluu Unit | €5.0m | German heating, ventilation and air conditioning (HVAC) business that installs and maintains commercial HVAC systems. Investment alongside Triton Partners. |
| Boost.AI (follow-on investment) | £0.3m | Specialist in conversational AI solutions for an array of different sectors. Investment alongside Nordic Capital. |
Source: PPET
Omilia is a conversational AI and customer experience (CX) technology company that specialises in voice AI, chat automation, and intelligent customer service platforms. Its platform helps large enterprises to automate contact centre interactions using natural language understanding, speech recognition, and voice biometrics, and is widely used in banking, insurance, telecom, healthcare, and quick-service restaurants. Clients include Capital One, Taco Bell, Nissan, and Vodafone. Taco Bell uses Omilia’s technology to automate drive-thru ordering. It has proved successful – speeding up the process during busy times and upselling during quieter periods. It has been rolled out to around 900 stores in the US, with 90% of orders at top-performing locations completed without human intervention. The average order value has reportedly increased by 5-10% through AI upselling.
Drawdowns and distributions
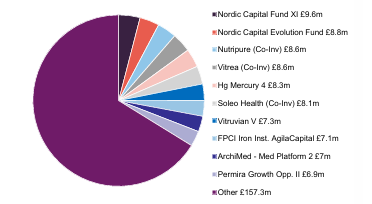
Figure 13: Drawdowns by source, 12 months to 30 September 2025
Source: PPET
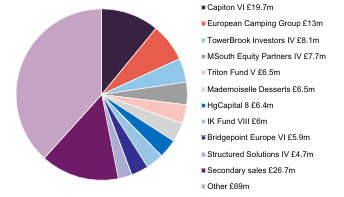
Figure 14: Distributions and secondary sales, 12 months to 30 September 2025
Source: PPET
Drawdowns since September 2025
Figures 13 and 14 show the drawdowns and distributions for PPET over the 12 months to end September 2025, as detailed in its annual report. In the six months to the end of March 2026, PPET received £107.6m in distributions and had drawdowns totalling £96.3m.
Notable realisations over the six months included exits of:
- GTreasury, a provider of comprehensive treasury management solutions, by Hg Mercury 4;
- Froneri, a leading global ice cream manufacturer, by PAI Strategic Partnerships; and
- Ahlsell, a leading Nordic distributor of installation products, tools and supplies, by CVC Capital Partners VII.
Notable drawdowns in the period included:
- Nordic Capital XI, to fund a follow-on investment into TradingHUB, a provider of trade surveillance technology that enables financial institutions to detect market abuse and manipulation;
- Investindustrial Growth III, to fund a new investment in Virospack, a leading global manufacturer of premium cosmetics droppers, serving all major global brands in the cosmetics industry;
- Investindustrial VIII, to fund investment into Piovan, a global leader in the design, manufacture and installation of systems that automate the storage, transport and processing of polymers, plastic powders, and food ingredients; and
- Archimed III, to fund an investment in Dermapharm, a Danish producer of hypoallergenic, environmentally friendly skincare and haircare products sold under its own brands and as private label solutions for third parties.
Commitment levels
As is illustrated in Figure 15, as of 31 March 2026, PPET had total outstanding commitments of £836.0m (although Patria estimates that £82.3m of this will never be drawn down). Balanced against that, PPET had short-term resources (cash balances, deferred consideration, and undrawn credit facilities) of £277.6m at the end of March 2026. PPET was using £140.2m of its £400m RCF at the end of March 2026, and had cash of £17.8m.
This equates to an over-commitment ratio of 44.0% (this being the value of PPET’s outstanding commitments that were in excess of its liquid assets, as a percentage of net assets). This figure has increased over time, but is comfortably within the manager’s target range of 30% to 65%, giving the team more than enough flexibility to make new commitments.
Figure 15: PPET outstanding commitments
| Date | Outstanding commitments (£m) | Outstanding commitments in excess of undrawn loan facility and resources available for investment as a % of NAV |
|---|---|---|
| September 2023 | 650.0 | 35.3 |
| September 2024 | 665.0 | 37.7 |
| September 2025 | 761.0 | 38.2 |
| March 2026 | 836.0 | 44.0 |
Source: Patria
Performance
PPET’s estimated NAV per share was 864.9p and total NAV of £1,269.5m as at 31 March 2026. Earnings growth of the underlying companies in the portfolio, both organic and inorganic, is the primary driver of PPET’s long-term NAV returns.
PPET’s five-year NAV performance continues to be well ahead of the MSCI Europe Small Cap and LPX Europe indices (the LPX Europe is an index of listed private equity companies in Europe, and its returns reflect the share price returns of those companies, rather than returns based on their NAVs).
We think this reflects the strength of PPET’s investment process and manager selection. More than 70% of its underlying primary funds fall within the top or second quartile by TVPI and IRR. The average exit uplift across PPET’s portfolio compares well to the wider market at 41% in 2021, 20% in 2022, 18% in 2023, 26% in 2024 and 12% in 2025 compared to 12%, 3%, 2%, 1% and 2% respectively for global buyout deals.
Figure 16: Cumulative total return performance over periods ending 31 May 20261
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| PPET NAV | 4.8 | 5.5 | 12.5 | 22.4 | 68.5 |
| MSCI Europe Small Cap | 1.7 | 10.5 | 18.3 | 47.1 | 28.9 |
| PPET price | 1.0 | 1.7 | 10.5 | 54.1 | 57.9 |
| LPX Europe | (1.6) | (6.5) | (3.8) | 9.2 | (14.0) |
Source: Bloomberg, Marten & Co. Note: 1) All returns in sterling equivalent terms
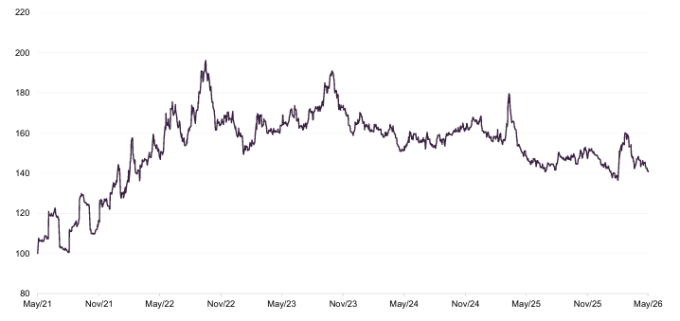
As can be seen in Figure 16, PPET’s NAV returns has lagged the MSCI Europe Small Cap Index over three years to 31 May 2026. However, PPET’s share price has risen significantly, increasing by 54.1% over the same period, having capitalised on the rebound in listed European equities from a low point after the selloff in listed equities in 2022. PPET’s NAV returns – which were not impacted by the selloff and thus had no low point to rebound from – did not.
Figure 17: PPET NAV relative to the MSCI Europe Small Cap over five years to 31 May 2026
Source: Bloomberg, Marten & Co
Peer group
PPET is a member of the AIC’s private equity sector, which comprises 17 members. For the purpose of this analysis, we have narrowed down the wider peer group to the 10 companies illustrated in Figure 18.
3i Group is among those excluded, as it considers itself to be an asset manager and has investment interests extending beyond private equity. We have also excluded EPE Special Opportunities, JPEL Private Equity, JZ Capital Partners, LMS Capital, and Seed Innovations Limited on size grounds, making them less-relevant comparators. In addition, JPEL Private Equity and Symphony International Holdings are in wind-down mode.
PPET’s NAV total returns over the past 12 months are by far the highest in the peer group, following some notable exits (as mentioned earlier). Longer-term performance has also remained above the average, as per Figure 18, reflecting the success of its highly diversified approach to private equity investing.
PPET can boast one of the highest dividend yields in the sector and the lowest ongoing charges ratio. In our opinion, all of these trusts are trading on discounts that are too wide.
Figure 18: AIC private equity sector comparison table, as at 19 June 2026
| Market cap (£m) | Premium/ (discount) (%) | Dividend yield (%) | Ongoing charge (%) | NAV TR1-year (%) | NAV TR 3-years (%) | NAV TR5-years (%) | NAV TR 10-years(%) | |
|---|---|---|---|---|---|---|---|---|
| PPET | 889 | (29.1) | 3.0 | 1.08 | 13.3 | 7.6 | 11.3 | 13.8 |
| CT Private Equity | 353 | (28.8) | 5.7 | 1.20 | 5.1 | 4.0 | 12.0 | 13.1 |
| HarbourVest Global PE | 2,357 | (23.1) | 0.0 | 2.17 | 6.7 | 4.6 | 10.2 | 14.0 |
| HgCapital | 1,810 | (25.9) | 1.3 | 1.50 | 1.1 | 5.3 | 10.8 | 16.2 |
| ICG Enterprise | 849 | (31.9) | 2.8 | 1.39 | 3.6 | 4.2 | 9.8 | 12.8 |
| Literacy Capital | 183 | (36.6) | 0.0 | 2.21 | (4.1) | 1.7 | 25.5 | – |
| NB Private Equity | 612 | (27.7) | 5.0 | 1.88 | 4.3 | 1.5 | 5.8 | 10.8 |
| Oakley Capital | 805 | (32.0) | 0.9 | 3.13 | 7.9 | 5.0 | 14.3 | 15.5 |
| Pantheon International | 1,587 | (22.5) | 0.0 | 1.35 | 3.1 | 4.2 | 8.2 | 11.4 |
| Partners Group Private Equity | 500 | (27.8) | 8.2 | 1.81 | (7.4) | (0.8) | 0.8 | 8.0 |
| Sector median | 849 | (28.8) | 1.3 | 1.50 | 4.3 | 4.2 | 10.8 | 13.5 |
| PPET rank | 4/10 | 7/10 | 4/10 | 1/10 | 1/10 | 1/10 | 4/10 | 4/9 |
Source: QuotedData webiste
Dividend
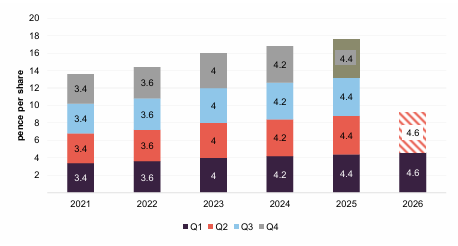
Dividend of 4.6p per quarter represents a 4.5% increase in the quarterly dividend rate year-on-year
PPET paid a total dividend of 17.6p per share for the year to 30 September 2025, which represented a 4.8% increase on the previous financial year. The trust has said that the expected dividend for FY27 is 18.4p, which is being paid in quarterly amounts of 4.6p. The shaded bar in Figure 19 represents the likely Q2 payment which would be made in July 2026.
PPET is one of the AIC’s “next generation dividend heroes”, having grown its dividend every year for more than 10 consecutive years.
Figure 19: PPET’s dividend history over financial years ending 30 September
Source: PPET
Premium/(discount)
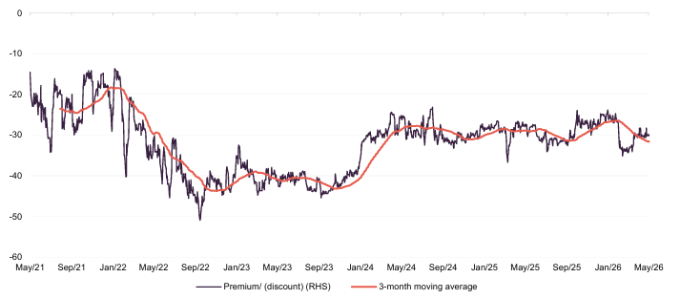
PPET’s discount has averaged 29.4% over 12 months
Over the 12 months ended 31 May 2026, PPET’s discount moved within a range of 23.8% to 35.1% and averaged 29.4%. As at 19 June 2026, the discount was 29.7%.
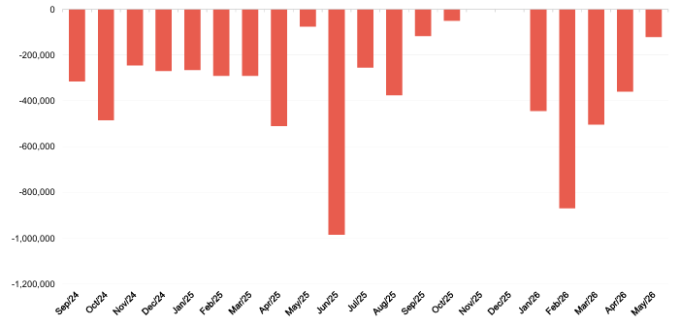
PPET’s discount does appear to have stabilised since Q1 2024. In part, this reflects the trust’s share buyback activity, which is shown in Figure 21. The discount remains stubbornly wide, however. When the exit market picks up and NAVs rise, it seems likely that PPET and the rest of the sector will be re-rated.
Figure 20: PPET premium/(discount) over five years ended 31 May 2026
Source: Bloomberg, Marten & Co
Figure 21: PPET share buybacks by month
Source: PPET
Fees and costs
PPET’s investment management agreement does not include a performance fee
Under the terms of its investment management agreement with Patria, PPET pays a base management fee of 0.95% per annum of its total net assets. The investment management agreement does not include a performance-fee element and is terminable on 12 months’ notice from either side.
The total investment management fee for the year ended 30 September 2025 was £11.1m (2024: £11.4m), and the ongoing charges ratio (OCR) was 1.08%, slightly above the previous year.
GPMS Corporate Secretary Limited, a subsidiary of Patria, provides company secretarial services to PPET, while IQ EQ Administration Services (UK) Ltd provides administrative services. The fees for both are adjusted annually in line with the retail price index. The secretarial agreement and administrative agreement can be terminated by either side on six months’ and three months’ notice respectively.
Capital structure and life
Simple capital structure with one class of ordinary shares
PPET has a simple capital structure with one class of ordinary share in issue. Its ordinary shares have a premium main market listing on the London Stock Exchange and, as of 19 June 2026, there were 146,255,166 shares in issue with 7,491,128 held in treasury.
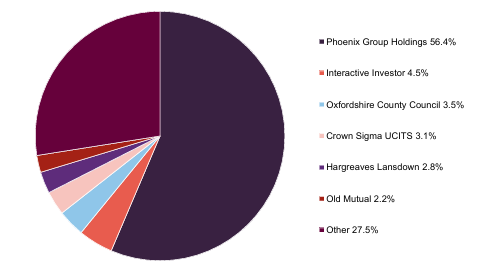
One shareholder, Phoenix Group Holdings, owns over 50% of PPET’s shares. However, under an agreement between it and the trust, it has agreed not to seek to exercise its vote, nor take actions that would prevent PPET from carrying on an independent business, effectively protecting the interests of minority shareholders.
Unlimited life
Arguably reflecting the longer-term nature of its underlying investments, PPET has been established with an indefinite life and there is no specific mechanism, such as a regular continuation vote, to wind up the company.
Major shareholders
Figure 22: Major shareholders as at 19 June 2026
Source: Bloomberg, Marten & Co
Gearing
The loan facility has been increased to £400m
PPET operates with a multicurrency syndicated revolving credit facility worth up to £400m, expiring in February 2028 (with options to extend for up to a further two years). The interest rate on the facility is calculated as the defined reference rate of the currency drawn plus 2.6% and the commitment fee payable on non-utilisation is 0.8% or 0.9% per annum, depending on utilisation. An annual fee of 0.35% is also payable.
PPET has plenty of credit available to fund future investments
The facility is provided by RBS International, Société Générale, State Street Bank International, State Street Bank & Trust Company and Banco Santander. PPET’s articles of association permit it to borrow up to 100% of net assets, although the board has said that it does not expect bank borrowings to exceed 30% of net assets.
PPET had £259.8m remaining undrawn on its £400m revolving credit facility as at 31 March 2026, along with £17.8m in cash. As of 31 December 2025, PPET had a net gearing level of 9.6%.
PPET’s board has agreed that the over-commitment ratio (outstanding commitments less resources available for investment and available debt facility/NAV) should sit within the range of 30% to 65% over the long term. PPET had an over-commitment ratio of 44.0% as of 31 March 2026.
Financial calendar
PPET’s financial year-end is 30 September. The most recent annual results were released in January, while interim results are typically released in June. The most recent AGM was held on 25 March 2026. PPET usually pays dividends in January, April, July, and October of each year.
Management
The lead manager, Alan Gauld, is a senior investment director in the private equity team at Patria. Alan is supported by Patrick Knechtli (head of secondary investments), Mark Nicolson (head of primary investments), Simon Tyszko (senior portfolio director), and Ramone Moody (investment manager). Backup is provided by the rest of Patria’s private equity team (which has more than 30 private equity investment professionals).
Alan has a strong network and extensive experience with leading private equity funds, particularly pan-European and French, Nordic, and Iberian GPs. He is involved in sourcing, appraising, and executing investments as well as portfolio monitoring. Alan is a qualified chartered accountant and holds a BSc (Hons) in Genetics from the University of Edinburgh.
Board
PPET’s board comprises five directors, all of which are non-executive and considered to be independent of the investment manager (details of their individual experience are provided below).
Duncan Budge was appointed chair of the board at PPET’s AGM in March this year, taking over from Alan Devine, who retired from the board after almost 12 years of service.
Figure 23: Board member – length of service and shareholdings
| Director | Position | Date of appointment | Length of service (years) | Annual fee (GBP) | Shareholding1 | Years of fee invested2 |
|---|---|---|---|---|---|---|
| Duncan Budge | Chair | 1 February 2025 | 1.3 | 84,460 | 15,041 | 1.1 |
| Calum Thomas | Audit committee chair and senior independent director | 30 November 2017 | 8.4 | 60,770 | 13,700 | 1.4 |
| Dugald Agble | Director | 1 September 2021 | 4.8 | 53,560 | 17,221 | 2.0 |
| Diane Seymour-Williams | Director | 7 June 2017 | 8.9 | 53,560 | 31,500 | 3.6 |
| Yvonne Stillhart | Director | 1 September 2021 | 4.8 | 53,560 | 13,718 | 1.6 |
| Average (service length, annual fee, shareholding, years of fee invested) | 5.6 | 61,182 | 18,236 | 1.9 |
Source: Patria, Marten & Co. Note 1) shareholdings as per most recent company announcements as at 29 April 2026. 2) Years of fee invested based on PPET’s ordinary share price of 608.00p as at 19 June 2026.
Duncan Budge (chair)
Duncan was an executive director and chief operating officer of RIT Capital Partners Plc between 1995 until his retirement in 2011. He has extensive board experience and is currently a non-executive director of Lowland Investment Company Plc, Biopharma Credit Plc and Asset Value Investors Ltd. He was until recently chair of Artemis Alpha Trust Plc and Dunedin Enterprise Investment Trust Plc.
Calum Thomson (senior independent director and chair of the audit committee)
Calum is a qualified accountant with over 25 years of experience in the financial services industry. He was with Deloitte LLP since October 1988, and for 21 of those years prior to his retirement, he was a senior audit partner in the firm. Calum is a non-executive director and the audit committee chair of the Diverse Income Trust, the AVI Global Trust Plc and Baring Emerging EMEA Opportunities Plc. He is also a non-executive director and audit committee chair of BLME Holdings Limited and Bank of London and The Middle East Plc.
Dugald Agble (independent director)
Dugald was appointed on 1 September 2021. He holds a PhD in Chemical Engineering from Imperial College London and has over 20 years’ direct investment experience in private equity. He started his career at Nomura Principal Finance Group, which later evolved into Terra Firma Capital Partners. More recently, Dugald has been involved in investing in emerging and frontier markets at Helios Investment Partners and 8 Miles. He is a supervisory board member at FMO, the Dutch finance institution.
Diane Seymour-Williams (independent director)
Diane worked for Deutsche Asset Management Group (previously Morgan Grenfell) for 23 years from 1981 until 2005, during which time she held various senior positions, including CIO of Asian Equities, CEO of the Asian asset management business, head of European client relationships and head of global equity product. Diane then spent nine years from 2007-16 at LGM Investments, a specialist global emerging markets manager, where she was global head of relationship management. She is a non-executive director of Baillie Gifford China Growth Trust Plc and Brooks Macdonald Group Plc, where she has also chaired the remuneration committee since 2012. Diane is also a pro-bono member of the investment committees of Newnham College, Cambridge and the Canal & River Trust.
Yvonne Stillhart (independent director)
Yvonne was appointed on 1 September 2021. She was a co-founding senior partner and member of the Investment Committee of Akina AG, a Swiss-based specialised private equity manager which merged in 2017 with Unigestion S.A. Yvonne has over 30 years’ senior executive experience in business building, transformational leadership, private equity and infrastructure investment, finance, banking and risk and investment management across a broad range of industries and geographical regions.
Yvonne serves currently as a non-executive director and member of the Audit and Risk committee at UBS Asset Management Switzerland Ltd., and is both chairperson and member of the Social and Ethics committee of the South African EPE Capital Ltd. She holds a Director Certificate from Harvard Business School and the ESG Competent Boards Certificate. She is fluent in German, English, Spanish and French.
SWOT and bull vs. bear analysis
Figure 24: SWOT analysis
| Strengths | Weaknesses |
|---|---|
| Good long-term performance track record | Weaker shorter-term returns could undermine the buy case for PPET and the asset class |
| Experienced and well-resourced investment team | Relatively high exposure to software companies that are perceived to be under threat from AI |
| PPET’s progressive dividend policy should be attractive to income-seeking investors | |
| Opportunities | Threats |
| Heightened uncertainty leads to lower entry valuations and the prospect of outsized future returns | The threat of AI to the software sector proves founded, to the detriment of valuations |
| The exit landscape remains challenged for an extended period of time |
Source: Marten & Co
Figure 25: Bull versus bear case
| Bull | Bear | |
|---|---|---|
| Performance | The exit market conditions improve and the meaningful valuation discounts that listed European mid- and small-cap stocks trade on versus US peers will be reflected in PPET’s valuations | The macro environment does not improve, and realisations continue to be scarce. Software valuations fall further on AI advancements |
| Dividends | PPET has increased its dividend target for FY26 by 4.5% and has grown it every year for more than 10 consecutive years | Severe market conditions may impact dividend payout, although the board is committed to maintaining the value of the dividend in real terms going forward |
| Outlook | Any progress in the macro environment – an end to the war in the Middle East, for example – could be the trigger for a switch to more positive sentiment. PPET could experience a “double whammy” of rising NAV and a narrowing discount | A prolonged difficult exit environment could undermine confidence in private equity |
| Discount | Discounts on almost all investment companies focused on private equity are too wide, and PPET is no exception to this. This is an opportunity to be highlighted | Wide discounts have been stubborn and prone to periods of widening during “risk-off” environments |
Source: Marten & Co
Previous publications
QuotedData has published a number of notes on PPET. You can read these by clicking the links in the table below or by visiting our website.
Figure 26: QuotedData’s previously published notes on PPET
| Title | Note type | Date |
|---|---|---|
| Sitting in a sweet spot | Initiation | 10 May 2016 |
| Reinvestment phase underway | Update | 14 September 2016 |
| Dividend doubled to 4.0% | Update | 22 February 2017 |
| Loading the portfolio | Update | 3 July 2017 |
| A good year; more to come? | Update | 8 December 2017 |
| Putting capital to work | Annual overview | 17 July 2018 |
| Now with direct investments | Update | 29 May 2019 |
| Share price out of sync? | Update | 15 July 2020 |
| Proving its mettle | Annual overview | 16 September 2021 |
| Laying the foundations for future returns | Update | 8 September 2022 |
| Unrecognised success | Annual overview | 8 September 2023 |
| On the way to greener pastures | Update | 10 April 2024 |
| Long-term success – near-term opportunity | Annual overview | 24 February 2025 |
| Difficult conditions make for better vintages | Update | 24 October 2025 |
Source: Marten & Co
IMPORTANT INFORMATION
This marketing communication has been prepared for Patria Private Equity Trust Plc by Marten & Co, which is authorised and regulated by the Financial Conduct Authority (FCA). It constitutes non-independent research as defined under the UK MiFID II regime and the onshored Commission Delegated Regulation (EU) 2017/565.
This communication is intended for use by investment professionals as defined in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005. Marten & Co is not authorised to provide advice to retail clients. Accordingly, if you are not a professional investor, or are otherwise restricted from receiving this information, you should disregard it. The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it.
The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.