
Cheap and cheerful
After a couple of years where the global financials sector has been outperforming global equities, the managers of Polar Capital Global Financials Trust (PCFT) remain just as upbeat about the outlook for the sector as they were last May, when we last wrote on the trust.
The managers observe that this is a sector that many investors neglect or underweight. However, even after the recent run of good returns, financials trade on the lowest valuations relative to other sectors and are still experiencing improving returns on equity. Many investors have consciously or passively (by holding index-tracking ETFs, for example) made a big bet on technology and are growing more nervous about the valuations in that area. It seems reasonable to us that investor sentiment may turn more favourably towards financials as a way to diversify.
Growing income and capital from financials stocks
PCFT seeks to deliver income and capital growth by finding the best investment opportunities across the world of financials (which includes banks, life and non-life insurance companies, asset managers, stock exchanges, speciality lenders, and fintech companies, as well as property and other related sub-sectors). A new enhanced dividend policy aims to pay out a quarterly dividend equivalent to approximately 4% of NAV each year.
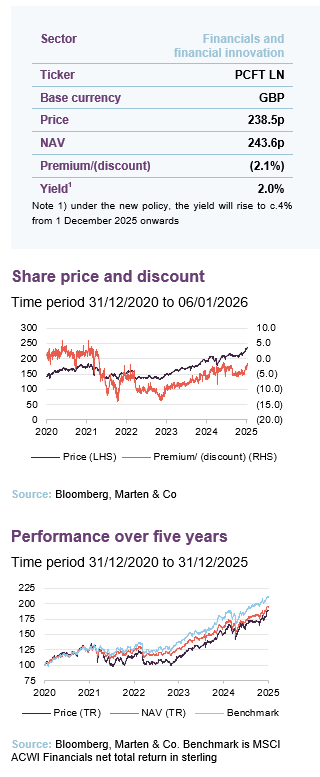
| Year ended | Share price total return (%) | NAV total return (%) | MSCI ACWI Financials TR (%) | MSCI ACWI total return(%) |
|---|---|---|---|---|
| 31/12/2021 | 25.4 | 24.2 | 25.4 | 19.6 |
| 31/12/2022 | (9.3) | (0.5) | 0.9 | (8.7) |
| 31/12/2023 | 0.8 | 3.7 | 9.5 | 15.8 |
| 31/12/2024 | 31.8 | 25.5 | 26.7 | 19.8 |
| 31/12/2025 | 24.7 | 20.7 | 19.7 | 13.9 |
Source: Bloomberg, Marten & Co
Fund profile
PCFT looks to grow investors’ income and their capital
More information on the trust is available on its website www.pcgft.com
Polar Capital Global Financials Trust (PCFT) has twin objectives of growing both investors’ income and their capital. Its global mandate makes it a useful alternative for UK-based investors looking to increase and diversify their financials exposure.
PCFT launched on 1 July 2013 with a fixed life. In April 2020, in conjunction with a vote on prolonging the life of the trust, shareholders were offered a cash exit. Shareholders overwhelmingly approved an extension of the trust’s life beyond May 2020. Then in June 2025, PCFT offered a 100% tender offer (holders of 56.17% of the shares stuck with the trust). These tender offers are held five-yearly, with the next planned for 2030.
Predominantly, the portfolio is invested in listed/quoted securities. The trust’s performance benchmark is the MSCI All-Countries World Financials Net Total Return Index in sterling (MSCI ACWI Financials).
PCFT’s AIFM is Polar Capital LLP, which had AUM of £28.4bn at 7 November 2025 and employs 13 investment teams, spread across offices in Europe, the US and Asia. PCFT’s lead managers are Nick Brind, George Barrow, and Tom Dorner.
Managers’ view – strong returns yet low valuations
ROE on a rising trend for financials
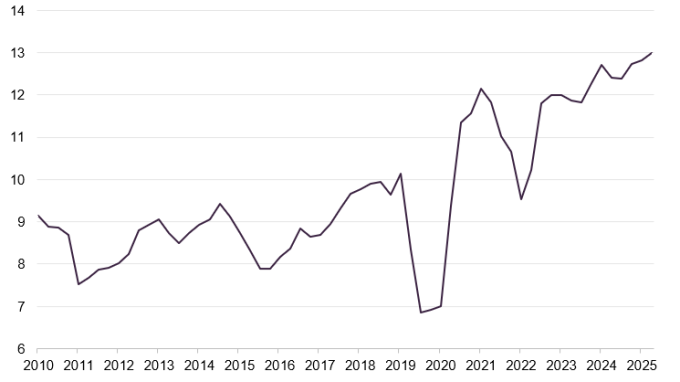
Since the global financial crisis (GFC), the sector has gradually rebuilt its returns on equity (ROE), as Figure 1 shows. The impact of COVID is clear, but much of that dent related to provisions that did not translate into losses. One factor that was holding back returns was low interest rates. When these began to climb from 2022 onwards, banks’ net interest margins expanded.
Figure 1: MSCI ACWI Financials ROE
Source: Bloomberg
The strict capital discipline imposed on the sector in the wake of the financial crisis also weighed on its ROE. However, there is now pushback against any further tightening of regulation and, at the same time, buybacks are proliferating, which are supportive of ROE growth.
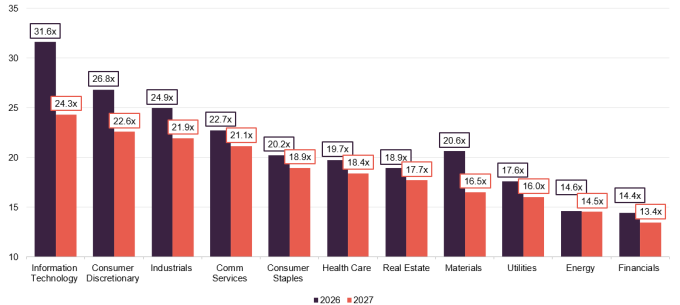
Figure 2: MSCI ACWI sector price/earnings ratios
Source: Bloomberg
PCFT’s managers tell us that they are about as bullish on the sector’s prospects as they have been for a long while. However, even though profits are rising, this does not show up in the ratings of financial stocks, as is illustrated in Figure 2. One implication might be that having been burnt in the GFC, investors are still sceptical about the sector.
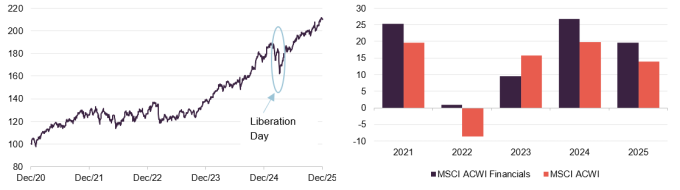
Figure 3: MSCI ACWI Financials
Figure 4: Financials versus global equities
Source: Bloomberg
Source: Bloomberg
Tariffs, which are applied to products rather than services, have no direct impact on financials’ profitability but still dented share prices in the sector, as Figure 3 shows. However, whilst financials bounced back fairly quickly following “Liberation Day”, they have not kept pace in recent months with a market that is still being driven by US mega-cap AI plays.
Financials should benefit from AI
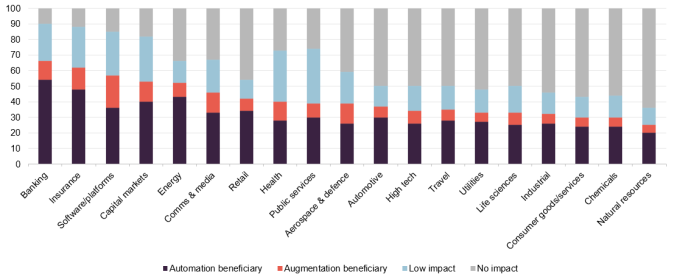
The managers point out that this looks odd when you consider that financials are potentially amongst the biggest beneficiaries of AI, which is already helping cut costs and improve profitability in many companies. Figure 5 shows the findings of some research by Accenture Research into the effects of AI on various industries.
Figure 5: Estimated AI impact by industry
Source: Accenture Research
For the most part, Q3 figures were good, although there were pockets of less-good numbers in areas such as property and casualty insurance, for example. The high profits that the insurance subsector has been generating are attracting more capital to the sector. The managers see greater upside in life assurance companies and have adjusted PCFT’s portfolio accordingly, adding to AIA, Prudential, and Globe Life, for example.
Earlier this year, PCFT profited from a well-timed switch from US banks towards European banks. The managers observe that a push for greater deregulation is taking hold in both the US and Europe, which should help profitability and – in the case of banks – permit an uptick in lending, which has been constrained for some time. Despite delivering strong share price gains, Europe’s banks still look inexpensive, trading on a forward P/E of 9.5x and a price to book ratio of 1.3x at the end of November 2025.
Deregulation is becoming a reality
In the UK, the Bank of England announced that banks had passed its stress tests and minimum tier 1 capital requirement was being cut from 14% to 13%. In addition, the latest budget did not include new taxes on banks, as had been feared. Meanwhile, in the US, a recent report published by consultants Alvarez and Marsal suggested that deregulation in that market could free up $2.6trn of capacity for lending and capital markets activity.
M&A activity has been picking up again and the managers feel that for the most part this seems sensible; there have not been too many cross-border or large-cap deals. The managers cite recent transactions in the US banking sector where banks have been acquired for 1.7x book (Fifth Third Bank paid $11bn for Comerica Bank, and Huntington Bank paid $7bn to buy Cadence Bank).
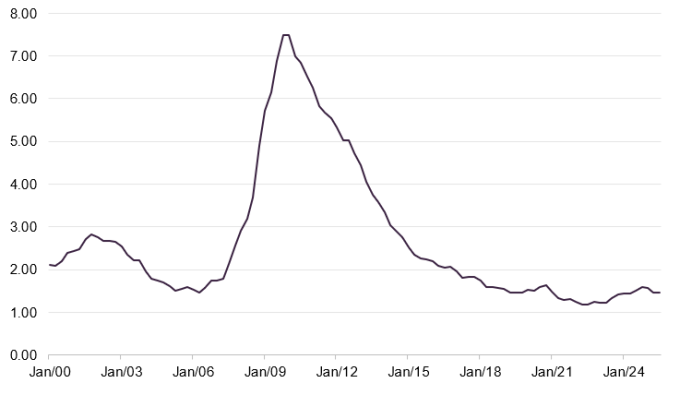
Interest rates are falling, but not, the managers think, to the point where they will be eating into interest rate margins once again. Bad debts are still relatively low, with recent well-publicised issues within private credit not showing up in banks’ loan books in a material way. In part, this reflects the constraints on lending that have been in place since the GFC.
Figure 6: Delinquency rate on all loans, US commercial banks
Source: Federal Reserve Bank of St Louis
Notwithstanding recent weakness in pricing, the managers have put a toehold into the crypto and stablecoin market with a small position in Coinbase, taking advantage of the recent weakness in its share price.
There has been a clear trend towards greater equity investing in markets such as the US. There is also a push for this in other markets, including the UK. Platform business flatexDEGIRO, which we wrote about in our last note (see page 11 of that note) has now doubled in price since PCFT made its investment.
Investment process
PCFT’s managers are stock-pickers and geographic and sector allocations are driven by their stock selection decisions. Traditionally the US has been the richest opportunity set for investors helped by the maturity of the industry in that country and fragmentation in the banking market. Over the last year the portfolio has shifted towards Europe and emerging markets where valuations remain compelling.
Emphasis on proprietary research
The managers are actively involved in researching opportunities. Proprietary research is a core part of the investment process. The managers feel that, whilst some of it is useful, external research is too often short-term in focus. They prefer to take a medium- to long-term view. Access to companies’ management is an important part of the process.
The approach seeks to identify stocks with the potential to create strong risk-adjusted returns. An analysis of balance sheet strength plays a part in this.
Focus on limiting the downside
Short-term profitability and rapid top-line growth may mask underlying problems with asset quality. Most financials stocks are very highly geared, and consequently there is a real need to focus on limiting the downside.
The remit is global and includes emerging markets. The universe is about 500 stocks (typically, the smallest stock that the managers would consider for PCFT’s portfolio would have a market cap of around $500m). There are no limits on the exposure of the investment portfolio to either smaller or mid-cap companies, but the majority of the portfolio is invested in companies with a market capitalisation greater than US$5bn.
The managers say that this is a manageable number of stocks for the team to cover. The likes of Goldman Sachs and JPMorgan are complex beasts, but most banks have relatively simple business models. In many areas, pricing is commoditised and so the sector can be quite generic, but research is essential to sort the good from the bad.
The managers use a scoring system to look at a range of variables around risk, growth, and value. These include balance sheet strength; how the company is funded; the composition of the loan book; historical quality of the loan book; and trends in margins. This model provides a framework for further analysis rather than producing a buy list.
The team meets about 400 companies a year
The team meets about 400 companies each year, but a lot of this is double-checking their research findings, talking to both customers and competitors, for example.
For banks and similar companies, any assessment of value is based on a variation of CAPM – using returns on equity and price to book. The managers find that P/E ratios and measures of growth do not work as well.
The sector is not just about balance sheet businesses, however, and it is evolving. The managers use a more earnings-driven, traditional approach to valuing other companies.
Restrictions
The investment manager has discretion to invest up to 10% of the portfolio in debt securities.
PCFT may have a small exposure to unlisted and unquoted companies, but in aggregate, this is not expected to exceed 10% of total assets at the time of investment.
PCFT will not invest more than 10% of total assets, at the time of investment, in other listed closed-ended investment companies and no single investment will normally account for more than 10% of the portfolio at the time of investment.
PCFT may employ levels of borrowing from time to time with the aim of enhancing returns, currently subject to an overall maximum of 20%.
ESG
ESG factors are integrated into the investment process, and the managers believe that they are a critical driver of long-term returns. Governance and risk management has always been an important component of the investment process as it sets the tone, along with culture, for how a business is managed and will perform in a stressed environment. The managers’ proprietary ESG process incorporates both quantitative and qualitative factors, making use of both internal research and data from third-party ESG providers. An ESG overlay is prepared for each company. This focuses on specific governance (risk management, engagement, litigation, strategy) and environmental factors (exposure to fossil fuels, communication, and engagement).
The lowest-rated companies are excluded from the universe of prospective investments, and any company that scores badly on governance is also automatically excluded.
The analysis helps identify matters that will be raised with the companies by the managers. Ongoing monitoring and engagement of companies is central to the team’s approach.
PCFT has an A MSCI ESG rating
As at 30 November 2024, PCFT had an MSCI ESG rating of A, with a weighted average ESG quality score of 6.86 versus 6.96 for PCFT’s benchmark. The trust’s holdings have a low carbon intensity, which to a large extent reflect the nature of the financials sector. The trust has a strong record of voting at meetings of the companies it invests in, and at over a third of them, the fund’s vote was not cast in favour of resolutions put forward at these meetings.
Portfolio – asset allocation
At the end of November 2025, there were 68 positions in PCFT’s portfolio, down from 77 at the end of April 2025 (when we last published). Relative to the benchmark MSCI ACWI Financials Index, PCFT’s active share at 30 November 2025 was 72.9%, up on the figure at end April.
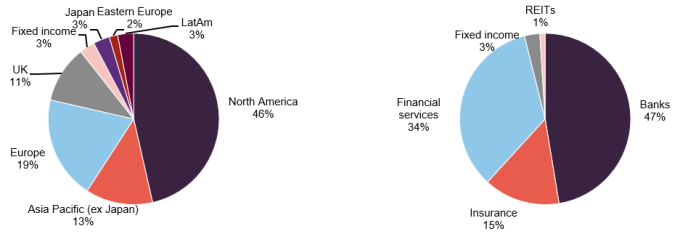
Figure 7: PCFT geographic exposure as at 30 November 2025
Figure 8: PCFT sector exposure as at 30 November 2025
Source: Polar Capital Global Financials Trust
Source: Polar Capital Global Financials Trust
There has been a big shift in PCFT’s geographic asset allocation since we last published (using data as at the end of April 2025). Exposure to North America has fallen from 51.6% to 46.4%. That money has been redeployed mostly to Europe, where the allocation has risen from 12.3% to 19.4%, and to a lesser extent Asia, where the allocation has risen from 10.6% to 12.7%.
On a sector basis, the shift has been to increase exposure to banks at the expense of financial services.
Top 10 holdings
Since we last published (using data as at end April 2025), Berkshire Hathaway, UniCredit, Barclays, SwissRe, Intercontinental Exchange, and Progressive have dropped out of the top 10. The replacements were Royal Bank of Canada, BPER Banca, AIA Group, Citigroup, Globe Life, and Erste Group Bank.
Figure 9: Top 10 holdings as at 30 November 2025
| Country/region | Subsector | 30/11/2025 (%) | 30/04/2025 (%) | Change (%) | |
|---|---|---|---|---|---|
| JPMorgan | United States | Banks | 6.9 | 6.2 | 0.7 |
| Mastercard | United States | Financial services (payments) | 4.1 | 4.8 | (0.7) |
| Bank of America | United States | Banks | 3.9 | 3.3 | 0.6 |
| Visa | United States | Financial services (payments) | 2.9 | 3.8 | (0.9) |
| Royal Bank of Canada | Canada | Banks | 2.8 | 1.8 | 1.0 |
| BPER Banca | Italy | Banks | 2.6 | – | 2.6 |
| AIA Group | Hong Kong | Insurance | 2.5 | – | 2.5 |
| Erste Group Bank | Austria | Banks | 2.3 | – | 2.3 |
| Citigroup | United States | Banks | 2.3 | 0.9 | 1.4 |
| Globe Life | United States | Insurance | 2.3 | 1.7 | 0.6 |
| Total | 32.6 |
Source: Polar Capital Global Financials Trust. Note 1) Percentage of gross assets.
Royal Bank of Canada
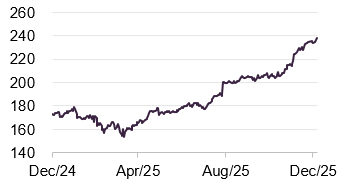
Figure 10: Royal Bank of Canada (CAD)
Source: Bloomberg
Royal Bank of Canada (rbc.com) is the leading Canadian bank, with a strong capital base, and a growing presence in wealth management in the US and UK. It recently published results for the 12 months ending 31 October 2025. Net income and earnings per share (EPS) were up 25% year-on-year.
RBC acquired HSBC Canada in 2025 and is aiming to extract significant cost and revenue synergies from the deal. It highlights its C$5bn annual spend on technology and its plan to use that to extract costs, drive revenue, and enhance its AI capabilities. It is targeting an ROE of 16% by 2027 and annualised EPS growth of 7%. RBC also wants to maintain a dividend payout ratio of about 40%–50%.
BPER Banca
Figure 11: BPER Banca (EUR)
Source: Bloomberg
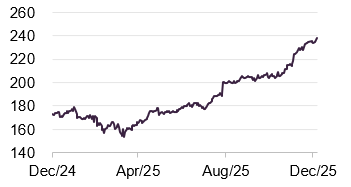
BPER Banca (bper.it) began life as Banca Popolare dell’Emilia Romagna and has grown both organically and by acquisition (most recently with the acquisition of Banca Popolare di Sondrio) to become a €21bn market cap Italian bank. PCFT made a new investment in the bank in July 2025.
Its Q3 figures came in ahead of expectations and showed ROE running at 19.8% and a common equity tier 1 (CET1) capital ratio of 15.1%. Buoyed by the acquisition, YTD net profits to the end of Q3 were €1.5bn up almost 20% when compared to the same period last year (on a like-for-like basis they would have been €1.3bn). Even after this year’s share price rise, the shares trade on less than 10x earnings.
AIA Group
Figure 12: AIA (HKD)
Source: Bloomberg
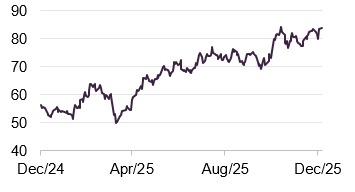
AIA Group (aia.com) was a new addition to the portfolio in June 2025. It is a leading life insurance business in Asia, with total assets of US$328bn at the end of June 2025. It operates in 18 markets across Asia and Australasia. Tata AIA Life, its joint venture in India, is the leading retail life insurer in that market.
Its Q3 figures revealed 25% growth in new business (achieving double-digit growth in 11 of the 18 markets it serves) and higher margins. It is recruiting more agents in China to help drive the expansion of that part of its business.
AIA is targeting CAGR of 9%–11% in its operating profit after tax, per share, between 2023 and 2026 and believes it is on track to achieve this.
Erste Group Bank
Figure 13: Erste Group bank (EUR)
Source: Bloomberg
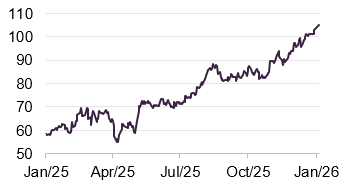
Erste Group Bank (erstegroup.com) was discussed in our December 2024 note (see page 11 of that note), but to recap, it is one of the largest financial services providers in Eastern Europe in terms of clients and total assets.
EPS and return on tangible equity have been growing quarter-on-quarter over 2025. Net interest margins have been fairly stable at around 2.4% and its cost/income ratio has been falling. The bank is seeing growth in both customer loans and deposits. It is also growing AUM within its long-term savings business, helped by the success of its George Invest digital savings platform, which had 11.2m users by the end of Q3 2025. The bank’s balance sheet is strong, with a CET1 ratio of 17.5%.
Citigroup
Figure 14: Citigroup (USD)
Source: Bloomberg
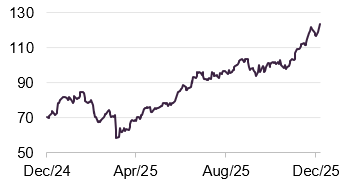
Citigroup (citigroup.com) is one of the world’s largest banks, with a market cap approaching $220bn. It is focusing on improving profitability by simplifying its business, which has meant exiting some markets (including its recent reduction in its stake in Banamex) and simplifying its management structure.
Q3 figures showed a 9% year-on-year uplift in revenue, a 38% increase in adjusted income, and a 48% increase in its EPS. At the end of Q3 2025, its CET1 ratio was 13.2%, about 1.1% higher than its regulatory requirement. It has been returning surplus capital to investors through buybacks and dividends, with the former contributing to the EPS uplift.
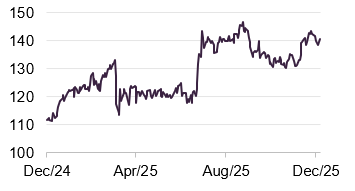
Globe Life
Figure 15: Globe Life (USD)
Source: Bloomberg
Globe Life (globelifeinsurance.com) is a leading US life and health insurance company, distributing its products under the American Income, Liberty National, Family Heritage, and United American brands, as well as a direct-to-consumer business. Based on end Q3 2025 numbers, life insurance accounted for about 69% of its total premium income and health insurance 31%. The life business accounts for an even greater proportion of its insurance underwriting margin, with a split of 82%:18%.
Globe’s Q3 figures showed a 28% increase in net operating income and, helped by share buy backs, a 38% increase in its net operating income per share. The book value per share had grown to $93.63 from $83.92 year-on-year.
Performance
Figure 16 shows the trust’s NAV and share price total returns alongside those of the MSCI All Countries World Financial Index for the five years to the end of December 2025. The drivers of PCFT’s historic performance have been covered in our previous notes, a list of which is provided on page 19.
Having shaken off the impact of the tariff announcements in April, the NAV and share price have been climbing in recent months, roughly in line with the benchmark.
Figure 16: PCFT NAV, share price, and MSCI ACWI Financials five years to 31 December 2025

Source: Bloomberg, Marten & Co
Figure 17: Cumulative total return performance over periods ending 31 December 2025
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| PCFT price | 10.5 | 14.0 | 24.7 | 65.5 | 88.3 |
| PCFT NAV | 6.6 | 12.1 | 20.7 | 57.1 | 94.1 |
| MSCI ACWI Financials | 5.0 | 12.0 | 19.7 | 66.1 | 110.2 |
| MSCI AC World Index | 3.3 | 13.3 | 13.9 | 58.0 | 72.5 |
Source: Bloomberg, Marten & Co
Recent performance attribution
The manager supplied us with some performance attribution data that covers the six-month period to the end of October 2025.
Figure 18: Five largest positive contributions to relative returns six months to 31 October 2025
| Average stock weight (%) | Active weight (%) | Stock return (%) | Total attribution (%) | |
|---|---|---|---|---|
| Alpha Bank | 1.98 | 1.96 | 67.1 | 0.76 |
| Fiserv | Nil | (0.56) | (63.3) | 0.58 |
| Bank of Cyprus Holdings | 1.29 | 1.29 | 60.2 | 0.47 |
| Permanent TSB Group Holdings | 0.68 | 0.68 | 93.2 | 0.43 |
| Interactive Brokers | 1.06 | 0.89 | (58.3) | 0.42 |
Source: Polar Capital Global Financials Trust
Good returns from positions in Alpha Bank, Bank of Cyprus, and Permanent TSB made a positive contribution to returns relative to the performance benchmark, as did underweight/nil positions in two stocks that disappointed – Fiserv and Interactive Brokers.
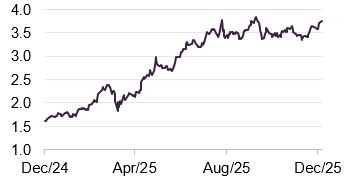
Figure 19: Alpha Bank (EUR)
Source: Bloomberg
Alpha Bank
Alpha Bank (alpha.gr) is a leading financial sector business in Greece and one of PCFT’s larger emerging market positions within its portfolio. Major Italian banking group UniCredit recently upped its stake in Alpha Bank to 29.5%. It has been the largest shareholder since 2023, when it bought the Hellenic Financial Stability Fund’s stake and took control of Alpha Bank’s Romanian subsidiary. The two companies are co-operating to help expand Alpha’s business.
Alpha Bank is targeting 10%+ EPS CAGR over 2024–2027 and believes it is on-track to achieve this, helped by share buybacks.
Figure 20: Five largest negative contributions to relative returns six months to 31 October 2025
| Average stock weight (%) | Active weight (%) | Stock return (%) | Total attribution (%) | |
|---|---|---|---|---|
| Fidelity National Information | 1.54 | 1.28 | (18.6) | (0.56) |
| Robinhood Markets | Nil | (0.47) | 203.8 | (0.48) |
| Intact Financial Corp | 1.41 | 1.16 | (13.6) | (0.37) |
| Axis Capital | 1.72 | 1.72 | (0.3) | (0.37) |
| Intercontinental Exchange | 1.91 | 1.24 | (11.0) | (0.34) |
Source: Polar Capital Global Financials Trust
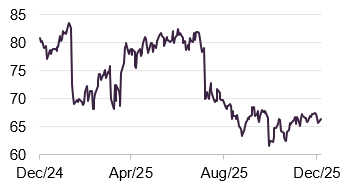
Figure 21: Fidelity National Information (USD)
Source: Bloomberg
Fidelity National Information Services
Fidelity National Information Services (fisglobal.com) saw sharp falls in its share price after publishing its Q2 figures. Investors may have been disappointed that foreign exchange moves seemed to be the main driver of near-term revenue growth. These may have also been read across from disappointing numbers at competitor Fiserv (see above), whose share price slipped this year ahead of a much larger drop on the back of its Q3 figures.
Premium/discount
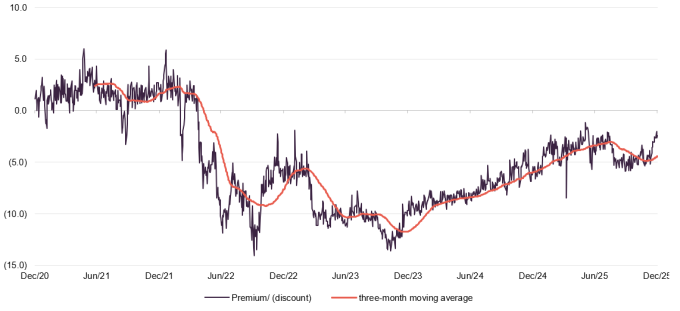
Figure 22: PCFT’s premium/(discount) over the five years to 31 December 2025
Source: Bloomberg, Marten & Co
Over the 12 months ended 31 December 2025, PCFT’s discount moved within a range of 1.2% to 8.5% and averaged 4.0%. At 6 January 2026, PCFT was trading on a discount of 2.1%.
PCFT offers its five-yearly exit opportunities. It also operates a discount control policy whereby if, under normal market conditions: (i) PCFT’s three-month average discount to NAV is greater than 5%, and (ii) the discount to NAV is currently greater than 5%, PCFT will buy back shares with the intention of reducing the discount to NAV to a level of no greater than 5%. We feel that both of these should help keep the discount relatively tight.
Dividend – new enhanced dividend policy
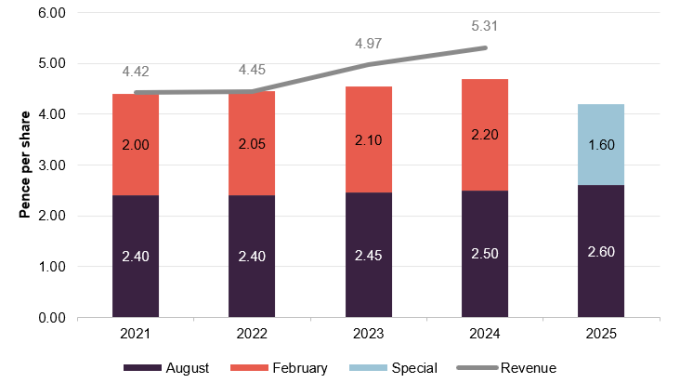
Figure 23: Dividend history – periods ending 30 November
Source: Polar Capital Global Financials Trust
Before its latest exit opportunity, PCFT was following a progressive dividend policy, paying two interim dividends in respect of each financial year in August and February.
Going forward, with effect from the new financial year that commenced on 1 December 2025, PCFT has adopted an enhanced dividend policy under which it will aim to pay, in the absence of unforeseen circumstances, a regular dividend equivalent to approximately 4% of the NAV in a given year. It is proposed that dividends will be paid quarterly at a level of 1% of NAV, calculated on the last business day of each prior financial quarter. The first of these will be announced in March 2026 and paid in April 2026.
Structure
Fees and costs
PCFT’s manager is Polar Capital LLC (Polar). With effect from 1 July 2025, PCFT’s management fees are based on 50% of the NAV (on a cum income basis) and 50% of the lower of market cap and NAV (on a cum income basis), and PCFT pays Polar a base management fee of 0.70% of NAV per annum on the first £500m of this and 0.65% on any balance. The investment management agreement may be terminated by either party giving 12 months’ notice. The base management fee is charged 80% to revenue and 20% to income.
There is no performance fee.
On a historic basis, PCFT’s ongoing running costs work out at 0.85% of NAV.
Capital structure and life
PCFT has a simple capital structure with a single class of ordinary shares in issue and trades on the Main Market of the London Stock Exchange. As at 6 January 2026, there were 162,705,218 ordinary shares with voting rights and a further 169,044,7482 shares held in treasury.
Five-yearly tender offers
PCFT has an unlimited life. The board intends to propose tender offers at five-yearly intervals, the next of which would be in 2030. These would allow any shareholder who wishes to exit the company to do so at a price close to NAV.
Shares bought back as part of the tender offer process and any other shares bought back in the normal course of discount control may be held in treasury and reissued at a premium to asset value.
PCFT’s accounting year end is 30 November and AGMs are usually held in April.
Gearing
PCFT may borrow up to 20% of net assets at the time of drawdown.
At end November 2025, PCFT had net gearing equivalent to 7.1% of NAV.
Management
The five-strong global financials team at Polar Capital LLC was managing £404m, as of end October 2025.
Nick Brind
Nick joined Polar Capital following the acquisition of HIM Capital in September 2010, and is co-manager of PCFT and the Polar Capital Financial Credit Fund. He has 29 years’ investment experience across a wide range of asset classes but since 2003 has focused on global financials. Before joining HIM Capital, Nick worked at New Star Asset Management. While there, he managed the New Star Financial Opportunities Fund, a high-income financials fund investing in the equity and fixed-income securities of European financials companies. Prior to that, he worked at Exeter Asset Management and Capel-Cure Myers. Nick has a Masters in Finance from London Business School.
George Barrow
George has been co-fund manager of PCFT since December 2020. He joined Polar Capital in September 2010 and is also the co-manager of the Polar Capital Financial Opportunities Fund. He has 15 years’ industry experience and over 10 years’ experience analysing Europe, Asia, and emerging markets. Prior to joining Polar Capital, George was an analyst at HIM Capital from 2008, where he completed his IMC. He has a Master’s Degree in International Studies from SOAS, where he graduated with merit.
Tom Dorner
Tom joined the team in December 2023 from Aberdeen, where he was a senior investment director in the developed markets team and managed the Aberdeen Europe ex UK Income Equity Fund. He was responsible for analytical coverage of European financials and managed a number of other European investment funds during his nine years there. Prior to this, Tom was an analyst specialising in the European Insurance sector at Citi and Lehman Brothers in London. He qualified as a Chartered Accountant with Ernst & Young in the Insurance Audit practice and has a BA (Hons) in War Studies from Kings College London, and an MA in Philosophy from the University of Nottingham.
Nabeel Siddiqui
Nabeel joined the Polar Capital Financials team as an analyst in August 2013 working closely with John Yakas and Nick Brind, focusing on the US, Latin America & Australia.
Prior to this, Nabeel worked as an operations executive at Polar Capital. He began his career in August 2008 with Habib Bank, where he worked within a variety of functions. He has a Master’s Degree in Money and Banking and has passed all three levels of the CFA.
Jack Deegan
Jack joined the Polar Capital Financials team as an analyst in October 2017 and is co-manager with Nick Brind on the Financial Credit Fund.
Prior to this, he worked at DBRS Ratings, covering the Swiss market as a lead analyst, as well as UK, Dutch, Japanese and Australian banks. Before DBRS, Jack worked in the Markets Division of the Bank of England for four years, assessing financial institutions with a view to determining access to the Bank’s Sterling Monetary Framework (SMF) facilities, and internal counterparty trading limits. He has a BA in Classical Archaeology & Ancient History from Oxford University and a Master’s Degree in Islamic Politics from SOAS.
Board
The board comprises four non-executive directors, all of whom are independent of the investment manager and who do not sit together on other boards.
Figure 24: Board member – length of service and shareholdings
| Position | Date of appointment | Length of service (years) | Annual director’s fee1 (GBP) | Shareholding1 | |
|---|---|---|---|---|---|
| Simon Cordery | Chair | 1 July 2019 | 6.5 | 46,000 | 42,497 |
| Susie Arnott | Director | 1 December 2022 | 3.1 | 32,500 | 20,000 |
| Angela Henderson | Director | 1 December 2022 | 3.1 | 32,500 | – |
| Cecilia McAnulty | Chair of the audit committee | 1 November 2021 | 4.2 | 38,250 | 40,000 |
Source: Polar Capital Global Financials Trust. Note 1) last available information as at 30 November 2024.
Simon Cordery (chair)
A director since 2019, Simon was appointed chair of PCFT on 30 March 2023. He has over 40 years’ experience working within financial services, of which nearly 30 years have been focused on the wealth management industry. Most recently he was head of Investor Relations and Sales at BMO Global Asset Management, where he spent almost 25 years in senior roles. Previously, Simon held roles with Invesco Fund Managers, Jefferies & Co, Kleinwort Benson Securities and Rea Bros Merchant Bank. He has considerable and detailed knowledge of the investment trust industry and remains actively involved with the AIC. He is a Chartered Fellow of the Chartered Institute for Securities and Investment.
Susie Arnott (non-executive director)
Susie started her career in fund management over 20 years ago. She was primarily focused on the financial sector; including periods focused on emerging markets investments and global financials portfolios. Susie also spent a number of years working in “Impact Investing”, combining her experience and passion for social investment and impact measurement. In her current role, she continues to focus on investment with a global impact incorporating ESG as a mainstream consideration.
Susie is a director of Sableknight Limited and Lockfold Communications.
Angela Henderson (non-executive director)
Angela qualified as a solicitor and initially focused her career on corporate law before moving into financial services, where she spent time as an in-house lawyer and a director of global equities. She invested in and held non-executive board seats at small UK companies in the technology and asset management sectors, and has previously served on the governing body of a London hospital foundation trust. Angela is currently a non-executive director and chair of risk for Macquarie Capital (Europe) Limited, non-executive director and chair of the Management and Service Provider Engagement Committee of Hargreave Hale AIM VCT Plc and Wells Fargo Securities Limited, and has various other private interests.
Cecilia McAnulty (chair of the audit committee)
Cecilia is an experienced non-executive director and Chartered Accountant with almost 30 years’ investment and financial services experience. Her executive career included senior investing roles at Royal Bank of Scotland, Barclays Capital and Centaurus Capital and encompassed a broad range of asset classes including public and private debt and equity.
Cecilia is a non-executive director and audit chair of Northern 2 VCT Plc, and non-executive director of RIT Capital Partners Plc and Eurobank Cyprus Limited.
SWOT/bull versus bear analysis
Figure 25: SWOT analysis for PCFT
| Large, experienced team dedicated to the strategy |
| One-stop-shop for diversified financials exposure |
| Attractive structure with strong discount control measures |
| Five-year performance lags performance benchmark |
| Sector appears to be performing well but stocks are cheap relative to other sectors |
| Regulation is being eased, which should boost profitability |
| Opportunity to cut costs by using AI |
| Interest rates are falling, which could affect sentiment towards sector |
| Risk of rising defaults after an extended period where these have been low |
Source: Marten & Co
Figure 26: Bull vs bear case for CGT
| Performance | Sector is cheap and backdrop supportive | A weaker economy/falling market could bring down the sector with it |
| Dividends | New 4% of NAV distribution policy for income-seeking investors | Dividends will fluctuate with NAV and eat into capital if the NAV falls |
| Outlook | The sector’s prospects look bright | Sentiment still seems to be against the sector and investors nervous – muscle memory of the GFC is still there |
| Discount | Shares have been trading within discount target, loose shareholders exited earlier this year, and buying could drive it down to asset value | No real downside as long as board sticks to discount control policy, and no reason why it shouldn’t |
Source: Marten & Co
Previous publications
QuotedData has published a number of notes on PCFT. You can read these by clicking the links in the table below or by visiting the QuotedData.com website.
| Don’t fear a slowing economy | Initiation | 30 April 2019 |
| Banks too cheap to ignore | Update | 29 October 2019 |
| New lease of life | Update | 22 February 2020 |
| Too much pessimism? | Annual overview | 22 October 2020 |
| The tide has turned | Update | 25 February 2021 |
| More to go for | Annual overview | 18 November 2021 |
| Riding out the storm | Update | 5 April 2022 |
| Don’t fear the dog that is yet to bark | Annual overview | 30 November 2022 |
| Avoiding mishap | Update | 7 June 2023 |
| Pessimism overdone, time to buy | Annual overview | 12 December 2023 |
| Handful of themes to drive performance | Update | 13 June 2024 |
| Taking advantage of a favourable landscape | Annual overview | 12 December 2024 |
| An entry as well as an exit opportunity | Update | 22 May 2025 |
IMPORTANT INFORMATION
This marketing communication has been prepared for Polar Capital Global Financials Trust Plc by Marten & Co (which is authorised and regulated by the Financial Conduct Authority) and is non-independent research as defined under Article 36 of the Commission Delegated Regulation (EU) 2017/565 of 25 April 2016 supplementing the Markets in Financial Instruments Directive (MIFID). It is intended for use by investment professionals as defined in article 19 (5) of the Financial Services Act 2000 (Financial Promotion) Order 2005. Marten & Co is not authorised to give advice to retail clients and, if you are not a professional investor, or in any other way are prohibited or restricted from receiving this information, you should disregard it. The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it.
The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.