
Is there an irrational bias against financials?
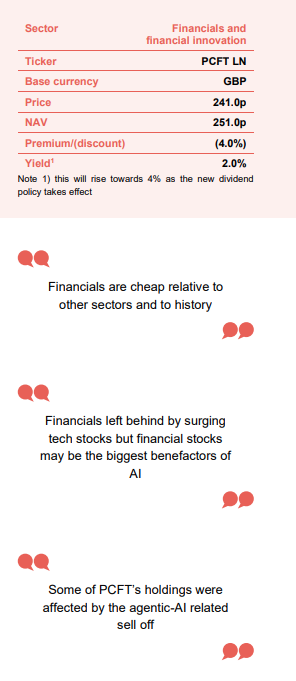
Financials stocks are still undervalued compared to other sectors and their historical averages. Although earlier gains in 2026 have been lost, Polar Capital Global Financials Trust (PCFT) has outperformed this year in NAV terms, thanks to strong stock selection by its managers.
Some PCFT holdings are already showing strong potential to cut costs and boost profits using AI. This adds to the sector’s appeal, as trading conditions normalise and regulations ease. Despite this, many investors still see the sector through the lens of the Global Financial Crisis of nearly 20 years ago. If sentiment changes, there could be a major rerating, and PCFT is well placed to benefit.
Growing income and capital from financials stocks
PCFT aims to deliver income and capital growth by investing in
a wide range of financial companies worldwide, including banks,
insurers, asset managers, stock exchanges, speciality lenders,
fintech firms, property, and related sectors. Its new dividend
policy targets quarterly payments totalling about 4% of NAV
annually.
At a glance
Share price and discount
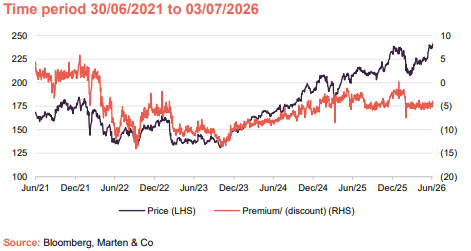
Over the 12 months ended 30 June 2026, PCFT’s share price discount to net asset value (NAV) moved within a range of a 0.2% premium to NAV and a 7.5% discount to NAV. The average was a 4.1% discount.
PCFT offers five-yearly exit opportunities and has a discount control policy that should help keep the discount relatively tight. Ahead of the outbreak of the Iran war, PCFT briefly traded at a premium, although the discount reopened in the more nervous and volatile markets that followed.
Performance over five years
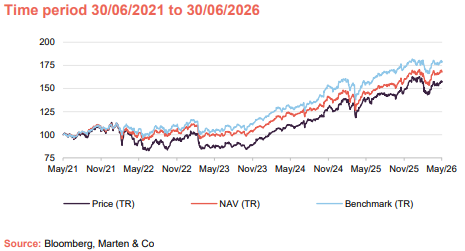
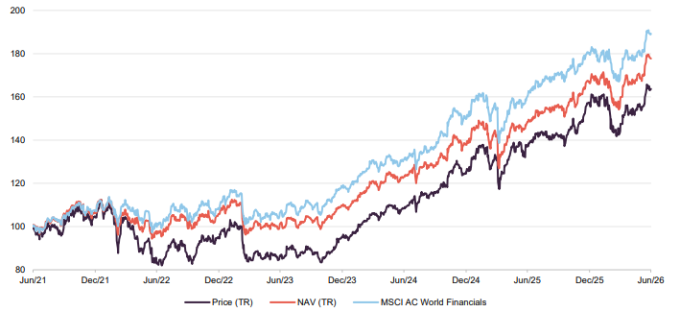
PCFT has delivered strong absolute returns over the five years to 30 June 2026, although it has lagged its benchmark. Its share price total return was 63.7%, while its NAV total return was 77.7%, compared with 89.2% from the MSCI ACWI Financials index.
Recent performance has been stronger. The managers say recent relative returns have been helped mainly by stock selection.
| Year ended | Share price total return (%) | NAV total return (%) | MSCI ACWI Financials total return (%) | MSCI ACWI total return (%) |
|---|---|---|---|---|
| 30/06/2022 | (17.2) | (3.5) | (0.2) | (4.5) |
| 30/06/2023 | 4.3 | 5.1 | 6.8 | 11.6 |
| 30/06/2024 | 25.3 | 21.0 | 22.7 | 20.1 |
| 30/06/2025 | 26.8 | 20.9 | 22.6 | 7.1 |
| 30/06/2026 | 19.3 | 19.8 | 18.0 | 28.0 |
Fund profile
PCFT looks to grow investors’ income and their capital
More information on the trust is available on its website www.pcgft.com
Polar Capital Global Financials Trust (PCFT) aims to grow both income and capital for investors. Its global focus offers UK investors a way to increase and diversify their financials exposure.
PCFT launched on 1 July 2013 with a fixed lifespan. In April 2020, shareholders voted to extend the trust’s life, with a cash exit option. Most chose to stay invested. In June 2025, a 100% tender offer saw 56.17% of shares remain. These five-yearly tender offers will continue, with the next due in 2030.
The trust mainly invests in listed securities and uses the MSCI All-Countries World Financials Net Total Return Index (in sterling) as its benchmark.
PCFT is managed by Polar Capital LLP, which had £30.6bn in assets under management as of 31 March 2026, with 13 investment teams across Europe, the US and Asia. The trust is led by Nick Brind, George Barrow, and Tom Dorner.
Managers’ view
An important sector and a diverse one
PCFT’s managers stress that financials remain a key sector, second only to IT in the global index and highly diversified, with banks making up less than half its value. While investors are focused on US technology, financials were outperforming until the end of 2025, as shown in Figure 1. With no strong fundamental reason for the recent sell-off, managers see good potential for a recovery.
Figure 1: MSCI ACWI Financials versus global equities
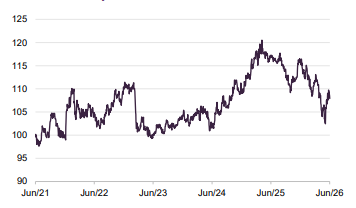
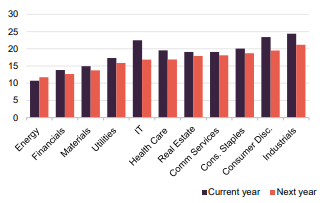
Figure 2: P/E ratios for major global sectors
Financials are cheap relative to other sectors and to history
Financials remain attractively priced compared to other sectors, as shown in Figure 2. Although they are more expensive than in recent years, the post-GFC era was marked by unusually low interest rates and stricter regulation. Lending was limited as banks focused on rebuilding their balance sheets. While this challenging period has passed and the sector’s outlook has improved, financial stocks are still valued much lower than before the global financial crisis.
Figure 3: MSCI ACWI Financials price/earnings ratio over past 20 years
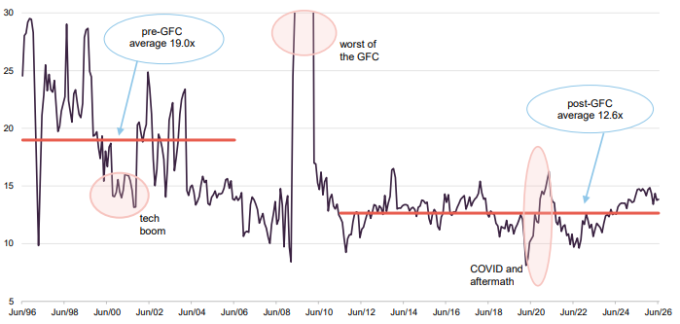
Figure 3 shows the 20-year P/E ratio for the MSCI ACWI Financials Index. Before the global financial crisis began in 2006, financials typically traded at P/E ratios in the mid-teens to low 20s, averaging 19.0x from June 1996 to June 2006. In comparison, the average from June 2011 to June 2026 is 12.6x, making financials look cheap compared to their long-term history.
Even without the impact of the Iran war, inflation and interest rates remain high in many countries, so banks’ net interest margins are unlikely to come under much pressure. As noted previously, default rates are still manageable. While a global recession and rising bad debts are possible, PCFT’s managers do not see this as their main scenario.
Financials & AI – low disruption/big beneficiary?
Another major market driver is AI, especially the ongoing boom in data centre spending and the sharp selloff in stocks seen as at risk from advanced AI earlier this year.
Financials left behind by surging tech stocks…
The financial sector’s low valuation may partly reflect being left out of the surge in IT hardware stocks and the excitement around hyperscalers and LLM creators. A similar pattern was seen during the tech boom, as shown in Figure 3.
…but financial stocks may be the biggest benefactors of AI
In our previous note, we highlighted a chart from Accenture Research showing that banking and insurance could benefit most from AI, with significant potential for cost savings and better services. Figure 4, from PCFT’s latest presentation, instead focuses on which businesses the team sees as most at risk from AI disruption.
Figure 4: Change in P/E versus AI disruption score for stocks in PCFT’s portfolio
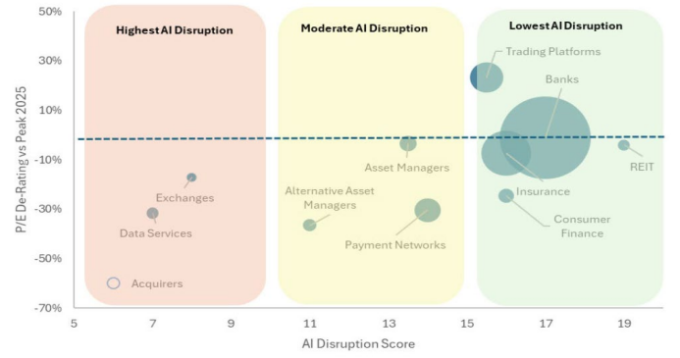
Figure 5: PwC estimate of cost impact on banks that embrace AI transformation
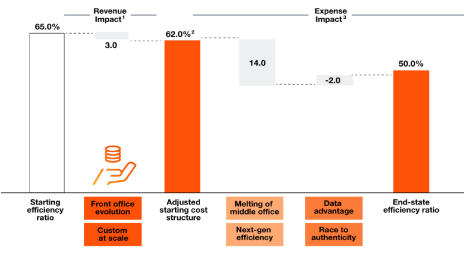
PwC estimates that banks could reduce their efficiency ratio (operating costs as a percentage of revenue) by 15 percentage points, as shown in Figure 5. Evidence for this can be seen with Bank of New York Mellon on page 9.
Some of PCFT’s holdings were affected by the agentic-AI related sell off
Despite these potential benefits from AI, PCFT was affected by a sharp sell-off in stocks seen as vulnerable to agentic AI. This included FlatexDEGIRO, Moody’s, Morgan Stanley, and London Stock Exchange Group. The managers sold the holding in the London Stock Exchange Group before its price recovered after Elliott, an activist investor, took a stake and pushed for changes.
Mastercard and VISA also saw share price declines in the payments sector. Insurance brokers were hit after Spanish company Tuio launched an AI-enabled product, but PCFT had no exposure there. The managers used the drop in Moody’s share price to increase their position in the stock.
It remains uncertain how agentic AI will affect these businesses, and this debate is likely to continue.
Key themes
The managers have highlighted several themes within the portfolio, with percentages showing their weight as of the end of April 2026.
Trading platforms (7%)
Trading platforms have benefited from the increased market volatility seen in 2026, driven by retail investor activity and wider economic events. Stock holdings in this area include Plus500, FlatexDEGIRO, and Interactive Brokers (IBKR). The managers have provided performance data for these platforms during periods of market weakness, shown in Figure 6.
Figure 6: Relative performance during market drawdowns
| Period | S&P 500(%) | MSCI ACWI Finls (%) | IG Group(%) | Plus500(%) | IBKR(%) | Stonex(%) |
|---|---|---|---|---|---|---|
| Sep 18 – Dec 18 | (8.0) | (5.3) | (7.0) | 2.4 | 5.3 | (15.6) |
| Feb 20 – Mar 20 | (33.8) | (41.3) | 23.1 | 50.4 | 4.6 | 1.7 |
| Jan 22 – Oct 22 | (24.3) | (20.8) | 19.2 | 57.3 | 10.5 | 37.0 |
| Jul 23 – Oct 23 | (9.9) | (10.3) | 2.7 | 9.1 | 1.1 | 10.4 |
| Feb 25 – Apr 25 | (18.9) | (12.2) | 10.1 | 20.7 | (24.5) | (2.2) |
Source: PCFT via Bloomberg
European banks (18%)
The portfolio favours European banks due to their lower valuations. Holdings include Santander, BPER Banca, Alpha Bank, and UniCredit. The managers note that European banks trade at an average 34% discount to the wider market, compared to a 15% discount before the financial crisis.
They also point out that European banks, insurance firms, and diversified financials are among the few sectors with positive earnings forecasts.
Insurance (18%)
The portfolio is weighted towards life insurers like AIA, Prudential, and Globe Life, attracted by growth prospects in Asia. PCFT’s managers have recently reduced holdings in AIA and Prudential.
Hiscox was added to replace Beazley after it received a takeover offer. In May, Hiscox shares rose on rumours of a bid from Intact Financial Corp.
US banks (19%)
Easier regulation is benefiting US banks, and the portfolio includes companies like JPMorgan, Bank of America and BNY Mellon. The managers expect more mergers and acquisitions among US banks, noting that recent deals are being approved faster than before. For example, FirstBank’s acquisition of Southern States Bancshares in March 2025 closed in just three months. The US banking market remains fragmented, with 3,849 domestically chartered commercial banks listed by the Federal Reserve at the end of December 2025.
Emerging markets (14%)
The main reason for investing in emerging markets is the growth potential as local populations become wealthier and use more financial products. PCFT invests in companies like Korea’s Shinhan Bank, Brazil’s Nubank, and Mexico’s Banorte.
Figure 7: Mortgage penetration versus GDP per capita
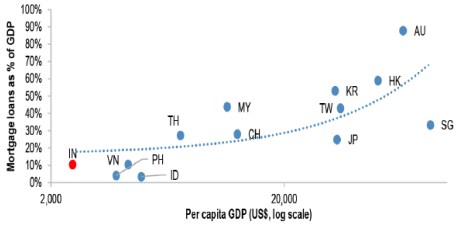
The managers highlight the low use of mortgage products in Asia, especially in India, as shown in Figure 7 (with India in red and Australia for comparison).
Alternative asset managers (now underweight)
Recent headlines have focused on issues in private credit. The portfolio is now underweight in alternative asset managers, but PCFT did hold Blackstone when concerns first emerged. The managers suggest the media may be exaggerating the situation. For example, they note that Partners Group’s gated funds make up only a small part of its assets under management, and the firm still saw net inflows in the first quarter.
Portfolio – asset allocation
At the end of May 2026, PCFT’s portfolio held 69 positions, up by one since November 2025. As of 31 May 2026, PCFT’s active share compared to the MSCI ACWI Financials Index was 68.5%, slightly lower than in November.
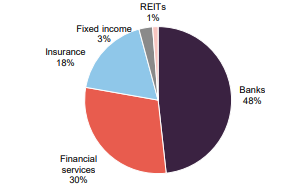
The managers note the portfolio remains well diversified, as shown in Figures 8 and 9.
Figure 8: PCFT geographic exposure as at 31 May 2026
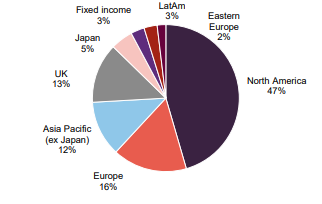
Figure 9: PCFT sector exposure as at 31 May 2026
PCFT’s geographic asset allocation is largely unchanged since our last update (data as of November 2025). European exposure has dropped from 19.4% to 16.4%, with most of these funds moved to the UK, increasing its allocation from 10.8% to 13.2%.
Sector-wise, the fund has increased its holdings in banks and insurance, while reducing its exposure to financial services.
Top 10 holdings
Since our last report at the end of November 2025, BPER Banca, AIA Group, Erste Group Bank, and Globe Life are no longer in the top 10. The replacements were Bank of New York Mellon, Morgan Stanley, IG Group Holdings, and Mizuho Financial.
Figure 10: Top 10 holdings as at 31 May 2026
| Country/region | Subsector | 31/05/2026(%) | 30/11/2025(%) | Change(%) | |
|---|---|---|---|---|---|
| JPMorgan | United States | Banks | 6.4 | 6.9 | (0.5) |
| Bank of America | United States | Banks | 3.8 | 3.9 | (0.1) |
| Royal Bank of Canada | Canada | Banks | 3.1 | 2.8 | 0.3 |
| Bank of New York Mellon | United States | Banks | 3.0 | n/a | n/a |
| Visa | United States | Financial services (payments) | 2.9 | 2.9 | – |
| Citigroup | United States | Banks | 2.8 | 2.3 | 0.5 |
| IG Group Holdings | United Kingdom | Financial services | 2.6 | n/a | n/a |
| Mastercard | United States | Financial services (payments) | 2.4 | 4.1 | (1.7) |
| Morgan Stanley | United States | Banks | 2.3 | n/a | n/a |
| Mizuho Financial | Japan | Banks | 2.3 | n/a | n/a |
| Total | 31.6 |
Source: Polar Capital Global Financials Trust. Note 1) Percentage of gross assets.
Figure 11: Bank of New York Mellon (USD)
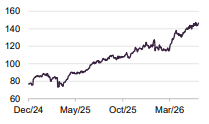
Bank of New York Mellon
Bank of New York Mellon (bny.com) was the 10th-largest US bank by assets at the end of 2025. It is the world’s largest custodian, with over $59 trillion in assets under custody or administration, and is also a leading US asset manager.
In Q1 2026, revenue rose 13% year-on-year while costs increased by only 5%. This led to wider margins, a 3.5 percentage point rise in return on equity to 16.1%, and a 42% increase in earnings per share.
Figure 12: Examples of where BNY is using AI
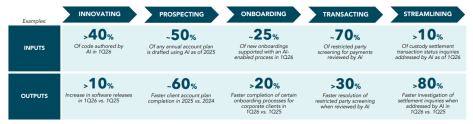
Figure 12 from the bank’s Q1 results highlights examples of how AI is having an impact.
The bank is adopting AI widely, offering training and development to all staff, upgrading its in-house AI platform Eliza (launched in 2024), and working with OpenAI on a multi-year partnership.
Figure 13: Morgan Stanley (USD)
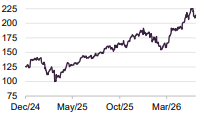
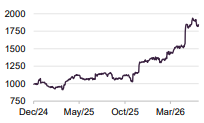
Figure 14: IG Group Holdings (GBp)
Morgan Stanley
Morgan Stanley (morganstanley.com) is an investment bank and wealth manager, with total assets under management of about $9.3 trillion.
In Q1 2026, results were strong and beat analyst expectations. Revenue rose 16%, return on equity increased from 17.4% to 21%, and earnings per share grew 32%, supported by better cost control. The wealth management division had net inflows of $118 billion.
Volatile equity markets following the Iran war boosted trading revenues. Morgan Stanley also played a key role in the SpaceX IPO.
IG Group Holdings
IG Group (iggroup.com) offers trading services to nearly 1.4 million customers, specialising in leveraged derivatives like CfDs (where it is the global leader) and spread-betting in the UK and Ireland. It also provides exchange-traded derivatives in the US through “tastytrade”, as well as stocks, ETFs, forex, crypto, and commodities.
In its May AGM statement for Q1 2026, IG Group reported 19% organic revenue growth year-on-year, driven by more first-time customers. Assets under administration have exceeded £20bn.
The company expects 10%-15% revenue growth for 2026 and aims to maintain EBITDA margins above 40%.
Performance
Figures 15 and 16 compare the trust’s NAV and share price total returns with the MSCI All Countries World Financial Index over the five years to June 2026. The main factors behind PCFT’s past performance are discussed in our earlier reports, listed on page 16.
Figure 15: Cumulative total return performance over periods ending 30 June 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| PCFT price | 13.6 | 4.6 | 19.3 | 89.6 | 63.7 |
| PCFT NAV | 12.3 | 6.9 | 19.8 | 75.3 | 77.7 |
| MSCI ACWI Financials | 10.9 | 5.4 | 18.0 | 77.7 | 89.2 |
| MSCI AC World Index | 14.6 | 12.9 | 28.0 | 64.6 | 75.4 |
Source: Bloomberg, Marten & Co
PCFT’s recent returns have benefited from its larger position in Europe and smaller position in US financials. The managers note that when US stocks rebounded in April, financials did not keep pace with the wider US market.
Figure 16: PCFT NAV, share price, and MSCI ACWI Financials five years to 30 June 2026
However, the main driver of PCFT’s relative returns has been stock selection.
Recent performance attribution
The manager provided performance data for the six months to May 2026, showing that PCFT outperformed its benchmark by 1.7 percentage points during this period.
Figure 17: Five-largest positive contributions to relative returns six months to 31 May 2026
| Average stock weight (%) | Active weight (%) | Stock return (%) | Total attribution (%) | |
|---|---|---|---|---|
| StoneX Group | 1.48 | 1.47 | 84.5 | 1.04 |
| IG Group Holdings | 1.81 | 1.81 | 61.1 | 0.87 |
| Plus500 | 1.58 | 1.58 | 42.6 | 0.51 |
| Bank of New York Mellon | 2.38 | 1.85 | 23.3 | 0.40 |
| Hiscox | 1.03 | 1.03 | 32.7 | 0.31 |
Source: Polar Capital Global Financials Trust
Higher market volatility has boosted trading volumes, as shown in Figure 17, with the top four stocks all benefiting. Hiscox also saw increased activity due to takeover speculation, as mentioned on page 7.
Figure 18: StoneX (USD)
StoneX
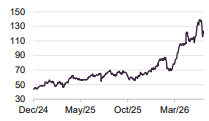
StoneX (stonex.com) serves over 80,000 institutional, commercial, and payments clients, plus more than 400,000 retail investors. It offers 24-hour trading in over 120 global markets. In the 12 months to March 2026, StoneX reported operating revenues above $5.2bn and net income of $462m, up 40% and 57% respectively from the previous year.
Q1 2026 results were much stronger year-on-year, driven by market volatility following the US/Israeli attack on Iran. Revenues from listed derivatives rose 148%, OTC derivatives 98%, and physical contracts 162%.
StoneX plans to expand further in Asia and EMEA.
Figure 19: Five largest negative contributions to relative returns six months to 31 May 2026
| Average stock weight (%) | Active weight (%) | Stock return (%) | Total attribution (%) | |
|---|---|---|---|---|
| Nu Holdings | 1.57 | 1.24 | (25.8) | (0.45) |
| HSBC Holdings | 0.58 | (1.22) | 30.2 | (0.43) |
| Goldman Sachs Group | – | (1.68) | 23.3 | (0.32) |
| S&P Global | 0.82 | (0.07) | (16.1) | (0.30) |
| Toronto-Dominion | – | (1.02) | 35.6 | (0.29) |
Source: Polar Capital Global Financials Trust
Four of the five negative relative contributions came from stocks that PCFT either does not own or holds less of, but which saw strong gains.
Figure 20: Nu Holdings
Nu Holdings
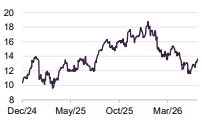
Nu Holdings (investidores.nu) is a Brazilian digital bank listed in the US and owned by PCFT since its founding in 2013. The company has grown rapidly, now serving 135 million customers—almost double the number from three years ago—and has expanded into Colombia and Mexico.
Nu has improved its efficiency ratio, benefiting from AI and not having the branch costs of traditional banks. Revenue per user has risen to $16, up from $12 in Q1 2025, supported by a net interest margin of 21.1% in Q1 2026.
In Brazil, Nu holds 18% of the credit/debit card market, 8% of unsecured loans, and 4% of deposits, while its businesses in Mexico and Colombia are still developing.
The recent share price drop has been linked to the departure of CFO Guilherme Lago and missing analyst forecasts, despite record results. It may also reflect profit-taking and investors moving funds to AI stocks.
Premium/discount
Figure 21: PCFT’s premium/(discount) over the five years to 30 June 2026
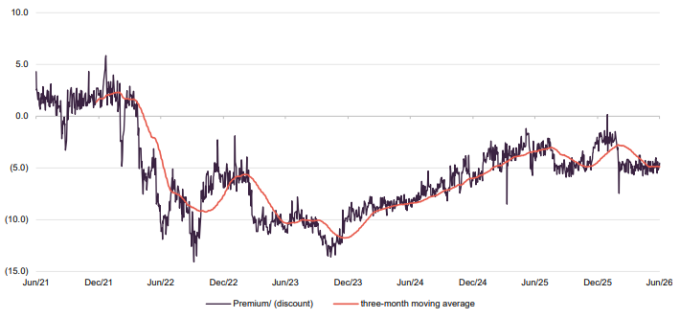
Over the 12 months to 30 June 2026, PCFT’s share price traded between a 0.2% premium and a 7.5% discount to NAV, averaging a 4.1% discount. As of 3 July 2026, the discount was 4.0%.
PCFT provides five-yearly exit opportunities and has a policy to buy back shares if the three-month average discount and current discount to NAV are both over 5%. This aims to keep the discount below 5%. Before the Iran war, PCFT briefly traded at a premium, but the discount returned as markets became more volatile.
Dividend – enhanced dividend policy
Figure 22: Dividend history – periods ending 30 November
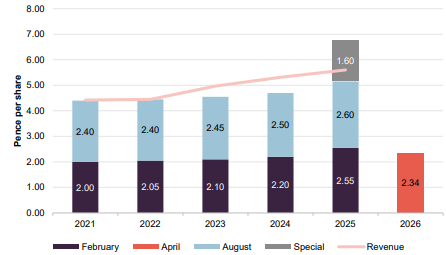
From 1 December 2025, PCFT has introduced a new dividend policy, aiming to pay a regular dividend of about 4% of NAV each year, unless unexpected events occur. Dividends will be paid quarterly at 1% of NAV, based on the value at the end of the previous financial quarter. The first payment was announced in March 2026 and paid in April 2026.
SWOT/bull versus bear analysis
Figure 23: SWOT analysis for PCFT
| Strengths | Weaknesses |
| Large, experienced team dedicated to the strategy | Five-year performance lags performance benchmark |
| One-stop-shop for diversified financials exposure | |
| Attractive structure with strong discount control measures | |
| Opportunities | Threats |
| Sector is cheap relative to other sectors and its long-term history | Risk of rising defaults, if economic conditions weaken, after an extended period where these have been low |
| Regulation is being eased, which should boost profitability | |
| Opportunity to cut costs by using AI |
Source: Marten & Co
Figure 24: Bull versus bear analysis for PCFT
| Bull | Bear | |
| Performance | Sector is cheap and backdrop supportive | A weaker economy/falling market could bring the sector down with it |
| Dividends | New 4% of NAV distribution policy for income-seeking investors | Dividends will fluctuate with NAV and eat into capital if the NAV falls |
| Outlook | The sector’s prospects look bright | Sentiment still seems to be against the sector and investors are nervous – muscle memory of the GFC is still there |
| Discount | Shares have been trading within discount target, loose shareholders exited earlier this year, and buying could drive it down to asset value | No real downside as long as board sticks to discount control policy, and no reason why it shouldn’t |
Source: Marten & Co
Previous publications
QuotedData has published several notes on PCFT. You can access these through the links in the table below or by visiting the QuotedData.com website.
Figure 25: QuotedData’s previously published notes on PCFT
| Don’t fear a slowing economy | Initiation | 30 April 2019 |
| Banks too cheap to ignore | Update | 29 October 2019 |
| New lease of life | Update | 22 February 2020 |
| Too much pessimism? | Annual overview | 22 October 2020 |
| The tide has turned | Update | 25 February 2021 |
| More to go for | Annual overview | 18 November 2021 |
| Riding out the storm | Update | 5 April 2022 |
| Don’t fear the dog that is yet to bark | Annual overview | 30 November 2022 |
| Avoiding mishap | Update | 7 June 2023 |
| Pessimism overdone, time to buy | Annual overview | 12 December 2023 |
| Handful of themes to drive performance | Update | 13 June 2024 |
| Taking advantage of a favourable landscape | Annual overview | 12 December 2024 |
| An entry as well as an exit opportunity | Update | 22 May 2025 |
| Cheap and cheerful | Annual overview | 7 January 2026 |
Source: Marten & Co
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Polar Capital Global Financials Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.