
Ageing well
Temple Bar (TMPL) turned 100 earlier this year. Its one-, three-, and five-year returns are at or near the top end of its peer group, the dividend has continued to climb, and the managers state that they continue to swim against the tide, identifying stocks they consider interesting and attractively valued in a UK equity market that appears to be cheap relative to peers.
The composition of TMPL’s portfolio continues to evolve. The managers are taking profits from financials, adding formerly highly-rated consumer staples stocks, and assessing opportunities in IT services. This cycle of portfolio renewal may provide the foundation for future outperformance.
UK equity income and capital growth
TMPL aims to provide growth in income and capital to achieve a long-term total return greater than its benchmark (the FTSE All-Share Index), through investment primarily in UK securities. The company’s policy is to invest in a broad spread of securities, with the majority typically selected from the FTSE 350 Index.
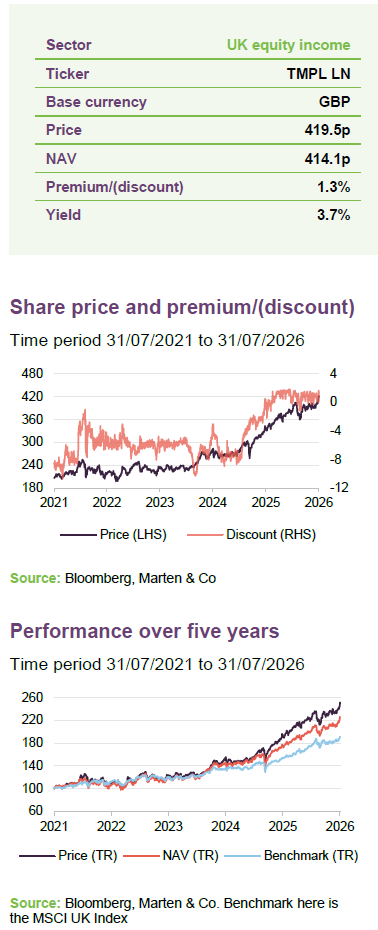
| 12 months ended | Share price TR (%) | NAV total return (%) | MSCI UK TR (%) | MSCI UK Value TR(%) | MSCI World TR (%) |
|---|---|---|---|---|---|
| 31/07/2022 | 9.8 | 6.6 | 12.7 | 17.7 | 3.7 |
| 31/07/2023 | 12.7 | 12.2 | 6.8 | 6.7 | 7.4 |
| 31/07/2024 | 25.4 | 21.6 | 13.5 | 16.7 | 18.5 |
| 31/07/2025 | 22.9 | 19.9 | 12.7 | 15.4 | 12.3 |
| 31/07/2026 | 31.0 | 28.4 | 23.6 | 36.9 | 18.2 |
Fund profile – classic value investing
You can access the trust’s website at: templebarinvestments.co.uk
TMPL aims to provide growth in income and capital to achieve a long-term total return greater than its benchmark (the FTSE All-Share Index), through investment primarily in UK securities. The company’s policy is to invest in a broad spread of securities with most holdings typically drawn from the FTSE 350. The MSCI UK Index has been substituted for the FTSE All-Share in this note.
TMPL’s AIFM is Frostrow Capital LLP, and it has delegated responsibility for portfolio management to RWC Asset Management LLC (Redwheel). Redwheel has been managing the trust since 1 November 2020. The lead managers are Nick Purves and Ian Lance (see page 16).
Looking for a disconnect between share prices and underlying intrinsic value
Their investment approach is based on the principle that investors may overreact to news, becoming overly bullish or overly pessimistic about the prospects for companies and markets. This may create a disconnect between the intrinsic value of a company and its share price, which long-term, value-driven investors may seek to take advantage of as sentiment appears to swing back in their favour.
Avoiding value traps by favouring good quality companies
Care may need to be taken to avoid “value traps” – businesses which look cheap but are in structural decline. Instead, the managers state that they target undervalued but good-quality companies (those with strong cash flows and robust balance sheets). These businesses may be better able to withstand cyclical downturns and recover from short-term, company-specific issues. The approach recognises that aspects of ESG can have an impact on a company’s long-term success.
TMPL has given the managers the flexibility to invest up to 30% of the portfolio in overseas stocks. The chair noted in his most recent statement that the board and manager monitor the size of the investment universe, particularly as the UK market appears to be shrinking through takeovers and a lack of issuance. The board is monitoring the situation with a view, if necessary, to asking shareholders to increase that 30% limit.
Recent data published by Peel Hunt and E&Y highlighted that there were 28 proposed takeovers of UK companies with a total value of £59.7bn over H1 2026, which compares to seven listings raising £577m. However, for the moment, the managers state that they believe they have a large enough opportunity set within the UK to meet the objective.
Value appears to work – just look at the past 100 years
100 years old on 24 June 2026
On 24 June 2026, TMPL was 100 years old. It has operated through the Wall Street Crash, the second World War (and other conflicts since), 70s inflation, 80s recession, the tech boom and bust, the 2008 financial crisis, and COVID and its aftermath. The trust has not always had a value focus – at launch it was “The Cable, Telephone and General Trust” – but while it did not adopt its current name until 1977, it already had a UK equity income focus by then. TMPL’s focus on dividend yield suggests it has a value-investing approach.
At this year’s AGM and in a separate video on the subject, Redwheel discussed the long-term case for value investing.
Figure 1: Out/underperformance of US value by year
| 30s (%) | 40s (%) | 50s (%) | 60s (%) | 70s (%) | 80s (%) | 90s (%) | 00s (%) | 10s (%) | 20s (%) | |
|---|---|---|---|---|---|---|---|---|---|---|
| Year 0 | (21) | (3) | 29 | (12) | 1 | (4) | (22) | 18 | 10 | 16 |
| Year 1 | 13 | 18 | (9) | 4 | 3 | 20 | 14 | 52 | (11) | 34 |
| Year 2 | 94 | 38 | (1) | 4 | (6) | 18 | 40 | 29 | 10 | |
| Year 3 | 135 | 85 | (10) | 8 | (12) | 29 | 25 | 56 | 9 | |
| Year 4 | 9 | 41 | 12 | 9 | 14 | 1 | 6 | 17 | (8) | |
| Year 5 | 16 | 29 | (2) | 31 | 32 | (7) | 0 | 3 | (10) | |
| Year 6 | 38 | (-4) | (5) | 5 | 32 | (3) | 5 | 8 | 19 | |
| Year 7 | (23) | 4 | (9) | 40 | 35 | 1 | 3 | (20) | (7) | |
| Year 8 | 0 | 1 | 25 | 42 | 24 | 8 | (22) | (17) | (15) | |
| Year 9 | 15 | 1 | 3 | (18) | 14 | (14) | 2 | 37 | (13) | |
| Decade (annualised) | 20 | 18 | 3 | 10 | 13 | 4 | 4 | 16 | (2) | 25 |
Figure 2: Long-run cumulative performance from low- and high-yielding stocks in the UK, 1900-2025
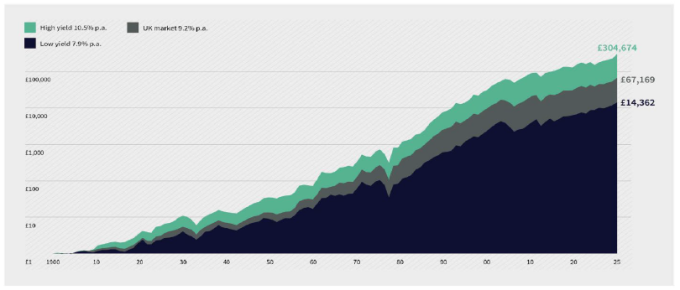
Figure 1 is taken from the video and shows the annual returns of US equities, based on holding stocks that appear cheaper than market averages on a book to price basis (the inverse of price to book, which is perhaps the more common way of presenting this) and shorting the more expensive ones, over the 92 calendar years to the end of 2022. This value approach does not outperform every year, but it is shown as a winning strategy over every decade bar the 2010s, when interest rates were unusually low.
Figure 2 – which is based on the performance of UK value stocks, this time selected on the basis of their dividend yield – appears to reinforce this message. The scale on the y-axis is logarithmic; consistently investing in high-yielding stocks and reinvesting dividends would have made 21x the return of a portfolio focused on low-yielding stocks over that 125-year period.
UK valuation opportunity
As Figure 3 shows, UK equities rose over 2025, but this progress appears to have stalled since the outbreak of war between the US, Israel, and Iran. Concerns about the impact of higher energy costs on inflation appear to have compounded concerns about the fiscal policy of the Labour government, which may have put upward pressure on UK borrowing costs, as illustrated by UK 10-year gilt yields in Figure 4.
Figure 3: MSCI UK

Figure 4: UK 10-year gilt yields

The revolving door at 10 Downing Street may have had some impact on sentiment towards the UK market. However, economically things appear to have been better than some expected. UK GDP growth was 0.6% in Q1 2026 and roughly flat over April and May. UK base rates are unchanged this year. UK inflation, as measured by CPI, came in at 2.6% for the 12 months to the end of June 2026, lower than some had forecasted.
Oil prices rose in March before easing over the next few months as both sides appeared to adopt a more conciliatory tone. That may have weighed on TMPL’s energy stocks, but the managers had taken some profits when share prices rose following the outbreak of the Iran war.
More recently, renewed hostilities appear to have pushed oil and gas prices higher again, with stockpiles dwindling; the situation may now be more serious. EU gas prices are hitting new three-year highs, for example.
Nevertheless, UK equities appear to remain cheap on a range of valuation multiples when compared to peers, as Figure 5 shows.
Figure 5: Valuation multiples across various markets
| P/E (current)(x) | P/E (FY26)(x) | P/E (FY 27) (x) | Price/book (FY26) (x) | EV/EBITDA (FY26) (%) | Dividend yield (FY26) (%) | |
|---|---|---|---|---|---|---|
| MSCI UK | 15.11 | 13.45 | 12.84 | 2.30 | 8.41 | 3.93 |
| MSCI Europe ex UK | 18.37 | 16.96 | 15.42 | 2.41 | 11.59 | 2.94 |
| MSCI AC Asia ex Japan | 19.04 | 12.13 | 9.62 | 2.17 | 9.30 | 2.16 |
| MSCI Japan | 19.79 | 17.56 | 15.60 | 1.87 | 9.10 | 2.12 |
| MSCI USA | 25.87 | 21.59 | 18.87 | 5.13 | 15.37 | 1.14 |
It is often claimed that the reason that UK equities appear cheap is the relative absence of stocks in highly-rated sectors such as information technology. However, as Figure 6 shows, UK stocks are cheaper than global averages in almost every sector.
Figure 6: P/E (FY 26) ratios for UK versus global stocks

A wave of bids for UK companies appears to underscore a view that UK equities may be undervalued. In 2026 we have seen takeover offers for Schroders, easyJet, Rotork, Tate & Lyle, UK Power Networks, Beazley, Intertek, Senior, Mitie, and SEGRO.
Portfolio
At the end of June 2026, there were 40 holdings in TMPL’s portfolio. The average yield on the portfolio at the end of June was 4.1%, which compares to 3.1% for its benchmark. The average current year P/E ratio on the portfolio was 9.7x, which compares to 12.7x for the index and the figures for price/book were 1.2x and 2.0x, respectively.
TMPL’s geographic and sector exposures are driven by the managers’ stock selection decisions and market movements.
Figure 7: TMPL geographic distribution as at 30 June 2026

Figure 8: TMPL change in geographic distribution since 30 November 2025

Since we last published, using data as at 30 November 2025, the portfolio has had more exposure to the US and consumer staples, and less exposure to cash and materials.
Figure 9: TMPL sector distribution as at 30 June 2026

Figure 10: TMPL change in sector distribution since 30 November 2025

Top 10 holdings
Since we last published using data as at 30 November 2025, Barclays and Smith & Nephew have both dropped out of the list of the 10 largest holdings, to be replaced by Marks & Spencer and GSK.
Figure 11: Top 10 equity holdings as at 30 June 2026
| Holding | Sector | % of portfolio 30/06/26 | % of portfolio 30/11/25 | Change (%) | P/E current year (x) | Dividend yield (%) |
|---|---|---|---|---|---|---|
| BT | Communications | 4.6 | 4.0 | 0.6 | 10.8 | 4.3 |
| NatWest | Financials | 4.4 | 4.3 | 0.1 | 9.1 | 4.9 |
| Marks & Spencer | Consumer Staples | 4.4 | 3.4 | 1.0 | 11.3 | 1.1 |
| Shell | Oil & gas | 4.3 | 4.7 | (0.4) | 7.7 | 3.8 |
| BP | Oil & gas | 4.2 | 4.2 | – | 7.2 | 5.3 |
| NN | Financials | 3.9 | 3.9 | – | 9.7 | 5.1 |
| ITV | Communications | 3.8 | 4.0 | (0.2) | 9.4 | 6.2 |
| GSK | Healthcare | 3.7 | 3.5 | 0.2 | 11.2 | 3.4 |
| Johnson Matthey | Materials | 3.7 | 5.1 | (1.4) | 12.3 | 4.1 |
| Aviva | Financials | 3.6 | 3.8 | (0.2) | 10.9 | 6.0 |
| Total of top 10 | 40.6 |
Looking at these and some other stocks in the portfolio:
Marks & Spencer
Figure 12: Marks & Spencer (GBp)

We have discussed Marks & Spencer in our previous notes (see page 19 for a list of these). Its share price has been volatile, but recent performance has moved it back into the list of the 10 largest holdings.
The company’s cyber-attack last year appears to have been addressed, the store refreshment programme appears to be progressing, and the food division appears to be taking share from rivals. TMPL’s managers highlight 4.6% margins on food for the financial year to the end of March 2026 as particularly noteworthy.
TMPL’s managers still see more upside in the share price, which they feel is not yet fully reflecting what they describe as a turnaround in the company.
GSK
GSK has also moved into the top 10 following a recovery in its share price. This is not a fast-growing business, but it is delivering revenue growth of about 3% per annum, which appears to be feeding through into double digit organic earnings growth. TMPL’s managers stated that they felt this positive story was not reflected in its rating.
Figure 13: Barclays price/book (x)

TMPL’s financials exposure appears to have been a driver of its recent returns, and the managers state that they have been taking profits from this area. The managers observe that almost everything appears to have gone right for TMPL’s bank holdings, for example. Even a couple of years ago, these stocks were lowly rated. However, rising interest rates may have opened up net interest margins, costs appear to have been taken out – latterly with the help of AI (the managers state that there may be more to go for on this front), and loan losses appear to have been kept under control.
However, another factor in the re-rating of financials stocks appears to have been the share buybacks that these companies have undertaken, which may be feeding through into their EPS growth.
Diageo and other consumer staples
Figure 14: Diageo (GBp)

One sector that Redwheel has been adding to is consumer staples. The managers state that this is an area that was once a highly rated preserve of growth-style managers, but that a severe de-rating appears to have brought many of these companies into TMPL’s orbit. Stocks in the portfolio include Kraft Heinz, Carrefour, J.M. Smucker, and Diageo.
Diageo’s de-rating has been significant, with the shares more than 60% below their peak. The new CEO, Sir Dave Lewis (ex-Tesco) joined at the start of 2026. According to the managers, one part of his turnaround plan for the company was to halve the dividend, conserving cash to invest in leading brands. The managers also state that he is focused on cutting costs, decentralising the business, refreshing the leadership team, and selling off non-core assets.
Guinness (and Guinness Zero) appears to be delivering sales growth, as is its emerging markets business. However, TMPL’s managers state that they are unsure whether falling spirits sales in North America reflect a structural trend for the drinks industry rather than a stock specific or cyclical issue. That uncertainty is reflected in the position size.
BP
Figure 15: BP (GBp)

BP is another turnaround story in the portfolio. Aside from the impetus given to the stock by the recent oil price increases, the main catalyst appears to have been the shake-up led by its new CEO, Meg O’Neill, who took over on 1 April 2026. Meg was previously CEO of Woodside Petroleum and prior to that spent over 20 years at ExxonMobil. The TMPL managers have met her and state that they were impressed.
TMPL’s managers believe that a key priority will be to unwind the low-return energy transition investments the company made under Bernard Looney (who was the CEO between 2020 and 2023). That process appears to be underway, and disposals may be used to reduce debt. There also appears to be a need to stabilise the company after a run of changes at the top of the company, including the recent dismissal of its chair.
ITV
In September 2020, when we wrote about ITV in our first note on TMPL, we noted that TMPL’s managers stated that all of the company’s market capitalisation could be accounted for by its studios business, and that, in their view, the broadcast business was “in for free”. On 6 July 2026, Sky announced that it would pay up to £1.6bn for ITV’s media and entertainment business. ITV’s share price fell on the day and is currently lower than it was back in September 2020. TMPL’s managers suggest that investors might be unwilling to price in a deal that appears unlikely to complete before H2 2027. In the meantime, it may be that a soon-to-be standalone studios business attracts attention from another bidder; Netflix, for example.
Software and IT services
TMPL has relatively limited exposure to the IT sector currently, but recent falls in the share prices of software and IT stocks have encouraged the managers to take a closer look at some of these companies.
For the moment, the software-as-a-service stocks that have seen sharp share price falls are still considered by TMPL to be too highly-rated to be attractive. However, amongst the IT services stocks, many are now on low double-digit or even single-digit earnings multiples. The analyst team is reviewing some of these names in more detail.
Performance
Figure 16: Total return performance over periods ending 31 July 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| TMPL share price | 8.8 | 11.6 | 31.0 | 101.9 | 149.8 |
| TMPL NAV | 8.5 | 10.8 | 28.4 | 87.2 | 124.0 |
| MSCI UK | 5.2 | 8.5 | 23.6 | 58.1 | 90.3 |
| MSCI UK Value | 8.8 | 13.1 | 36.9 | 84.4 | 131.6 |
| MSCI World | 5.2 | 9.8 | 18.2 | 57.4 | 75.4 |
| Peer group1 NAV median | 7.5 | 8.6 | 19.6 | 49.7 | 61.4 |
| Peer group1 share price median | 8.4 | 8.3 | 21.2 | 44.9 | 64.1 |
TMPL’s three-year and five-year returns remain ahead of its benchmark and, as discussed below, peer group averages.
TMPL’s returns relative to the MSCI UK Value Index may be influenced by the high levels of concentration within that index. At 30 June 2026, HSBC was 19.1% of the index, Shell 12.8%, Unilever 7.7%, and BAT 7.3%, which may limit its usefulness as a comparator. HSBC’s share price is up about 70% over the past 12 months.
TMPL’s recent track record appears to be influenced by its financials exposure, which we discussed on page 9. Redwheel states that contributions to TMPL’s returns have come from stocks such as Standard Chartered, Barclays, NatWest, and Aberdeen Group.
Figure 17: Temple Bar NAV relative to MSCI UK (sterling total return) to 31 July 2026

WPP
Figure 18: WPP (GBp)

The only meaningful detractor from returns has been WPP; however, this is a stock that the managers state has potential. Under Martin Sorrell, WPP was built – through a series of acquisitions – into one of the world’s largest advertising agencies and the leading media buyer. A market cap that peaked at around $30bn is now around $4bn. While other big global advertising agencies have been seeing modest top line growth, WPP has seen like-for-like revenue falls over the past couple of years and that appears to be feeding through into declining EPS. TMPL’s managers state that this suggests WPP’s problems are specific to it rather than a structural issue with the industry.
A new CEO, Cindy Rose (formerly of Microsoft), took on the job in September 2025. TMPL’s managers have met her and believe that she may be able to turn WPP around. They think it may help that she has a background in technology. One issue is that the individual businesses within WPP were not integrated and often ended up competing with each other for the same business. There may be scope to reduce complexity and cost from the business, which could help improve cost control.
It may be sufficient to stabilise the business. The managers state that the market is valuing WPP on about 5x earnings, whereas a rating of 10x may be ascribed to a stable business. If the new CEO can grow earnings on top of this – TMPL’s managers state that organic revenue growth of 3% p.a. over the medium term, with an operating profit margin of 16~17%, appears achievable – then the potential for a rerating may be considerable.
Redwheel is a significant shareholder in WPP, with about 10% of the company held across its range of funds and mandates, and states that it is content to give the new CEO room to deliver on her planned transformation of the company.
Peer group
You can find up-to-date information on TMPL and its peers on our website
TMPL is one of the larger of the 16 funds in the AIC’s UK equity income sector, and its running costs are below the sector median. The shift to an enhanced dividend appears to have moved TMPL’s yield closer to the sector median. TMPL’s long-term track record, which is shown in Figure 19, appears to be reflected in its rating and regular share issuance.
Figure 19: Snapshot of UK equity income sector as at 31 July 2026
| Premium/ (discount) (%) | Yield (%) | Ongoing charges (%) | Market cap (£m) | |
|---|---|---|---|---|
| Temple Bar Investment Trust | 1.3 | 3.7 | 0.59 | 1,283 |
| Aberdeen Equity Income Trust | 1.5 | 5.0 | 0.84 | 367 |
| BlackRock Income and Growth | (13.0) | 3.4 | 1.15 | 42 |
| Chelverton UK Dividend Trust | (6.6) | 7.0 | 2.25 | 32 |
| CT UK Capital and Income | (4.2) | 3.6 | 0.66 | 334 |
| CT UK High Income | (3.2) | 5.1 | 1.03 | 105 |
| Dunedin Income Growth | (7.8) | 6.1 | 0.57 | 368 |
| Edinburgh Investment Trust | (7.6) | 3.8 | 0.52 | 1,057 |
| Finsbury Growth & Income | (6.5) | 2.5 | 0.62 | 805 |
| JPMorgan Claverhouse | (1.4) | 3.7 | 0.62 | 530 |
| Law Debenture Corporation | 1.9 | 2.9 | 0.56 | 1,668 |
| Lowland Investment Company | (9.0) | 3.6 | 0.71 | 400 |
| Murray Income Trust | (6.2) | 4.0 | 0.48 | 952 |
| Schroder Income Growth Fund | (5.7) | 4.0 | 0.78 | 242 |
| The City of London Investment Trust | 2.0 | 3.7 | 0.36 | 3,057 |
| The Merchants Trust | (5.1) | 4.5 | 0.54 | 983 |
| Peer group median | (5.4) | 3.8 | 0.62 | 465 |
| TMPL rank | 4/16 | 10/16 | 7/16 | 3/16 |
TMPL’s long-term track record appears to be good, ranking at the top end of the table over most time periods. This may reflect the success of its value-driven approach. Many trusts appear to have drifted away from value investing over the period when the style was underperforming. Many of those that focused on “quality” instead appear to have been exposed to software stocks caught in the agentic AI sell off earlier this year (most notably Finsbury Growth & Income).
Those that have a bias to small-cap stocks have also tended to lag in recent years.
Figure 20: Total return NAV performance over periods ending 31 July 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| Temple Bar Investment Trust | 8.5 | 10.8 | 28.4 | 87.2 | 124.0 |
| Aberdeen Equity Income Trust | 8.9 | 12.4 | 32.9 | 74.2 | 63.9 |
| BlackRock Income and Growth | 5.6 | 4.0 | 15.3 | 38.6 | 55.0 |
| Chelverton UK Dividend Trust | 7.9 | 7.8 | 10.5 | 25.4 | (7.5) |
| CT UK Capital and Income | 6.2 | 4.9 | 10.2 | 39.1 | 36.8 |
| CT UK High Income | 7.1 | 7.2 | 20.6 | 61.1 | 54.5 |
| Dunedin Income Growth | 7.5 | 7.8 | 12.3 | 27.5 | 33.3 |
| Edinburgh Investment Trust | 7.6 | 7.8 | 10.4 | 41.6 | 68.1 |
| Finsbury Growth & Income | 6.2 | 7.1 | (9.9) | (1.0) | 2.4 |
| JPMorgan Claverhouse | 8.1 | 9.4 | 22.2 | 61.6 | 68.6 |
| Law Debenture Corporation | 6.5 | 10.2 | 24.6 | 70.9 | 93.6 |
| Lowland Investment Company | 9.4 | 10.7 | 29.4 | 73.7 | 77.5 |
| Murray Income Trust | 10.3 | 11.4 | 18.5 | 33.4 | 38.6 |
| Schroder Income Growth Fund | 6.8 | 7.0 | 18.7 | 50.3 | 58.9 |
| The City of London Investment Trust | 7.5 | 10.3 | 24.9 | 70.0 | 92.6 |
| The Merchants Trust | 11.6 | 10.2 | 24.9 | 49.0 | 79.3 |
| Peer group median | 7.5 | 8.6 | 19.6 | 49.7 | 61.4 |
| TMPL rank | 5/16 | 3/16 | 3/16 | 1/16 | 1/16 |
Enhanced dividend
TMPL pays dividends quarterly. Since the AGM in 2025, it has used reserves to top up the dividend that it would have paid from net revenue earnings by an additional 3p per annum (0.75p per quarter). This represents a contribution to payouts that may be intended as an alternative to companies buying back shares rather than maximising their dividend payout ratio. In the last annual report, the chair observed that according to Computershare’s UK Dividend Monitor, share buybacks represented 42.1% of the total distributions by UK listed companies in 2025.
That change in policy appears to be reflected in the step change in the dividend for 2025 over 2024. The chair has cautioned that the pace of TMPL’s dividend growth going forward is unlikely to match the significant increases seen in the past few years.
The dividend target for the current financial year is 15.6p, payable in four instalments of 3.9p. This represents a 4% increase on the dividend for 2025.
Figure 21: TMPL’s recent dividend record

Premium/(discount)
Figure 22: TMPL discount over five years ended 31 July 2026

As investors appeared to become more convinced of TMPL’s ability to outperform over the long term and memories of the extended period of underperformance from value strategies appeared to fade, the shares appeared to re-rate over the course of 2025. Over the 12-month period that ended on 31 July 2026, TMPL’s shares have traded between a discount of 10.7% and a premium of 1.8%, averaging a discount of 4.6%. As of publishing, the company was trading on a premium of 1.3%.
The board states that it is committed to an active policy to manage TMPL’s share price relative to its NAV. That includes both issuing shares at a premium as well as buying back shares at a discount. Both may have the effect of enhancing the NAV for ongoing shareholders. At the AGM on 5 May 2026, shareholders authorised the directors to issue up to 20% and buy back up to 14.99% of the then shares in issue.
Over the past 12 months, due to demand, particularly from retail investors, no shares have been repurchased, and 21.13m shares have been reissued from treasury.
Figure 23: Shares issued and repurchased

Structure
Fees and costs
As AIFM, Frostrow Capital LLP is paid 0.125% of TMPL’s market capitalisation up to £250m and 0.1% of market capitalisation above £250m. As portfolio manager, Redwheel is paid a management fee equal to 0.325% per annum of the company’s total assets. There is no performance fee.
At 31 December 2025, TMPL’s ongoing charges were calculated at 0.59%, compared with 0.61% a year earlier.
Capital structure
At 30 July 2026, TMPL had 334,363,285 shares in issue, of which 28,629,447 were held in treasury. The number of shares with voting rights was 305,734,378.
Based on data published by the company as at 31 December 2025, retail investors owned 50.7% of TMPL’s shares, wealth managers and private banks 34.9%, and institutional investors 13.9%.
Gearing and hedging
TMPL has a £50m 4.05% private placement loan which is repayable on 3 September 2028, and a £25m 2.99% private placement loan which is repayable on 24 October 2047. The two loans are secured by a floating charge over the assets of the company. TMPL’s net gearing was 3.7% as of 31 May 2026.
TMPL does not currently hedge its currency exposure.
Financial calendar
The trust’s year-end is 31 December. The annual results are typically released in March (interims in September), and its AGMs are typically held in May of each year. TMPL pays quarterly dividends in April, June, September, December each year.
Management team
Nick Purves joined Redwheel in August 2010 from Schroders, where he was a senior portfolio manager with responsibility for both Institutional Specialist Value Funds and the Schroder Income Fund and Income Maximiser Fund, together with Ian Lance. He worked at Schroders for 16 years, having moved from KMPG, where he qualified as a chartered accountant.
Ian has over 30 years of experience in fund management and started working with Nick at Schroders in 2007 before joining Redwheel in August 2010. While at Schroders, he was a senior portfolio manager, managing the Institutional Specialist Value Funds, the Schroder Income Fund and Income Maximiser Fund, together with Nick. Previously, Ian was the head of European equities and director of research at Citigroup Asset Management and head of global research at Gartmore.
Board
TMPL’s board comprises five non-executive directors, all of whom are independent of the manager, and who do not sit together on other boards.
Charles Cade was appointed chairman of the board on 2 December 2025, succeeding Richard Wyatt, who stepped down from the board on that date after eight years as a director, including two as chair. Nick Bannerman and Wendy Colquhoun were appointed to the board in the summer of 2025.
Figure 24: Directors
| Role | Appointed | Length of service (years) | Fee | Shareholding | |
|---|---|---|---|---|---|
| Charles Cade | Chairman | 24 March 2022 | 4.3 | 49,000 | 50,000 |
| Shefaly Yogendra | Senior independent director, chair of the nomination committee | 1 October 2019 | 6.8 | 32,000 | 4,500 |
| Carolyn Sims | Chair of the audit and risk committee | 1 January 2023 | 3.5 | 37,000 | – |
| Nick Bannerman | Director | 1 July 2025 | 1.0 | 32,000 | 10,049 |
| Wendy Colquhoun | Chair of the management engagement committee | 1 July 2025 | 1.0 | 32,000 | 5,535 |
Charles Cade
Charles has more than 30 years’ experience in the investment companies sector, and was ranked among the leading analysts throughout his career at Numis Securities, Winterflood Securities, HSBC and Merrill Lynch. He joined the City following an MBA, having previously worked for a consultancy firm and as an economist in the UK government. Charles is currently a non-executive director of Vietnam Enterprise Investments Ltd, a member of the Investment Committee of the Rank Foundation charity, and an independent consultant to interactive investor, the retail platform.
Shefaly Yogendra, PhD
Shefaly was recently the COO of Ditto AI, a symbolic AI startup. She built her career in the technology industry, followed by strategic advisory work on emerging technologies, and specialises in governance, growth, risk, and decision-making. Shefaly is a non-executive director of JPMorgan US Smaller Companies Investment Trust Plc. She was listed among the “100 Women To Watch” in the Female FTSE Board Report 2016.
Carolyn Sims
Carolyn is the CFO and COO of British International Investment plc (BII), the UK’s Development Finance Institution. Before joining BII in 2020, she was CFO of the Wealth Management Division of Schroders Plc and a member of its Group Management Committee. Prior to that, Carolyn was the CFO of Cazenove Capital Management Limited until its sale to Schroders in 2013. She started her career with Touche Ross & Co. where she qualified as a Chartered Accountant. Carolyn then joined Lazard, where her roles included COO for Global Capital Markets and UK finance director.
Nick Bannerman
Nick is a Chartered Accountant and was managing director of a number of Scottish luxury cashmere businesses. He is a non-executive director of JPMorgan China Growth and Income Trust Plc and also of The Global Smaller Companies Trust Plc, where he also acts as chair of its audit committee. Nick was formerly chair of the audit committee and chair of Baillie Gifford Japan Trust Plc.
Wendy Colquhoun
Wendy is a former senior corporate partner at international law firm CMS Cameron McKenna Nabarro Olswang LLP where she specialised in advising financial services companies including investment trusts. Wendy is a non-executive director and the senior independent director of Capital Gearing Trust Plc, Schroder UK Mid-Cap Fund Plc, and Murray International Trust Plc. She was formerly a non-executive director and chair of Henderson Opportunities Trust Plc and a non-executive director of Scottish Financial Enterprise.
Previous publications
Readers interested in further information about TMPL may wish to read our previous notes. You can read the notes by clicking on them in Figure 25 or by visiting our website.
Figure 25: QuotedData’s previously published notes on TMPL
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Temple Bar Investment Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.