
Premium investing
Temple Bar Investment Trust (TMPL), managed by Ian Lance and Nick Purves, outperformed again in 2025, delivering a 33.9% NAV return and a 45.3% share price return, well ahead of both UK and global markets. The shares ended the year at a premium to asset value, which has been unusual in the investment company sector recently, and allowed the fund to sell some previously repurchased shares back into the market.
The managers focus only on investing in companies with clear potential to increase shareholder value. In 2025, a more positive mood towards the UK market, where TMPL has 70% of its assets, helped performance. Ian and Nick still see the UK as undervalued and continue to find companies trading below their real value. They are optimistic that TMPL’s strong performance can continue into 2026 and beyond.
UK equity income and capital growth
TMPL aims to provide growth in income and capital to achieve a long-term total return greater than its benchmark (the FTSE All-Share Index), through investment primarily in UK securities. The company’s policy is to invest in a broad spread of securities, with the majority typically selected from the FTSE 350 Index.
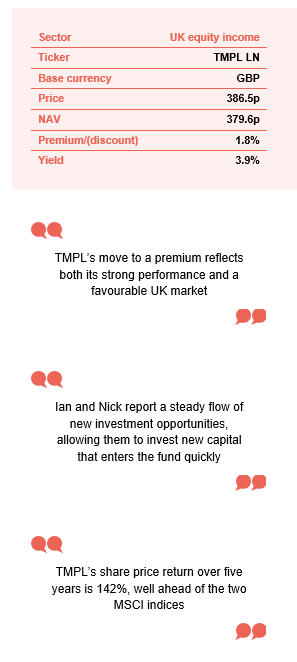
At a glance
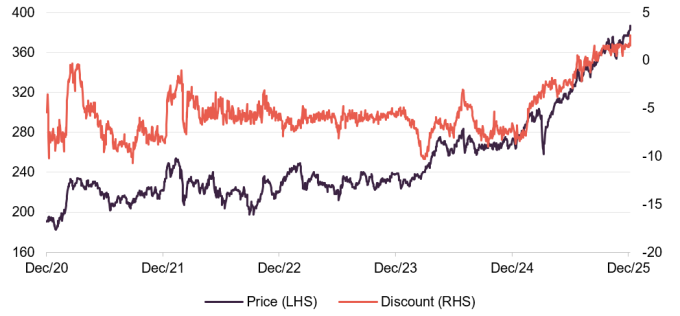
Share price and discount
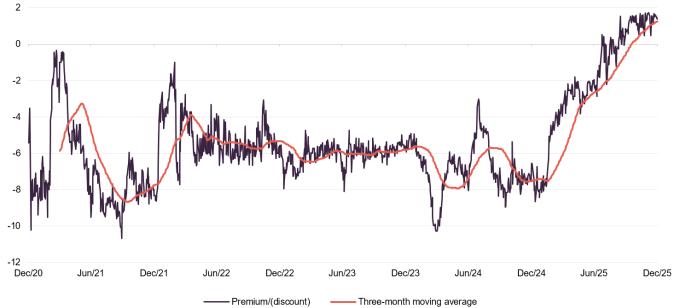
In our last note, we highlighted the narrowing discount at the start of 2025. This has continued, and since the end of September, the shares have consistently traded at a premium. This is positive, especially given the discounts seen elsewhere in the investment companies sector.
Time period 31 December 2020 to 6 January 2026
Source: Bloomberg, Marten & Co
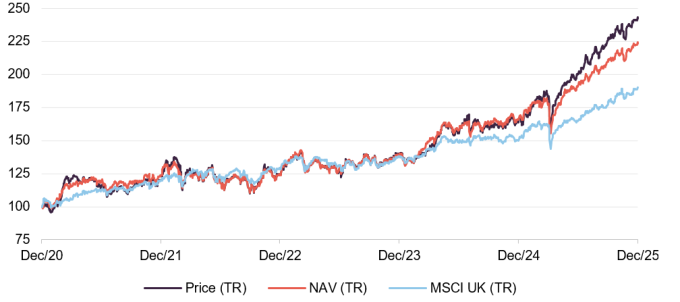
Performance over five years
Redwheel has managed TMPL since October 2020, so the five-year period here reflects their full tenure. During this time, TMPL’s NAV return of 124% has clearly outperformed both the MSCI UK index and the MSCI UK Value sector.
Time period 31 December 2020 to 31 December 2025
Source: Bloomberg, Marten & Co
| 12 months ended | Share price total return (%) | NAV total return (%) | MSCI UK total return (%) | MSCI UK Value total return (%) | MSCI World total return (%) |
|---|---|---|---|---|---|
| 31/12/2021 | 20.0 | 23.5 | 19.6 | 17.7 | 22.9 |
| 31/12/2022 | 3.6 | 0.4 | 7.1 | 14.7 | (8.4) |
| 31/12/2023 | 12.5 | 12.3 | 7.7 | 6.4 | 17.3 |
| 31/12/2024 | 19.1 | 19.9 | 9.5 | 12.5 | 21.0 |
| 31/12/2025 | 45.3 | 33.9 | 25.8 | 32.6 | 12.7 |
Source: Bloomberg, Marten & Co
Market overview
2025 was positive for markets, and performance was more broad-based than in previous years.
Investor sentiment was positive in 2025, with global equities rising strongly. Markets were less focused on one region, as the US technology sector, while still performing well, attracted less attention than in recent years. The UK market, in particular, saw improved sentiment and stronger performance from previously low levels.
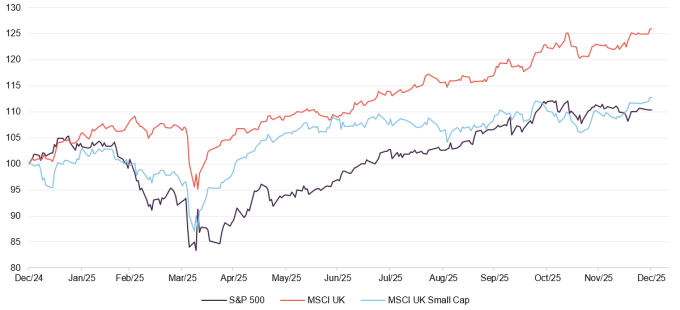
Figure 1 shows that while the S&P 500 rose, the UK market, measured by the MSCI UK Index, did even better. This outperformance included smaller UK stocks, as shown by the MSCI UK Small Cap Index, which narrowly beat the US market. This environment benefited TMPL, as Ian and Nick invest across a wide range of UK companies.
Figure 1: Market performance over 2025, indices rebased to 100
Source: Bloomberg, Marten & Co
The main period of weakness came in April, when equities fell sharply after President Trump’s “Liberation Day” tariff announcements. However, this downturn was brief, with a 90-day tariff pause and ongoing negotiations easing concerns. For the rest of the year, investors largely ignored trade tensions and focused on a healthy corporate sector, supported by stable global inflation and interest rates. Overall, 2025 was a strong and more broadly based year for markets.
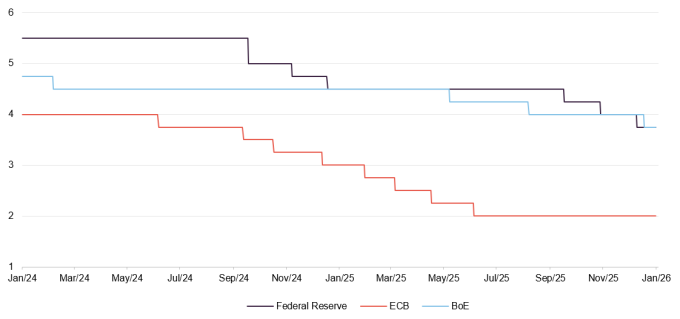
Developed market interest rates have continued to fall.
Figure 2 shows that interest rates in developed markets have steadily fallen over the past two years. Although periods of falling rates can be associated with strong performance for more “growth”-focused investors, in the current relatively benign macroeconomic environment both growth and value investors are generally seeing positive returns. It would be encouraging if we have moved away from the recent period of wild swings between the two styles moving into and out of favour, although the risk of this dynamic reasserting itself clearly remains.
Figure 2: US (Federal Reserve), eurozone (ECB) and UK (BoE) benchmark interest rates since January 2024
Source: Bloomberg, Marten & Co
Current prospects for TMPL
Value stocks perform strongly when corporate profitability is strong.
Currently, corporate profitability is generally strong and therefore value stocks are tending to perform well because their worth relies more on current earnings than on future profits. Strong profits increase cash flow and margins, making the current environment positive for TMPL’s investment approach.
Despite recent gains in UK markets, Ian and Nick believe there is still good value among their chosen stocks and that they are not buying at market highs. The UK market remains much cheaper than other developed countries; for example, the S&P 500 began 2026 with a forward price-to-earnings ratio of 22, compared to 13 for the FTSE 100.
With large-cap stocks in the UK outperforming their small-cap peers in 2025, as shown in Figure 1, it might seem logical for Ian and Nick to move down the market-cap spectrum somewhat in the coming months. However, they have made clear that all investment decisions are made on a stock-specific, bottom-up basis, with a focus on risk and reward, rather than being specifically driven by market-cap considerations.
Portfolio – asset allocation
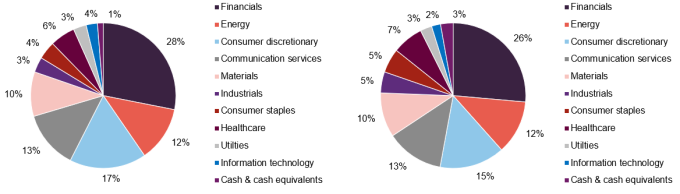
Financials remain the largest sector weight in TMPL’s portfolio.
Financials remain TMPL’s largest sector holding, though the allocation has fallen slightly since our last note (with data as at April 2025). Four of the portfolio’s top 10 positions are financial companies (see page 7). The sector has performed well due to strong profits, low loan losses and healthy interest margins. Many firms have also bought back shares at low prices. The managers believe there is still value in financials, even if falling interest rates may reduce margins.
TMPL’s exposure to consumer discretionary has also decreased, while holdings in industrials, consumer staples and technology have seen small increases.
Figure 3: TMPL sector distribution as at 30 April 2025
Figure 4: TMPL sector distribution as at 30 November 2025
Source: Temple Bar Investment Trust
Source: Temple Bar Investment Trust
The trust mainly invests in UK companies within the FTSE 350 index, keeping non-UK assets below 30%. As of 30 November 2025, 70.3% of the portfolio is in the UK. However, there are notable overseas holdings, including US retailer Macy’s and Korean banks Hana Financial and Woori.
In early 2025, the managers sold Dutch bank ABN AMRO, having nearly doubled the original investment. The proceeds were reinvested in Hana Financial and Woori, keeping funds within the financial sector. Despite weak sentiment and low valuations in Korean banking, the managers saw both banks as well-run, with strong capital and steady loan growth in a growing economy. The Korean market rallied hard from the middle of May onwards on the back of efforts to improve Korean corporate governance, to the benefit of TMPL’s Korean exposure.
Gearing
TMPL’s gearing was 3.0% as at 30 November 2025, down from 5.7% at the time of our last note in May 2025.
Top 10 holdings and recent additions
Figure 5: Top 10 holdings as at 30 November 2025
| Holding | Sector | % of portfolio 30/11/25 | % of portfolio 30/04/25 | Change(%) |
|---|---|---|---|---|
| Johnson Matthey | Materials | 5.1 | 3.5 | 1.6 |
| Shell | Energy | 4.7 | 5.0 | (0.3) |
| NatWest | Financials | 4.3 | 5.0 | (0.7) |
| BP | Energy | 4.2 | 4.0 | 0.2 |
| BT Group | Communications | 4.0 | 3.4 | 0.6 |
| ITV | Communications | 4.0 | 4.7 | (0.7) |
| NN | Financials | 3.9 | 4.8 | (0.9) |
| Aviva | Financials | 3.8 | 4.9 | (1.1) |
| Barclays | Financials | 3.5 | 4.6 | (1.1) |
| Smith & Nephew | Healthcare | 3.5 | 2.1 | 1.4 |
| Total of top 10 | 41.0 | 42.0 | (1.0) |
Source: Temple Bar Investment Trust, Bloomberg
Johnson Matthey has moved from the 10th-largest holding to the top spot after strong recent share price gains. BT Group and Smith & Nephew are now in the top 10, replacing Marks & Spencer and Standard Chartered. BT Group and Smith & Nephew are discussed below, and we also asked the managers for an update on ITV.
Smith & Nephew
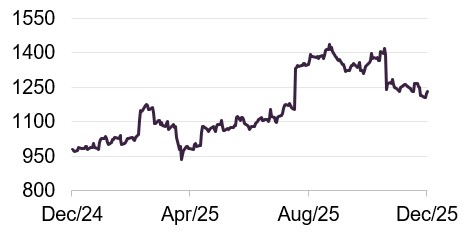
Figure 6: Smith & Nephew (GBp)
Source: Bloomberg
Smith & Nephew (www.smith-nephew.com) is a UK-based global medical technology company focused on orthopaedics, sports medicine, ENT devices, and advanced wound care. Ian and Nick started investing in the company in the second quarter of 2025.
After a period of underperformance, TMPL managers bought shares at about half their previous peak of £20. The company is following a 12-point plan to improve operations, simplify the business, and support long-term growth. This has led to steady revenue growth across its divisions, and improving margins could help the shares recover.
In 2025, Smith & Nephew reported organic revenue growth of about 5%, mainly from strong demand in sports medicine and wound care. Cash generation also improved, and the company completed a US$500m share buyback to return capital to shareholders.
BT Group
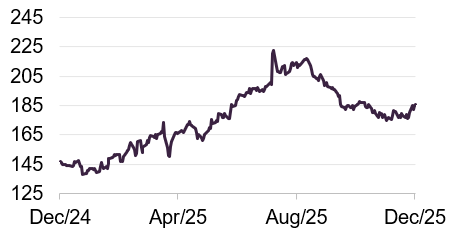
Figure 7: BT Group (GBp)
Source: Bloomberg
BT Group (www.bt.com) is the UK’s largest telecoms provider. TMPL’s investment is mainly based on Openreach, which builds and maintains the UK’s broadband and telephone network. The managers note that BT needs about three out of ten homes connected to sign up as customers to be profitable, a target they are currently meeting. In contrast, alternative networks like CityFibre, Toob and Zzoomm are struggling to reach this level and may face financial difficulties.
BT’s share price has recovered from just over 100p in May 2024 as confidence in Openreach has grown, but Ian and Nick believe the shares remain undervalued. Beyond Openreach, BT is undergoing a strategic transformation led by chief executive Allison Kirkby, focusing on modernisation, simplification, and better customer service. The company is streamlining operations, such as exiting sports broadcasting, and is strengthening its consumer and business divisions. Despite a slight drop in revenue, BT has reported modest growth in core earnings.
ITV
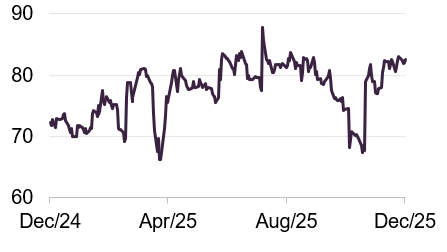
Figure 8: ITV (GBp)
Source: Bloomberg
ITV (www.itvplc.com) is the UK’s largest commercial broadcaster, with two main divisions: ITV Studios, a global production and distribution business, and Media & Entertainment (M&E), which includes broadcasting and the ITVX streaming service.
ITV Studios is the world’s second-largest independent production company and has performed well. Ian and Nick estimate it could be worth over £3bn if sold separately. As ITV’s market value is about the same, this suggests investors get the M&E business, including ITVX, at no extra cost. Broadcasting faces challenges, with fewer people watching traditional TV and high fixed costs. However, ITVX continues to grow its subscriber base and digital advertising, adding value to the group.
Recent press reports suggest Comcast, which owns Sky, has held early talks with ITV about buying its M&E division. While there is no certainty a deal will happen, these reports lifted ITV’s share price at year-end and suggest a potential move to unlock value for shareholders from the M&E business.
Performance
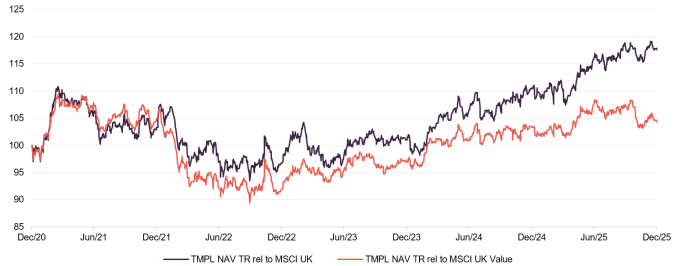
Redwheel has managed TMPL since October 2020, so the five-year period in Figure 9 reflects their full tenure. During this time, TMPL’s NAV return of 124% has clearly outperformed both the MSCI UK index and the MSCI UK Value sector.
Figure 9: Temple Bar NAV relative to MSCI UK and MSCI UK Value (sterling TR) to 31 December 2025
Source: Bloomberg, Marten & Co
Figure 10 shows TMPL’s share price return over five years is 142%, well ahead of the two MSCI indices. Most of this outperformance came in recent years, helped by falling inflation and interest rates, which have benefited UK and value investors.
TMPL’s short-term results are also strong. The one-year share price return is notable, partly due to the narrowing discount. However, this is not solely due to the discount, as the NAV return of 33.9% also beats both indices, driven by strong stock selection.
Figure 10: Total return performance over periods ending 31 December 2025
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| TMPL share price | 7.1 | 21.2 | 45.3 | 94.7 | 142.1 |
| TMPL NAV | 6.6 | 17.2 | 33.9 | 80.3 | 123.5 |
| MSCI UK | 7.1 | 15.4 | 25.8 | 48.3 | 90.0 |
| MSCI UK Value | 9.5 | 20.8 | 32.6 | 58.7 | 114.2 |
Source: Bloomberg, Marten & Co.
Contributor
Johnson Matthey
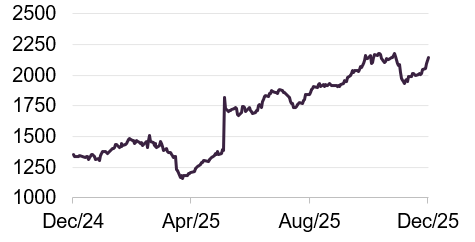
Figure 11: Johnson Matthey (GBp)
Source: Bloomberg
Johnson Matthey (www.matthey.com) is a global speciality chemicals and sustainable technologies company focused on clean air, platinum group metals, catalysts, and hydrogen technologies.
Over the past five years, the shares have underperformed, allowing Ian and Nick to buy at a significant discount to the company’s underlying value. They saw potential for a quick recovery, especially after pressure from activist shareholder Standard Investments, which owns 11% of the company. This prompted the board to take action, contributing to the strong share price in 2025.
In May, Johnson Matthey agreed to sell its Catalyst Technologies business to Honeywell International for about £1.8bn in cash. At the time, Johnson Matthey’s market value was around £2.3bn. The shares rose on the news, but as Catalyst Technologies only accounts for about 25% of group profits, the managers still see the rest of the company as significantly undervalued.
Detractor
WPP
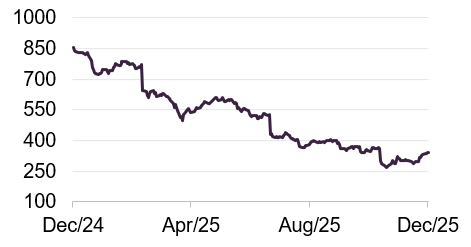
Figure 12: WPP (GBp)
Source: Bloomberg
WPP (www.wpp.com) is a leading global communications and advertising group, with agency brands covering media, creative, public relations, and technology services. Its wide reach gives it a diverse client base and exposure to both traditional and digital advertising.
In 2025, WPP was TMPL’s biggest disappointment, with shares falling by about two-thirds. The company issued two profit warnings, cutting its 2025 revenue forecast by 5-6% and expecting earnings to drop 25%. The industry faces a weak advertising cycle, and WPP has also struggled with management issues. The result is that the shares are very lowly rated and, in Ian and Nick’s view, all the new management has to do is steady the ship and begin making basic improvements for them to begin to recover. The managers are confident that this can happen in the coming months.
Peer group
You can find up-to-date information on TMPL and its peers on our website
TMPL continues to perform well compared to its peers. Discounts across the sector have narrowed recently, and three trusts now trade at a premium, with TMPL having the widest premium. Its ongoing charges ratio is 0.61%, lower than the peer group median of 0.82%.
Figure 13: Snapshot of UK equity income sector as at 6 January 2026
| Premium/(discount) (%) | Yield(%) | Ongoing charges(%) | Market cap(£m) | |
|---|---|---|---|---|
| Temple Bar Investment Trust | 1.81 | 3.9 | 0.61 | 1,124 |
| Aberdeen Equity Income Trust | 0.76 | 5.6 | 0.84 | 200 |
| BlackRock Income and Growth | (13.67) | 3.5 | 1.15 | 42 |
| Chelverton UK Dividend Trust | (2.77) | 7.1 | 2.79 | 31 |
| CT UK Capital and Income | (3.54) | 3.8 | 0.66 | 329 |
| Diverse Income Trust | (7.56) | 4.2 | 1.13 | 256 |
| Dunedin Income Growth | (7.13) | 6.2 | 0.56 | 372 |
| Edinburgh Investment Trust | (6.48) | 3.5 | 0.51 | 1,126 |
| Finsbury Growth & Income | (5.46) | 2.4 | 0.62 | 977 |
| JPMorgan Claverhouse | (4.36) | 4.1 | 0.63 | 483 |
| Law Debenture Corporation | (1.56) | 3.1 | 0.51 | 1,457 |
| Lowland Investment Company | (8.37) | 4.0 | 0.71 | 362 |
| Murray Income Trust | (8.51) | 4.3 | 0.50 | 885 |
| Schroder Income Growth Fund | (5.38) | 4.2 | 0.78 | 240 |
| Shires Income | (0.29) | 5.0 | 1.00 | 123 |
| The City of London Investment | 1.38 | 4.0 | 0.36 | 2,713 |
| The Merchants Trust | (5.79) | 4.8 | 0.52 | 895 |
| Peer group median | (4.5) | 4.3 | 0.82 | 683 |
| TMPL rank | 1/17 | 12/17 | 7/17 | 4/17 |
Source: Marten & Co
The yield remains at the lower end of the peer group but has risen from 3.5% to a strong 3.9% since our last note, helped by the new dividend policy detailed on page 12. TMPL is the fourth-largest fund in its sector.
Figure 14 illustrates TMPL’s extremely strong performance record against its peers, being the sector leader over six months, one year, three years and five years.
Figure 14: Total return NAV performance over periods ending 31 December 2025
| 3 months(%) | 6 months(%) | 1 year(%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| Temple Bar Investment Trust | 6.6 | 17.2 | 33.9 | 80.3 | 123.5 |
| Aberdeen Equity Income Trust | 7.5 | 16.8 | 30.8 | 39.7 | 62.5 |
| BlackRock Income and Growth | 6.0 | 10.1 | 16.2 | 36.7 | 56.7 |
| Chelverton UK Dividend Trust | (1.4) | (1.2) | 1.1 | 6.9 | 21.1 |
| CT UK Capital and Income | 2.3 | 5.2 | 13.2 | 33.5 | 45.1 |
| Diverse Income Trust | 1.8 | 8.4 | 23.5 | 38.4 | 38.8 |
| Dunedin Income Growth | 5.6 | 3.1 | 14.8 | 27.8 | 33.3 |
| Edinburgh Investment Trust | 2.3 | 3.9 | 10.0 | 42.9 | 78.8 |
| Finsbury Growth & Income | (4.6) | (10.2) | (7.6) | 5.3 | 11.2 |
| JPMorgan Claverhouse | 6.5 | 12.4 | 27.6 | 49.3 | 74.9 |
| Law Debenture Corporation | 4.8 | 12.1 | 27.8 | 61.3 | 96.0 |
| Lowland Investment Company | 6.2 | 13.1 | 31.5 | 54.7 | 80.7 |
| Murray Income Trust | 6.7 | 7.8 | 14.7 | 26.9 | 42.5 |
| Schroder Income Growth Fund | 7.2 | 11.6 | 25.1 | 41.3 | 63.8 |
| Shires Income | 8.2 | 11.0 | 26.0 | 42.4 | 59.2 |
| The City of London Investment | 6.7 | 11.9 | 27.2 | 51.0 | 90.5 |
| The Merchants Trust | 6.5 | 9.7 | 18.2 | 33.6 | 85.9 |
| Peer group median | (3.7) | (1.2) | 2.4 | 13.0 | 31.8 |
| TMPL rank | 6/17 | 1/17 | 1/17 | 1/17 | 1/17 |
Source: Bloomberg, Marten & Co
Dividend
Shareholders receive a dividend payment each quarter.
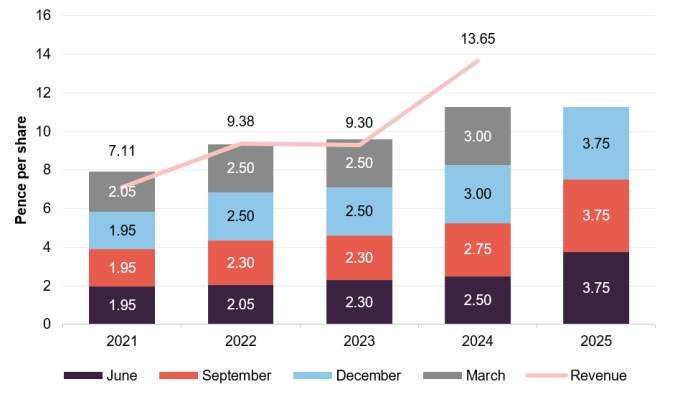
The board has confirmed it plans to pay out most of TMPL’s net revenue income to shareholders, with dividends paid quarterly. The first three payments for the 2025 financial year were 3.75p each, matching the total of all four payments made in 2024, and a final dividend is still to come.
This higher payout follows TMPL’s recent change in dividend policy. More companies are now returning value to investors through share buybacks rather than just dividends, especially those held by TMPL due to their low valuations. To ensure shareholders benefit from this, the board is increasing dividends by using TMPL’s distributable reserves to reflect a share of these buybacks. Dividends for 2025 each rose by 0.75p, reflecting this improvement. The board aims to increase dividends further in the coming year.
Figure 15: TMPL’s recent dividend record as of 31 December 2025
Source: Temple Bar Investment Trust
Premium/(discount)
Figure 16: TMPL discount over five years ended 31 December 2025
Source: Bloomberg, Marten & Co
In our last note, we highlighted the narrowing discount at the start of 2025. As shown in Figure 16, this has continued, and since the end of September, the shares have consistently traded at a premium. This is positive, especially given the discounts seen elsewhere in the investment companies sector.
TMPL’s shares moved to a premium at the end of 2025.
TMPL’s move to a premium reflects both its strong performance and a favourable UK market. If these trends continue, the trust could keep trading at or above par through 2026.
While the shares traded at a discount, the board repurchased 5.218 million shares in 2024 for £12.7m, with the last buyback in February 2025. Now that shares trade at a premium, the board has sold some treasury shares, 1.775 million in October, 1.15 million in November, and 2.12 million in December, improving liquidity and benefiting existing shareholders. We expect these sales to continue if the premium remains.
As new capital enters the fund, Ian and Nick are able to invest it quickly and report a steady flow of new opportunities.
Fund profile
You can access the trust’s website at: templebarinvestments.co.uk
TMPL aims to grow both income and capital to deliver long-term returns above the FTSE All-Share Index, mainly by investing in UK-listed companies. The portfolio usually focuses on stocks from the FTSE 350 Index, ensuring a broad spread of investments.
Co-managers Nick Purves and Ian Lance look for companies trading well below their estimated true value. They buy shares in undervalued, unpopular companies and hold them until prices better reflect their worth or until better opportunities arise.
Redwheel became manager of TMPL on 1 November 2020
Redwheel took over managing the portfolio on 1 November 2020, with Nick and Ian as co-managers. Together, they have over 50 years of experience and have worked as a team for more than 15 years, managing over £3bn in income funds. TMPL’s AIFM is Frostrow Capital.
SWOT analysis
Figure 17: SWOT analysis for TMPL
| Extremely strong performance in both NAV and share price terms, over both the short and long term. |
| A track record of consistently raising the dividend. This has been helped by a change in policy of enhancing the payout through its distributable reserves, reflecting the importance of share buybacks by its portfolio companies. |
| As a fund with a clear focus on value investing in the UK market, TMPL is exposed to a shift in investor sentiment to either, which could depress returns even with good stock-picking. |
| Despite a strong 2025, the UK market remains undervalued when compared to the likes of the US. Therefore, there remains significant upside potential for the stocks in TMPL’s portfolio. |
| The current macroeconomic environment looks favourable for TMPL, with value stocks typically doing well when corporate profitability is strong. |
| Although the recent move to a premium is testament to the strong performance and outlook for the fund, any investor buying at a premium risks a move back to par over time. |
Source: Marten & Co
Bull vs bear case
Figure 18: Bull vs bear case for TMPL
| Performance | Particularly strong performance over the past year, in both NAV and share price terms, adds to a very good long-term picture. | Such strong performance may not be maintained, particularly if the market environment turns against TMPL. |
| Dividends | Payouts to shareholders have consistently increased, supported by the new policy of enhancing these through distributable reserves. | There is no guarantee of these increases being maintained, if payouts and buybacks from the underlying companies come under pressure. |
| Outlook | The macroeconomic environment looks good for value investing, particularly in the UK where the market remains undervalued. | Both value investing and the UK market could move out of favour with investors, potentially quickly. |
| Discount/ premium | TMPL moved to a premium during 2025, a rare occurrence in recent investment company history. It is reflective of the strong performance and outlook, and could be extended further. | The premium may not last, and investment trust theory is that the fund should return to trading at NAV over the long term. |
Source: Marten & Co
Previous publications
Readers interested in further information about TMPL may wish to read our previous note, Temple of performance, published on 29 May 2025, as well as our previous notes. You can read the notes by clicking on them in Figure 19 or by visiting our website.
Figure 19: QuotedData’s previously published notes on TMPL
| Title | Note type | Date |
|---|---|---|
| Keeping faith | Initiation | 23 September 2020 |
| Just getting started | Update | 23 April 2021 |
| No compromise | Annual overview | 8 December 2021 |
| Time to Shine | Annual overview | 31 August 2022 |
| True Colours | Update | 26 June 2023 |
| Foundations for success | Update | 27 March 2024 |
| Historic opportunity | Annual overview | 22 October 2024 |
| Temple of performance | Update | 29 May 2025 |
Source: Marten & Co
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Temple Bar Investment Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.