
Gathering momentum?
BlackRock American Income (BRAI) has delivered consistent outperformance of its benchmark index and peer group since April 2025’s revamp. This appears to be translating into buying interest from investors. A rising NAV is also feeding through into higher dividends. The company is re-issuing shares and is now nearing a £200m market cap. It could pass thresholds at which it may become of greater interest to the larger wealth managers, and then the pace of this re-expansion could accelerate. That could lower average running costs and improve liquidity.
A recent rebalancing of the benchmark index has changed BRAI’s opportunity set. BRAI’s portfolio is valued at a discount to the wider US market. The manager believes that BRAI’s bias to value stocks will serve it well over the medium term.
Attractive income and growth from US value stocks, using a systematic active equity approach
BRAI aims to provide long-term capital growth, whilst paying an attractive level of income (1.5% of NAV per quarter, around 6% of NAV per annum). BRAI follows a systematic active equity approach that aims to provide consistent outperformance of the Russell 1000 Value Index.
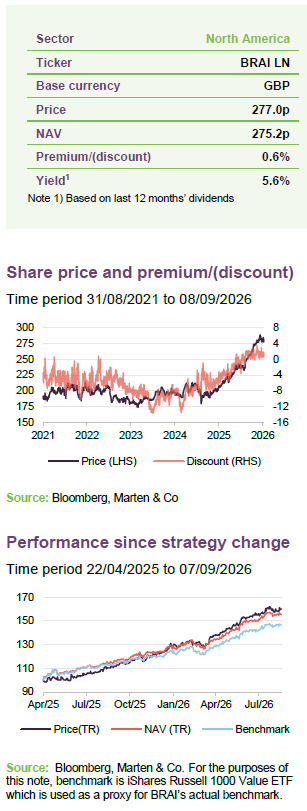
| 12 months ended | Share price total return (%) | NAV total return (%) | Benchmark (%) |
|---|---|---|---|
| 31/08/2026 | 43.0 | 36.5 | 30.0 |
Fund profile
More information is available on the trust’s website
BRAI aims to derive capital growth and pay an attractive income by investing in a portfolio of US value stocks.
A change to the company’s structure and approach was implemented in April 2025. The management fee was halved, and a new dividend policy introduced. The company pays out 1.5% of NAV each quarter as a dividend funded both from revenue and capital.
A more detailed look at BRAI’s structure and investment process was included within our initiation note
Stocks are selected using BlackRock’s proprietary systematic active equity approach. Our initiation note looked at the approach in detail but to summarise:
BlackRock’s Systematic Active Equity (SAE) team of over 100 investment professionals seeks to use data-derived insights to spot and exploit market inefficiencies (mispriced stocks).
The approach draws on over 40 years of experience in active investment management.
The SAE team evaluates sets of data to produce insights into companies’ fundamentals, market sentiment, and macroeconomic themes. The analysis includes both numeric and text datasets (contributing to over 1,000 signals in total) and makes use of LLM models that have been developed and optimised over many years.
Once the manager has a set of signals that it thinks is providing useful information, the scores from these signals are blended to give a view on each stock in the universe.
Higher scores correspond to higher return expectations, and this informs portfolio construction, which seeks to balance risk and return net of transaction costs. The manager seeks to avoid large factor, sector, or stock bets that could skew returns. BRAI is expected to hold 150–250 stocks of a universe of 870.
New signals are continually being identified and evaluated. BRAI’s manager describes this as an “arms race” where the aim is to extract as much information about stocks and the economy as possible, and learn how to interpret that. BlackRock believes its scale, depth of resource, and long history in this area gives it an edge that is hard to replicate.
Backdrop
Gasoline prices are well above pre-war levels but inflation is not as high as feared
It has been a few months since we last published on 27 February 2026. The outbreak of war between the US/Israel and Iran just one day later appears to have contributed to a shift in sentiment as the oil price rose, concerns grew over inflation, and the market outlook for interest rates shifted from probable cuts to possible rises. Oil prices have fluctuated since as hopes grew and faded for a lasting resolution to the conflict, and remain elevated. Gasoline prices are off their recent peaks (which may have contributed to a lower-than-expected 3.4% US inflation rate as at end July 2026), but above pre-war levels.
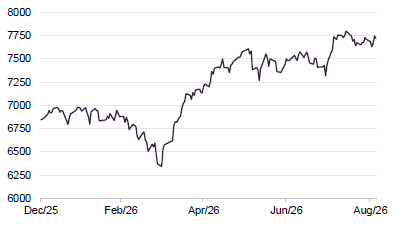
Nevertheless, the US market – as represented by the S&P 500 Index in Figure 2 –has risen year-to-date.
Figure 1: Oil price
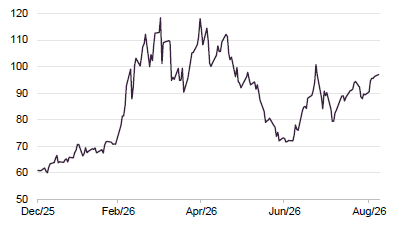
Figure 2: S&P 500
AI has been a big driver of share prices – both up and down
AI – and in particular the capex needed to support it and the potential impact of advances in agentic AI on software and data businesses (the so-called SaaSpocalypse) – appears to have influenced markets.
The “picks and shovels” trade – backing the companies that supply semiconductor equipment, memory, optical connectivity and data-centre infrastructure – appears to have contributed to share price appreciation for a number of companies that fell into BRAI’s benchmark, including Micron Technology, whose shares rose by 277% between 30 March 2026 and 25 June 2026. However, some investors appear to have become more concerned about the hyperscalers’ ability to finance this capex and the likely return on this investment. This may be reflected in the relative performance of the Magnificent 7, as Figure 3 shows.
Figure 3: Mag 7 relative to rest of S&P500
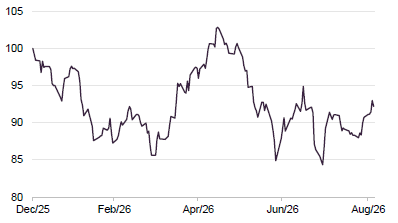
Figure 4: Yield on long-dated US Treasuries
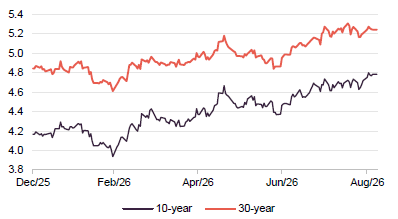
Even though US inflation remains above its 2% target, the Federal Reserve (Fed) has left interest rates unchanged so far this year. However, yields on US long-date government debt have been climbing, possibly as markets consider a potential $2trn deficit for 2026 and grow more concerned about its sustainability. Higher for longer rates may favour value strategies over growth strategies.
Asset allocation
At the end of June 2026, BRAI had 155 stocks in its portfolio, two more than as at the end of December 2025 (the data that we used when we last published) but towards the lower end of its 150–250 target range.
Data from the manager shows that, at the end of June 2026, the portfolio’s weighted average price/earnings ratio, price to book, and return on equity were close to the averages for the benchmark, but below those of the wider market.
Figure 5: Comparison of BRAI with US indices as at 30 June 2026
| BRAI | Benchmark | S&P 500 | |
|---|---|---|---|
| Number of securities | 155 | 870 | 504 |
| Average market cap ($bn) | 555.8 | 511.7 | 1,058.3 |
| P/E next 12 months (x) | 17.3 | 17.9 | 21.3 |
| Price/book (x) | 3.35 | 3.22 | 5.66 |
| Dividend yield (%) | 1.6 | 1.6 | 1.0 |
| ROE (5-year average) (%) | 14.0 | 14.8 | 12.6 |
Benchmark index rebalancing
A rebalancing of BRAI’s benchmark contributed towards some changes in the portfolio
BRAI’s benchmark index is now being rebalanced on a six-monthly basis. There is a size component to this, but in June there is also the chance to reclassify stocks from value to growth and vice versa.
The criteria for this are based on ranking stocks based on one value measure (book/price), which accounts for 50% of the total score, and two growth measures (two-year forecast earnings growth and historical five-year sales growth), which account for the other 50%. Stocks can end up being 100% value or 100% growth, but most end up with a foot in both camps.
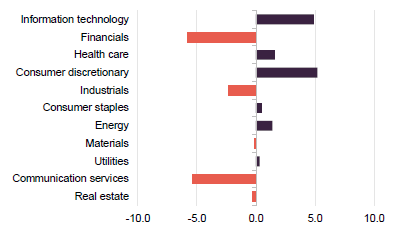
The shift at the end of June triggered some changes in BRAI’s portfolio as is reflected in the following charts.
These moves – notably an increase in the exposure to information technology and consumer discretionary at the expense of financials and communication services – predominantly reflect the change in the composition of the benchmark.
The increase in consumer discretionary comes as Amazon moved to become the largest stock in the benchmark (5.95% of the index as at the end of June, according to BRAI). The increase in information technology reflects the addition of Apple and Microsoft to the benchmark, offset to some extent as stocks such as Micron, Sandisk, and Western Digital move to the growth index.
Figure 6: BRAI asset allocation by sector as at 31 July 2026
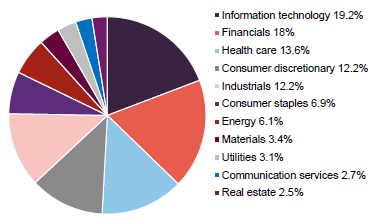
Figure 7: BRAI changes to sector allocations since 31 December 2025
The manager states that it is not looking to take any big factor, sector, or stock bets relative to the benchmark and this appears to be reflected in the changes to the list of the 10 largest holdings.
Top 10 holdings
Figure 8: Top 10 holdings as at 31 July 2026 compared to 31 May 2026
| % as at 31/07/26 | % as at 31/05/26 | Change | ||
|---|---|---|---|---|
| Amazon | Consumer discretionary | 6.8 | 2.5 | 4.3 |
| Apple | Information technology | 5.3 | 0.4 | 4.9 |
| Microsoft | Information technology | 4.6 | 0.6 | 4.0 |
| Berkshire Hathaway | Financials | 2.9 | 2.6 | 0.3 |
| JPMorgan Chase | Financials | 2.6 | 2.3 | 0.3 |
| Exxon Mobil | Energy | 1.9 | 2.1 | (0.2) |
| Bank of America | Financials | 1.8 | 1.9 | (0.1) |
| Chevron | Energy | 1.6 | 1.8 | (0.2) |
| Procter & Gamble | Consumer staples | 1.5 | 1.8 | (0.3) |
| Goldman Sachs | Financials | 1.4 | n/a | n/a |
| Total of top 10 | 30.4 | 25.1 |
Between the end of December 2025 and the end of May 2026, Walmart, Meta Platforms, and Charles Schwab had dropped out of the top 10. To be replaced by Exxon Mobil, Procter & Gamble, and Chevron.
Following the rebalancing as at 30 June, the position in Amazon was increased and a new position was taken in Apple. The only other new entrant to the top 10 at 31 July 2026 was Goldman Sachs. Dropping out since the rebalancing were Morgan Stanley, Alphabet, and Micron Technology.
Performance
Up to date information is available on our website
We have not included an analysis of BRAI’s returns before the strategy change in this note. Figure 9 shows how BRAI has performed both in share price and NAV terms versus its performance benchmark, against the S&P 500 Index, and against the median of its AIC North America peer group of Baillie Gifford US Growth, Canadian General Investments, JPMorgan American, Pershing Square Holdings, and The North American Income Trust. Within this group, BRAI ranks first over all the time periods shown in Figure 9. It also has a lower standard deviation of returns than this peer group.
Figure 9: Total return performance data for periods to end July 2026
| Calendar year | 1 month (%) | 3 months (%) | 6 months (%) | 1 year (%) | Since 22 April 20251 | 3 years (%) | 5 years (%) |
|---|---|---|---|---|---|---|---|
| BRAI share price | 1.5 | 7.8 | 18.7 | 43.0 | 58.3 | 78.3 | 85.0 |
| BRAI NAV | 1.6 | 9.5 | 16.7 | 36.5 | 55.5 | 62.6 | 74.7 |
| Benchmark | 2.1 | 8.3 | 14.7 | 30.0 | 46.9 | 60.8 | 77.2 |
| S&P 500 | 2.5 | 1.5 | 12.1 | 20.5 | 46.1 | 66.3 | 85.9 |
| Peer group median | 1.6 | 6.3 | 8.4 | 22.6 | 45.4 | 58.9 | 74.7 |
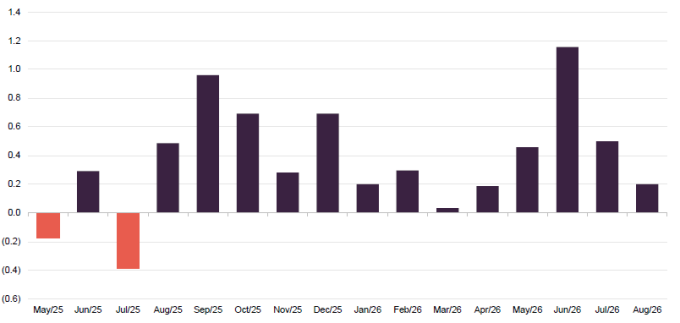
Figure 10 shows BRAI’s month-by-month relative returns and highlights the outperformance achieved over the past year.
Figure 10: BRAI NAV total return relative performance by month
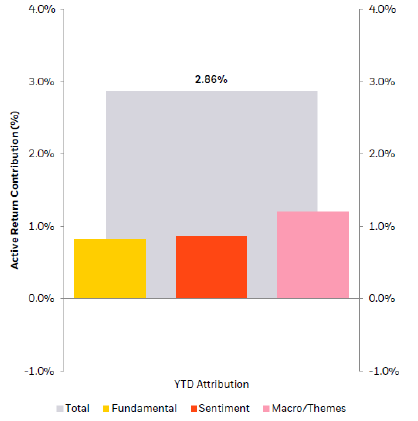
Figures 11 and 12 show the results of the manager’s performance attribution analysis for the first six months of 2026. In Figure 11, the yellow dots represent BRAI’s average active overweight and underweights relative to the benchmark and the bars illustrate the contributions by sector to BRAI’s returns over this period. Figure 12 shows that all of the signals made positive contributions to returns.
Figure 11: Attribution by sector
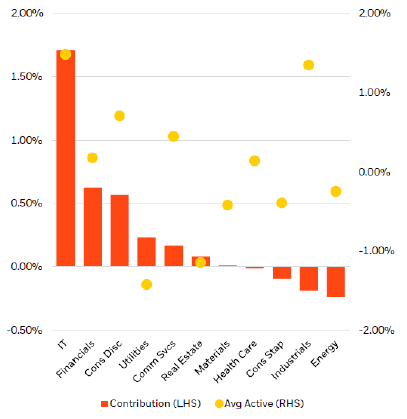
Figure 12: Attribution by signal
The contribution made by the IT sector was likely influenced by the AI capex-related increases in the share prices of stocks such as Micron, Applied Materials, LAM Research, Western Digital, and Sandisk. Since then, as described above, some of these stocks have fallen out of BRAI’s benchmark and no longer feature in its portfolio; it participated in the share price gains, but not the declines that have occurred since the index was rebalanced.
The model that underpins BRAI’s stock selection is designed to analyse a company’s supply chain as well as help predict customer demand. The manager says that the model identified a wide variety of stocks that were beneficiaries of the AI capex trade. According to the manager, it recognised the R&D spend that helped underpin their growth. The manager believes BRAI anticipated the trend as stocks that had been perceived as cash-generative, low-growth businesses saw orders multiply and margins expand.
Relative to the wider market, BRAI’s performance appears to have been helped by not having exposure to the highly-rated software and data businesses that fell during the selloff earlier this year. Markets fell amid investor concerns about the potential of agentic AI such as Claude Cowork to disrupt business models. However, it appears that high ratings were not the only reason BRAI was not exposed here. The potential threat posed by agentic AI was a theme that the model had already identified.
BRAI’s interim report had a table of contributors to and detractors from its relative returns over the six months ended 30 April 2026, the top five of each we have reproduced below.
| Stock | Sector | BRAI weight (%) | Benchmark weight (%) | Active weight (%) | Contribution (%) |
|---|---|---|---|---|---|
| Micron Technology | Information technology | 2.2 | 1.8 | 0.5 | 0.5 |
| Devon Energy | Energy | 0.5 | 0.1 | 0.4 | 0.5 |
| Bristol Myers Squibb | Health care | 1.4 | 0.3 | 1.1 | 0.3 |
| Moderna | Health care | 0.0 | 0.1 | (0.1) | 0.3 |
| Lam Research | Information technology | 0.4 | 0.0 | 0.4 | 0.3 |
Health care recovered as the market appeared to perceive that deals between pharmaceutical companies and the US government on pricing and overseas manufacturing could reduce the risk of government intervention in the sector. M&A has been picking up in this area too.
Figure 13: BRAI five largest contributions to relative returns over six months ended 30 April 2026
| Stock | Sector | BRAI weight (%) | Benchmark weight (%) | Active weight (%) | Contribution (%) |
|---|---|---|---|---|---|
| Exxon Mobil | Energy | 2.1 | 2.0 | 0.1 | (0.4) |
| Boston Scientific | Health care | 0.6 | 0.2 | 0.4 | (0.4) |
| Texas Instruments | Information technology | 0.0 | 0.5 | (0.5) | (0.2) |
| Merck &Co | Health care | 0.0 | 0.8 | (0.8) | (0.2) |
| Corning | Information technology | 0.0 | 0.4 | (0.4) | (0.2) |
Dividends
Enhanced dividend policy roughly 6% of NAV each year
BRAI has long paid part of its dividend out of capital. However, with effect from April 2025, BRAI adopted a policy of paying a quarterly dividend equivalent to 1.5% of NAV (approximately 6% annually). With less reliance on high-yielding stocks to generate its income, BRAI may have greater flexibility to invest across the US market and seek to maximise its total returns.
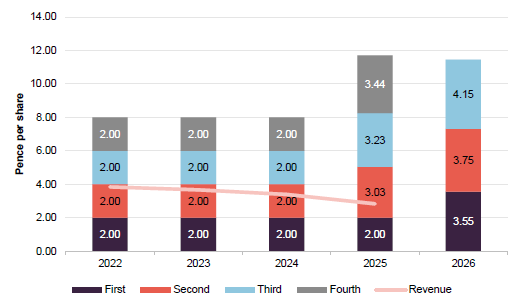
Figure 15 shows BRAI’s dividend history over the last five years. On 3 August 2026, BRAI announced that its third interim dividend would be payable on 11 September 2026.
Based on the NAV as at the time of publishing, the next dividend would be 4.15p, which would make a total of 15.6p for the current financial year, up 33% on the prior year.
Figure 15: BRAI five-year dividend history for financial years ending in October
Premium/(discount)
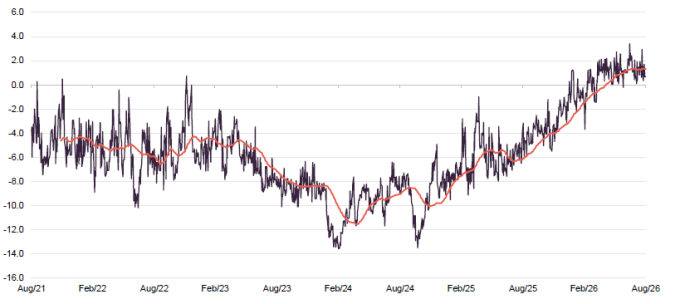
Over the 12 months ended 31 August 2026, BRAI’s shares traded between a 5.9% discount to NAV and a 3.4% premium and averaged a discount of 0.9%. By25 February 2026, the discount had been eliminated and as at the date of publication, BRAI’s shares were trading on a 0.6% premium.
The widening discount over 2023 came as the Magnificent 7 appeared to dominate markets and value stocks underperformed. BRAI’s rating began to improve in October 2024, perhaps initially in anticipation of a tender offer. However, investors appear encouraged by the performance of the new strategy and buying interest continues to grow. That may have helped shift the shares onto a premium to NAV this year, and this appears to have enabled BRAI to reissue shares, as we detail below.
Issuing stock at a premium to NAV may enhance the NAV for existing shareholders and improve liquidity in the shares. It may also spread BRAI’s fixed overheads over a wider base, potentially lowering its average running costs.
Figure 16: BRAI’s premium/(discount) over the five years ended 31 August 2026
Conditional tender offers
If BRAI fails to beat its benchmark net of fees by an average of 0.5% per annum over three-year periods (the first of which ends on 30 April 2028) the company has committed to offering shareholders a 100% tender offer at a 2% discount to NAV less costs. In addition, the 100% tender offer may also be triggered if the net assets of the company are less than £125m at the end of those three-year periods.
Share issuance and repurchase
On 27 August 2026, BRAI published a circular to convene a meeting on 14 September 2026 at which shareholders will be asked to approve the issue of up to 30% of BRAI’s share capital on 21 August 2026. BRAI has justified the 30% figure on the grounds that it saves the expense of holding more frequent meetings to approve the issue of smaller amounts of stock, and paves the way for a significant re-expansion of the trust. This could have the effect of improving liquidity, lowering average running costs – as fixed costs are spread over a wider base – and making the trust more attractive to larger wealth managers.
As at the date of publication, BRAI had 69,620,138 shares in issue with voting rights and a further 25,741,167 shares held in treasury.
Figure 17: Share issuance/repurchases over the past 12 months
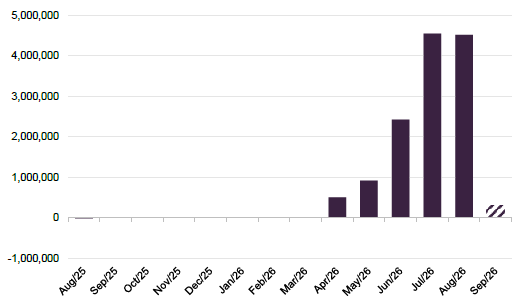
In April 2025, ahead of the strategy change, BRAI held a tender offer in which it bought back 10,910,252 shares into treasury at 192.0501p per share. The shares are up 47% since then. Over 13.2m shares have been issued over the last six months.
Previous publications
Readers interested in further information about BRAI may wish to read our previous notes.
Figure 18: QuotedData’s previously published notes on BRAI
| Title | Note type | Date |
|---|---|---|
| And now for something completely different | Initiation | 27 November 2025 |
| On the up | Update | 27 February 2026 |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on BlackRock American Income Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.