
On the up
BlackRock American Income Trust (BRAI) has continued to make progress both in absolute terms and relative to its benchmark since we last published at the end of November 2025. Whilst it is still relatively early days for the strategy, the results so far appear positive.
BRAI is benchmarked against a value index, which means it is significantly underweight the AI-driven mega-cap names that dominate broader US indices. This positioning appears to be benefiting BRAI at present as some investors are questioning whether some of these companies can sustain their capital expenditure programmes and whether those investments will generate acceptable returns. This uncertainty may be contributing to a broadening of interest in other parts of the market, which could be advantageous for BRAI. However, as shown on page 4, in a historic context, the recent increase in the performance of value relative to growth remains minor, so there could be room for further outperformance.
Attractive income and growth from US value stocks, using a systematic active equity approach
BRAI aims to provide long-term capital growth, whilst paying an attractive level of income (1.5% of NAV per quarter, around 6% of NAV per annum). BRAI follows a systematic active equity approach that aims to provide consistent outperformance of the Russell 1000 Value Index (the benchmark).
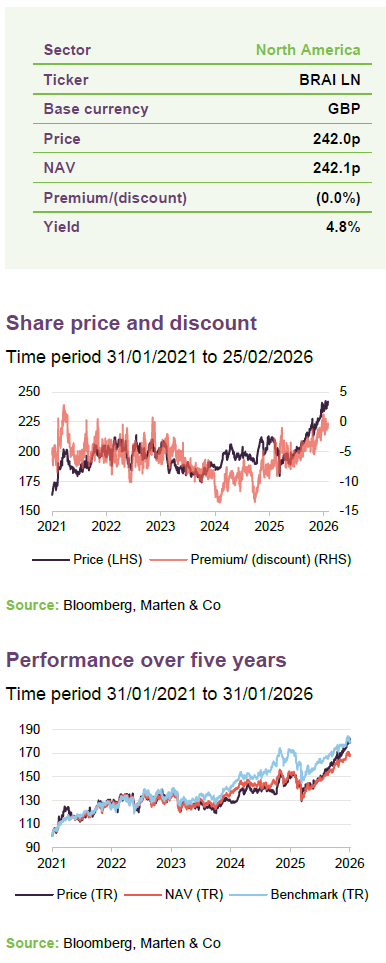
With effect from 22 April 2025, BRAI adopted a new investment approach. BRAI invests using a systematic active equity approach devised by BlackRock, which is different from that of other investment companies listed in the UK. The initiation note aimed to explain BRAI’s new approach and the corporate structure that supports it.
Historical performance data is included for reference in the charts on this page. This note focuses on BRAI’s returns since the strategy change.
Fund profile
More information is available on the trust’s website
BRAI aims to derive income and capital growth by investing in a portfolio of US value stocks.
A significant change to the company’s structure and approach was implemented in April 2025. The management fee was reduced by half, and a new dividend policy was introduced. The company pays out 1.5% of NAV each quarter as a dividend funded both from revenue and capital.
A more detailed look at BRAI’s structure and investment process was included within our initiation note
Stocks are selected using BlackRock’s proprietary systematic active equity approach. Our initiation note examined the approach in detail; in summary:
- BlackRock’s Systematic Active Equity (SAE) team of over 100 investment professionals seeks to use data-derived insights to identify and exploit market inefficiencies (mispriced stocks).
- The approach draws on over 40 years of insights into active investment management practices.
- The SAE team evaluates sets of data to generate insights into companies’ fundamentals, market sentiment, and macroeconomic themes. The analysis includes both numeric and text datasets (contributing to over 1,000 signals in total) and uses LLM models that have been developed and optimised over several years.
- Once the manager has a set of signals that it considers to be providing useful information, the scores from these signals are blended to produce a view on each stock in the universe.
- Higher scores are associated with higher return expectations, and this informs portfolio construction, which aims to achieve a trade-off between risk and return net of transaction costs. The manager seeks to avoid large factor, sector, or stock concentrations that could skew returns. BRAI will hold 150–250 stocks from a universe of 870.
- New signals are continually identified and evaluated. According to BRAI’s manager, this process is described as an “arms race” with the aim of extracting as much information about stocks and the economy as possible and learning how to interpret that information. BlackRock’s scale, depth of resource, and long history in this area are cited by the manager as factors that give it a competitive advantage.
Manager’s view
The manager observes that over the course of 2025, particularly over the summer, stocks with higher levels of indebtedness and losses outperformed. The manager states that this is reflected in the underperformance of most quality-focused managers last year.
Early in 2025, the Magnificent 7 stocks were affected by DeepSeek and Liberation Day (which occurred shortly before BRAI adopted its new investment approach), but appeared to recover as the year progressed. Companies perceived as beneficiaries of the significant sums being invested in AI capex performed well, particularly over the summer).
Figure 1: Magnificent 7 stocks versus rest of S&P 500

Another group of companies that outperformed were those that appeared to benefit from the US government’s policy agenda and/or technological advances. The manager highlights areas such as rare earths, SpaceTech, quantum computing, nuclear, batteries, and to a lesser extent, crypto as all attracting interest. However, enthusiasm for many of these themes appeared to peak around the beginning of Q4 before declining towards the end of the year.
The manager interprets this shift as a reassertion of fundamentals. Value outperformed growth over that period and has continued to do so since, but the turn in value’s favour appears limited in Figure 2. The data suggests that it may be premature to conclude with confidence that – in the US at least – value is consistently outperforming growth, as it did for the majority of the period prior to the GFC and the low inflation/interest rate environment that followed it.
Figure 2: Value versus growth in US market

Asset allocation
At the end of December 2025, BRAI had 153 stocks in its portfolio – towards the lower end of its 150–250 target range.
Figure 3: BRAI asset allocation by sector as at 31 December 2025

Figure 4: BRAI changes to sector allocations since 30 September 2025

Over the final quarter of 2025 – capturing the reported change since the last publication – the portfolio saw a modest increase in its weighting to information technology and a small reduction in consumer discretionary. These moves seem minor and would appear to reflect BRAI’s benchmark-aware approach.
Data from the manager indicates that, at the end of December 2025, the portfolio’s weighted average price/earnings ratio, price to book, and return on equity were close to the averages for the benchmark.
Figure 5: Comparison of BRAI with US indices
| BRAI | Benchmark | S&P 500 | |
|---|---|---|---|
| Number of securities | 153 | 870 | 503 |
| Average market cap ($bn) | 408.3 | 299.4 | 1,069.7 |
| P/E next 12 months (x) | 17.6 | 17.6 | 22.9 |
| Price/book (x) | 3.15 | 2.98 | 5.54 |
| Dividend yield (%) | 1.7 | 1.8 | 1.1 |
| ROE (5-year average) (%) | 10.3 | 10.2 | 18.0 |
Top 10 holdings
Figure 6: Top 10 holdings as at 31 December 2025 %
| % as at 31/12/25 | % as at 30/09/25 | Change | ||
|---|---|---|---|---|
| Alphabet | Communication services | 4.6 | 1.9 | 2.7 |
| JPMorgan Chase | Financials | 3.0 | 3.2 | (0.2) |
| Amazon | Consumer discretionary | 2.9 | 2.6 | 0.3 |
| Berkshire Hathaway | Financials | 2.6 | 2.8 | (0.2) |
| Walmart | Consumer staples | 2.5 | 2.6 | (0.1) |
| Bank of America | Financials | 2.3 | 2.3 | – |
| Morgan Stanley | Financials | 1.8 | 1.9 | (0.1) |
| Meta Platforms | Communication services | 1.8 | n/a | n/a |
| Charles Schwab | Financials | 1.7 | 1.7 | – |
| Micron Technology | Information technology | 1.6 | n/a | n/a |
| Total |
As discussed earlier, the manager says that it does not take large active stock positions relative to the benchmark, and the list of BRAI’s largest holdings reflects this approach. Since the end of September 2025, Johnson & Johnson and Pfizer have dropped out of the top 10 to be replaced by Meta Platforms and Micron Technology.
Performance
Building a track record of outperformance
For the purpose of this note, we are focusing on BRAI’s returns since the strategy change. Figure 7 shows BRAI’s performance in both share price and NAV terms versus its performance benchmark, the S&P 500 Index, and the median of its AIC North America peer group.
Figure 7: Total return performance data for periods to end January 2026
| Calendar year | 1 month(%) | 3 months(%) | 6 months(%) | Since 22 April 2025(%) |
|---|---|---|---|---|
| BRAI share price | 2.6 | 9.0 | 18.4 | 27.1 |
| BRAI NAV | 2.8 | 4.8 | 13.3 | 27.1 |
| Benchmark | 2.6 | 3.5 | 9.6 | 22.7 |
| S&P 500 | (0.5) | (2.5) | 6.2 | 28.9 |
| Peer group median | (0.4) | (3.1) | 4.0 | 27.1 |
Figure 8 shows BRAI’s month-by-month relative returns and highlights the strong run of outperformance achieved over the past six months.
Figure 8: BRAI NAV total return relative performance by month

The trust has delivered outperformance of its benchmark and ahead of its peers under its new investment approach. In 2025 it was the top performing North American equity trust in the peer group, and it continues to be the top performer over the last 12 months. This may reflect the shift back towards a more fundamentally driven market that the manager has noted.
Figure 9: Attribution by sector

Figure 10: Attribution by signal

The manager states that the portfolio has performed well in periods of volatile markets, when dislocations have created mispricing opportunities. BRAI’s returns have also been less volatile than those of its benchmark, with a standard deviation of 9.9% since the strategy change versus 10.3% for the index.
In Figure 9, the yellow dots represent BRAI’s average active overweight and underweights relative to the benchmark, and the bars illustrate the contributions by sector to BRAI’s returns over this period.
Figure 10 breaks down the source of relative return by signal. All three signals made positive contributions, with market sentiment driven stock selection signals appearing to have the greatest impact. The manager highlights the importance of being aware of where retail money was flowing, referencing lessons learned from the meme stock phenomenon over 2024 and into 2025. According to the manager, these flows do not necessarily identify the best long-term performers, but can materially distort short-term returns.
Dividends
New enhanced dividend policy roughly 6% of NAV each year
BRAI has historically paid part of its dividend out of capital. With effect from 17 April 2025, BRAI adopted a policy of paying a quarterly dividend equivalent to 1.5% of NAV (approximately 6% annually). Without the requirement to hold high-yielding stocks to generate its income, BRAI has greater flexibility to invest across the US market with the aim of increasing its total returns.
The x-axis labels show historic ex dates for BRAI’s dividends. Management states that, going forward, the intention is to pay the dividends in April, July, October, and January.
Figure 11 shows BRAI’s dividend history over the last five years. There are now 12 months of dividends declared under the new system totalling 13.25p.
Figure 11: BRAI five-year dividend history for financial years ending in October

Premium/(discount)
Over the 12 months ended 31 January 2026, BRAI’s shares traded between 9.1% discount to NAV and a 1.2% premium and averaged a discount of 4.8%. By25 February 2026, the discount had been eliminated.
Figure 12: BRAI’s premium/(discount) over the five years ended 31 January 2026

As stated in the previous note, the widening discount over 2023 coincided with the period when the Magnificent Seven dominated markets and value stocks underperformed. BRAI’s rating began to improve in October 2024, initially on what appears to be the anticipation of a tender offer. Since then, it has continued to narrow and is currently trading close to asset value or at a premium. The board has indicated an intention for the trust to re-expand and has powers to issue stock at a premium to NAV, which should enhance the NAV for existing shareholders and improve liquidity in the shares. This could also spread BRAI’s fixed overheads over a wider base, potentially lowering its average running costs.
Conditional tender offers
If BRAI fails to beat its benchmark net of fees by an average of 0.5% per annum over three-year periods, the first of which ends on 30 April 2028, the company has committed to offering shareholders a 100% tender offer at a 2% discount to NAV less costs. In addition, the 100% tender offer may also be triggered if the net assets of the company are less than £125m at the end of those three-year periods.
Previous publications
Readers interested in further information about BRAI may wish to read our previous note – And now for something completely different – which was published on 27 November 2025.
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on BlackRock American Income Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.