
On the up
BlackRock American Income Trust (BRAI) has performed well both in absolute terms and compared to its benchmark since our last update in November 2025. Although the strategy is still new, early results are promising.
BRAI uses a value index as its benchmark, so it holds fewer of the large AI-focused US companies that dominate broader indices. This has helped recently, as investors are starting to question whether these companies can maintain their high levels of investment and whether this investment can deliver decent returns. As a result, interest is spreading to other areas of the market, which benefits BRAI. However, as shown on page 4, the recent improvement in the performance of value stocks compared to growth stocks is still quite small by historical standards, suggesting there may be further room for value to catch up.
Attractive income and growth from US value stocks, using a systematic active equity approach
BRAI aims to provide long-term capital growth, whilst paying an attractive level of income (1.5% of NAV per quarter, around 6% of NAV per annum). BRAI follows a systematic active equity approach that aims to provide consistent outperformance of the Russell 1000 Value Index (the benchmark).
From 22 April 2025, BRAI began using a new investment strategy designed by BlackRock, which is unique among UK-listed investment companies. Our earlier note explained this new strategy and the corporate structure that supports it.
While we include some past performance data for reference, this report focuses on BRAI’s returns since adopting the new strategy
From 22 April 2025, BRAI began using a new investment strategy designed by BlackRock, which is unique among UK-listed investment companies. Our earlier note explained this new strategy and the corporate structure that supports it.
While we include some past performance data for reference, this report focuses on BRAI’s returns since adopting the new strategy
At a glance
Share price and discount
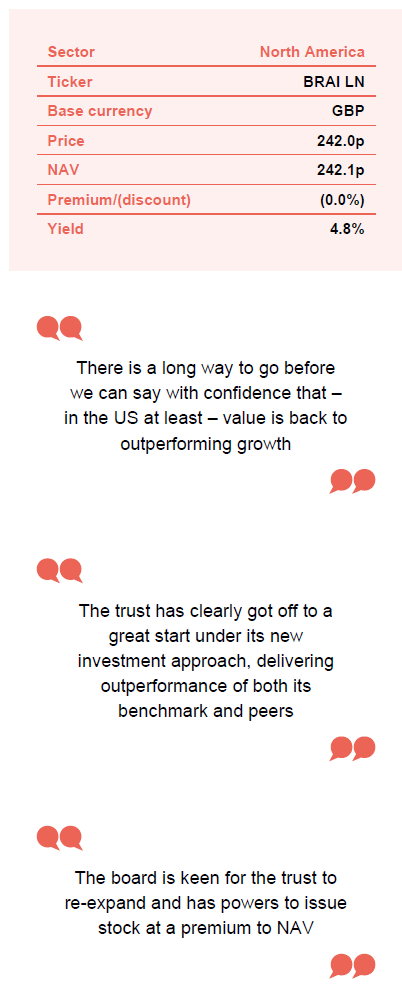
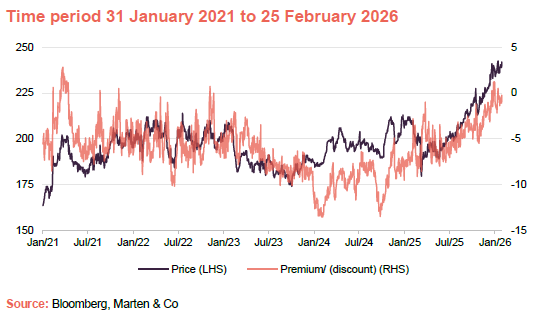
Over the 12 months ended 31 January 2026, BRAI’s shares traded between 9.1% discount to net asset value (NAV) and a 1.2% premium and averaged a discount of 4.8%. By25 February 2026, the discount had been eliminated.
The board is keen for the trust to re-expand and has powers to issue stock at a premium to NAV, which would enhance the NAV for existing shareholders and improve liquidity in the shares.
Performance over five years
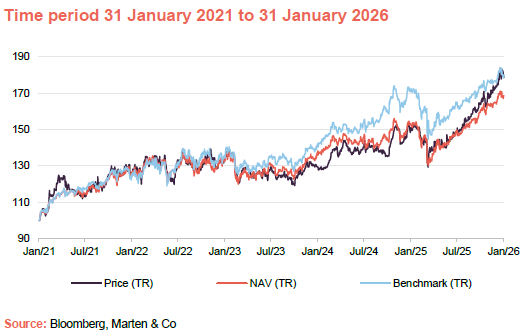
The trust has got off to a great start under its new investment approach, delivering outperformance of both its benchmark and peers. In 2025, it was the top performing North American equity trust in the peer group, and this has continued into this year. This may reflect the shift back towards a more fundamentally driven market that the manager says it has observed.
Fund profile
More information is available on the trust’s website
BRAI aims to deliver income and capital growth by investing in US value stocks. In April 2025, the company made major changes, halving its management fee and introducing a new dividend policy. It now pays a quarterly dividend of 1.5% of NAV, funded from both income and capital.
A more detailed look at BRAI’s structure and investment process was included within our initiation note
Stocks are selected using BlackRock’s proprietary systematic active equity approach. The Systematic Active Equity (SAE) team, with over 100 professionals, uses data-driven insights to find and exploit mispriced stocks. Drawing on 40 years of experience, the team analyses a wide range of data on company fundamentals, market sentiment, and economic trends, using both numbers and text. This analysis produces over 1,000 signals, including those from advanced language models.
Signals are blended to score each stock, guiding portfolio construction to balance risk and return after costs. The manager avoids large bets on any single factor, sector, or stock. BRAI typically holds 150–250 stocks from a universe of 870. New signals are regularly identified and tested, with the manager describing this as an “arms race” to extract and interpret information. BlackRock’s size, resources, and experience provide a significant advantage.
Manager’s view
The manager notes that in 2025, especially during the summer, poor-quality stocks (those with high levels of debt and are loss-making) outperformed, leading to underperformance among quality-focused managers. Early in the year, the Magnificent 7 stocks were affected by announcements around DeepSeek and Liberation Day, just before BRAI changed its investment strategy, but later recovered. Companies seen as benefiting from large AI investment also performed strongly, particularly in the summer.
Figure 1: Magnificent 7 stocks versus rest of S&P 500

Some top performers were companies boosted by US government policies or new technologies, including rare earths, SpaceTech, quantum computing, nuclear, batteries, and, to a lesser extent, crypto. Interest in these areas peaked at the start of Q4 but faded by year-end.
The manager sees this development as a return to focusing on company fundamentals. During this time, value stocks outperformed growth stocks and have continued to do so, though this shift is hard to see in Figure 2. It will take more time before we can confidently say that value is outperforming growth in the US, as it did before the financial crisis and the era of low inflation and interest rates that followed.
Figure 2: Value versus growth in US market

Asset allocation
At the end of December 2025, BRAI had 153 stocks in its portfolio – towards the lower end of its 150–250 target range.
Figure 3: BRAI asset allocation by sector as at 31 December 2025

Figure 4: BRAI changes to sector allocations since 30 September 2025

In the final quarter, the portfolio’s weighting in information technology was increased slightly, while its exposure to consumer discretionary was reduced. These small changes reflect BRAI’s benchmark-aware strategy. Data from the manager shows that the portfolio’s average price/earnings ratio, price to book, and return on equity were similar to the benchmark averages at year-end.
Figure 5: Comparison of BRAI with US indices
| BRAI | Benchmark | S&P 500 | |
|---|---|---|---|
| Number of securities | 153 | 870 | 503 |
| Average market cap ($bn) | 408.3 | 299.4 | 1,069.7 |
| P/E next 12 months (x) | 17.6 | 17.6 | 22.9 |
| Price/book (x) | 3.15 | 2.98 | 5.54 |
| Dividend yield (%) | 1.7 | 1.8 | 1.1 |
| ROE (5-year average) (%) | 10.3 | 10.2 | 18.0 |
Top 10 holdings
Figure 6: Top 10 holdings as at 31 December 2025
| % as at 31/12/25 | % as at 30/09/25 | Change | ||
|---|---|---|---|---|
| Alphabet | Communication services | 4.6 | 1.9 | 2.7 |
| JPMorgan Chase | Financials | 3.0 | 3.2 | (0.2) |
| Amazon | Consumer discretionary | 2.9 | 2.6 | 0.3 |
| Berkshire Hathaway | Financials | 2.6 | 2.8 | (0.2) |
| Walmart | Consumer staples | 2.5 | 2.6 | (0.1) |
| Bank of America | Financials | 2.3 | 2.3 | – |
| Morgan Stanley | Financials | 1.8 | 1.9 | (0.1) |
| Meta Platforms | Communication services | 1.8 | n/a | n/a |
| Charles Schwab | Financials | 1.7 | 1.7 | – |
| Micron Technology | Information technology | 1.6 | n/a | n/a |
| Total |
The manager avoids taking large positions c, Johnson & Johnson and Pfizer have left the top 10, replaced by Meta Platforms and Micron Technology.
Performance
Building a track record of outperformance
As previously highlighted, we do not consider that an analysis of BRAI’s returns before the strategy change was implemented are relevant for this note. Figure 7 shows BRAI’s share price and NAV performance compared to its benchmark, the S&P 500 Index, and the median of its AIC North America peer group.
Figure 7: Total return performance data for periods to end January 2026
| Calendar year | 1 month(%) | 3 months(%) | 6 months(%) | Since 22 April 2025(%) |
|---|---|---|---|---|
| BRAI share price | 2.6 | 9.0 | 18.4 | 27.1 |
| BRAI NAV | 2.8 | 4.8 | 13.3 | 27.1 |
| Benchmark | 2.6 | 3.5 | 9.6 | 22.7 |
| S&P 500 | (0.5) | (2.5) | 6.2 | 28.9 |
| Peer group median | (0.4) | (3.1) | 4.0 | 27.1 |
Figure 8 shows BRAI’s month-by-month relative returns and highlights the strong run of outperformance achieved over the past six months.
Figure 8: BRAI NAV total return relative performance by month

The trust has started well under its new investment approach, outperforming its benchmark and peers. In 2025, it was the top-performing North American equity trust in its group and remains the leader over the past 12 months. This strong performance may be due to the market’s shift back to a more fundamentals-based approach, as noted by the manager.
Figure 9: Attribution by sector

Figure 10: Attribution by signal

The manager notes that the portfolio has performed well during volatile markets, taking advantage of mispricing opportunities. BRAI’s returns have also been less volatile than its benchmark, with a standard deviation of 9.9% since the strategy change compared to 10.3% for the index.
Figure 9 shows BRAI’s average sector overweights and underweights versus the benchmark, along with each sector’s contribution to returns. Figure 10 breaks down relative returns by signal, with all three signals contributing positively. Stock selection based on market sentiment had the biggest impact. The manager highlights the importance of tracking retail money flows, as seen during the meme stock events in 2024 and 2025. While these flows may not point to the best long-term investments, they can significantly affect short-term returns.
Dividends
New enhanced dividend policy roughly 6% of NAV each year
BRAI has historically paid part of its dividend from capital. From 17 April 2025, it switched to a policy of paying a quarterly dividend equal to 1.5% of NAV, or about 6% a year. This change means BRAI no longer needs to focus on high-yield stocks and can invest more freely across the US market to maximise total returns.
Dividends are now planned for April, July, October, and January. Over the past year under this new approach, BRAI has declared total dividends of 13.25p. Figure 11 shows the dividend history for the last five years.
Figure 11: BRAI five-year dividend history for financial years ending in October

Premium/(discount)
Over the 12 months to 31 January 2026, BRAI’s shares traded between a 9.1% discount and a 1.2% premium to NAV, averaging a 4.8% discount. By 25 February 2026, the discount had disappeared.
Figure 12: BRAI’s premium/(discount) over the five years ended 31 January 2026

As noted previously, the discount widened in 2023 as value stocks lagged behind the Magnificent Seven. BRAI’s rating started to improve from October 2024, helped by expectations of a tender offer, and has since moved close to or above asset value. The board wants the trust to grow and has the authority to issue new shares at a premium, which would benefit existing shareholders by raising NAV, improving liquidity, and spreading fixed costs over more shares, reducing average running costs.
Conditional tender offers
If BRAI does not outperform its benchmark by at least 0.5% per year after fees over three-year periods (the first ending 30 April 2028), it will offer shareholders a 100% tender at a 2% discount to NAV after costs. This tender may also be triggered if the company’s net assets fall below £125m at the end of any of these periods.
SWOT and bull vs. bear analysis
Figure 13: SWOT analysis
| Strengths | Weaknesses |
|---|---|
| Differentiated investment proposition | Investors need to get comfortable with the investment approach |
| Enhanced income whilst maintaining risk-controlled exposure to US equities | |
| Encouraging early performance | Relatively low market cap restricts attraction for wealth managers |
| Considerable backing of BlackRock | |
| Opportunities | Threats |
| Discount has been eliminated, potential for a re-expansion of the trust | Persistent US dollar weakness undermines attractions for UK investors |
| Recent market moves mean that US investors are thinking more about diversification | AI could continue to dominate the investment agenda, perpetuating the outperformance of growth stocks |
| Value is overdue a return to favour |
Figure 14: Bull versus bear case
| Bull | Bear | |
|---|---|---|
| Performance | Off to a great start with fairly consistent outperformance and lower volatility | AI resurgence could depress value stocks further |
| Dividends | Dividend policy results in attractive yield | If markets fell for an extended period, the dividend policy would shrink the capital base of the company |
| Outlook | Value is picking up and a more decisive shift in sentiment could help extend BRAI’s run of good relative performance | Weak dollar and return to outperformance by growth stocks are both possibilities |
| Discount | Appears to be under control | Small size reduces the impact of buybacks as liquidity worsens |
Previous publications
Readers interested in further information about BRAI may wish to read our previous note – And now for something completely different – which was published on 27 November 2025.
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on BlackRock American Income Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.