
Defensively positioned, cautious on inflation
The managers of Capital Gearing Trust (CGT) remain cautious about market and inflation risks, and have adjusted the trust’s portfolio to reflect this. Exposure to risk assets was reduced to 25% by the end of November 2025, while holdings in UK inflation-linked bonds were increased.
Last November, the managers opposed a proposed merger for HICL Infrastructure (one of the holdings in the risk assets part of CGT’s portfolio), leading a campaign group of HICL shareholders against it. The deal was stopped, and HICL’s share price has since recovered. This highlights the behind-the-scenes work CG Asset Management (CGAM) does to reduce discounts across UK-listed investment companies.
Preserve and grow shareholders’ real wealth
CGT aims to preserve and grow its shareholders’ real wealth over time. Whilst it has a long-term investment horizon, it has an aversion to short-term losses. That means that greater emphasis is placed on avoiding loss than on maximising returns. It targets returns in sterling that are ahead of inflation over the long term.

At a glance
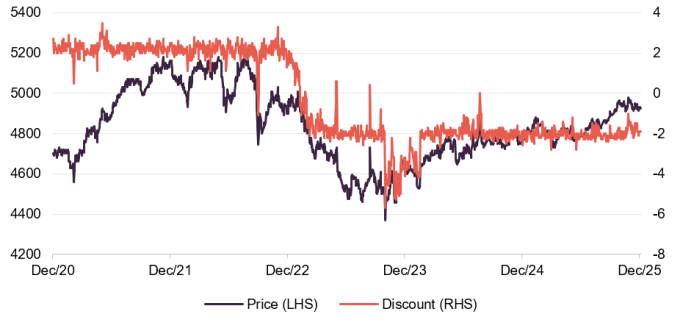
Share price and discount
The board believes shareholders should not have to face the risk of a wide discount. Since 2015, CGT has run a discount control policy, aiming to buy or issue shares so they trade close to NAV under normal market conditions.
In the 12 months to 31 December 2025, CGT’s shares traded at discounts between 2.8% and 1%, averaging 2.0%. At publication, the shares were at a 1.9% discount.
Time period 31 December 2020 to 5 January 2026
Source: Bloomberg, Marten & Co
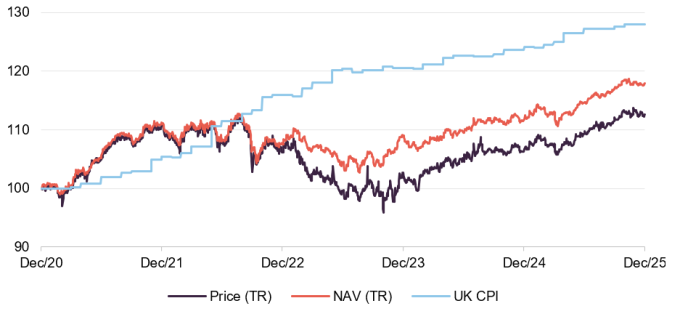
Performance over five years
CGT has continued to protect and grow shareholders’ capital in real terms over the long term. Looking at the five-year picture, it is also recovering against the inflation index following the sharp rise in inflation during 2021 and 2022.
Time period 31 December 2020 to 31 December 2025
Source: Bloomberg, Marten & Co
| 12 months ended | Share pricetotal return (%) | NAV total return (%) | UK CPI(%) | MSCI UK total return (%) |
|---|---|---|---|---|
| 31/12/2021 | 10.8 | 11.0 | 5.4 | 19.7 |
| 31/12/2022 | (4.2) | (3.2) | 10.0 | 7.2 |
| 31/12/2023 | (3.3) | 1.3 | 4.0 | 7.7 |
| 31/12/2024 | 4.0 | 2.6 | 3.0 | 9.5 |
| 31/12/2025 | 5.4 | 5.4 | 3.1 | 25.8 |
Source: Bloomberg, Marten & Co
Fund profile
You can access the trust’s website at: www.capitalgearingtrust.com
CGT is aimed at long-term investors who want to avoid large short-term losses and achieve returns above inflation. Over the long term, it has outperformed inflation with low drawdowns.
The manager, CG Asset Management (CGAM), also serves as the company’s AIFM. CGAM was founded in 2001 by Peter Spiller, who has managed CGT’s portfolio since 1982. Since then, CGT has had only two years where the NAV total return was negative – the 12 months ending March 2014 and March 2023 –both during periods of rising bond yields.
CGAM is mainly owned by an employee trust and plans to stay independent. Most managers have significant personal investments in the funds they run, closely aligning their interests with clients.
The CGAM team has 10 members, with six focused on investments: Peter Spiller, Alastair Laing, Chris Clothier, and newer members Hassan Raza, Emma Moriarty, and Jock Henderson. As at 31 December 2025, CGAM managed £2.3bn in assets.
In July 2025, Karl Sternberg became CGT’s chairman. He previously held senior roles at Morgan Grenfell/Deutsche Asset Management and co-founded Oxford Investment Partners. He has chaired several investment trusts and currently chairs Clipstone Industrial REIT and is a non-executive director at Howard de Walden Estates.
New chair in place
Managers’ view
Market optimism for 2026 could be scuppered by inflation
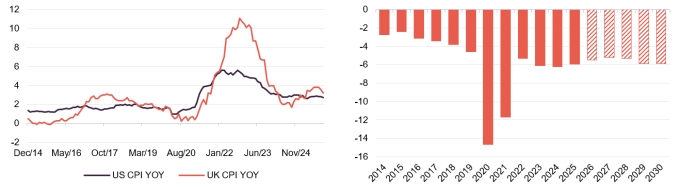
Recently, several brokers have issued positive forecasts for equity markets, especially in the US, for 2026. These are based on expectations of lower interest rates, tax rebates, and infrastructure spending. However, there is a real risk that persistent or rising inflation could disrupt these predictions. If inflation does not ease, CGT’s managers believe there will be few safe options for investors.
Figure 1: US and UK inflation rates
Figure 2: US fiscal deficit as a percentage of GDP
Source: Bloomberg
Source: Federal Reserve Bank of St Louis (historic figures), US Congressional Budget Office (forecasts as at March 2025).
In 2021, easy-money (low interest rate and high government spending) policies to support economies during COVID led to higher inflation. While inflation has slowed, it is still above central bank targets. CGT’s managers expect this situation could continue for some time.
COVID-related spending has led to larger fiscal deficits in most developed countries. Despite this, governments are not cutting back, causing concern in bond markets, and leading to more volatility in long-term bond yields.
A third of the S&P 500 is in stocks trading on more than 10x revenues
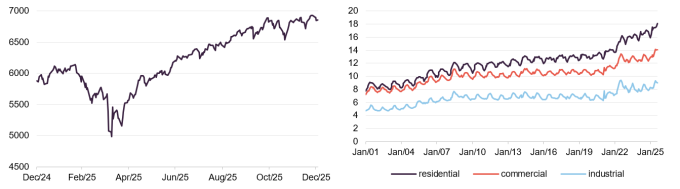
Figure 3 shows the recent performance of the S&P500 Index of US stocks. The managers say that equity market valuations also appear high. The managers point out that a third of the S&P 500, by market cap, trades at over 10 times revenues. This excludes Alphabet, just under 10 times, and Amazon, where the figure is lower due to its ecommerce business, though much of its value is linked to its cloud division.
The team notes that the biggest AI-focused companies are becoming more capital intensive, making it harder to achieve the returns needed to justify their planned investment.
Figure 3: S&P 500 Index 2025 and 2026 YTD
Figure 4: Average US power prices in cents per kilowatt-hour
Source: Bloomberg
Source: US Energy Information Administration
Tariff announcements in early April caused brief market volatility. CGT held up well falling by just 2% by comparison to c.20% in global equities. While the overall impact has been less than expected, tariffs are still pushing up inflation and slowing growth. US GDP growth is being boosted by AI-related investment; without it, the economy would be flat. The rising power needs of AI data centres are also pushing up US energy prices (as Figure 4 shows), which is likely to add to inflation.
At CGAM’s recent capital markets day, Peter Spiller argued that commercial real estate is overpriced. He believes investors are overlooking the cost of redeveloping offices every 25–30 years, which can reduce expected returns by about 2.8% a year. Current prime yields are around 5.5% in the City and 3.75% in the West End, according to Cushman & Wakefield.
Gold has performed well this year, and CGT holds a small position. However, the managers remain cautious, as CGT aims to preserve real wealth. They note that gold offers no yield, has a mixed record as an inflation hedge, and its prices can be highly speculative. While gold sometimes does well during war or political turmoil, its volatility and reliance on market sentiment create risks that do not align with the trust’s main goal.
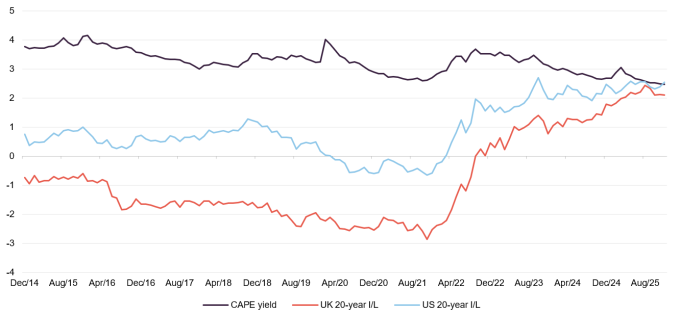
Due to concerns over high valuations, CGT is shifting its asset allocation away from risk assets and towards inflation-linked bonds, which the team believes still offer the chance of positive real returns. Figure 5 helps illustrate their thinking. The cyclically adjusted price to earnings ratio (CAPE) compares current valuations to the average of the previous 10 years of inflation-adjusted earnings. It is a way of assessing whether markets look cheap or expensive on a long-term view. The inverse of this is the cyclically adjusted earnings yield. The team points out that the CAPE equity yield is now about the same as the yield on 20-year UK inflation-linked gilts and 20-year US TIPS, highlighting how expensive equities have become.
Figure 5: CAPE equity yield versus inflation linked bond yields
Source: Bloomberg, Robert Shiller online dataset (at yale.edu)
CGT maintains liquidity through cash and high-quality, short-term credit, allowing the team to quickly increase risk asset exposure if markets fall and better opportunities arise. The managers note it has been a long time since the last major market downturn, and they are prepared to act when it happens.
Asset allocation
Figure 6 shows how CGT’s monthly asset allocation has changed since March 2011. Despite reducing exposure to risk assets (the funds/equities portion of the pie), the team still sees many unique opportunities to add value in that part of the portfolio.
Figure 6: CGT asset allocation history

Source: Capital Gearing Trust
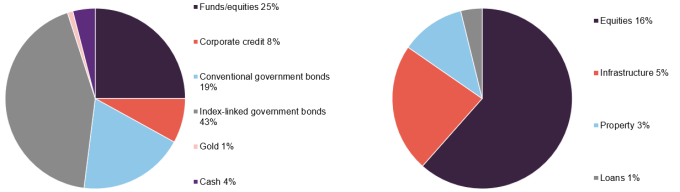
Since our last note, which used data from June 2025, CGT has increased its exposure to index-linked government bonds, reducing holdings in funds, equities, corporate credit, and conventional government bonds. This year, there has been a move towards UK index-linked bonds, funded by selling US TIPS.
Figure 7: Asset allocation as at 30 November 2025
Figure 8: Split of funds/equities allocation as at 30 November 2025
Source: Capital Gearing Trust
Source: Capital Gearing Trust
The managers state that CGT’s asset allocation is deliberately cautious compared to other multi-asset investment trusts. The portfolio focuses on capital preservation, favouring inflation-linked government bonds, defensive assets, and low-volatility investments rather than growth-oriented risk assets.
This leads to less sensitivity to stock market declines and credit risk, and returns that are differentiated from traditional multi-asset funds, which typically hold more equities and credit. CGT’s defensive approach is a long-term strategy aimed at preserving real wealth in all market conditions.
The portfolio’s duration has risen slightly from 3.9 years since our last update. While credit spreads have narrowed this year, the average credit quality of the portfolio has improved since June.
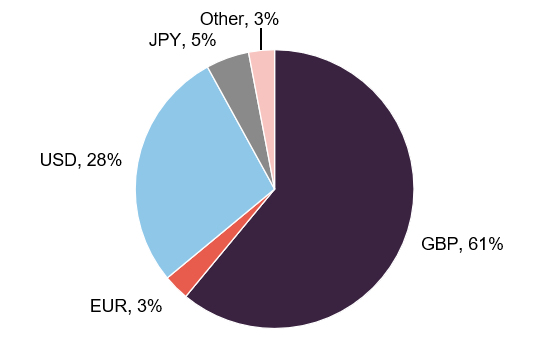
Figure 9: CGT’s currency exposure as at 30 November 2025
Source: Capital Gearing Trust
Figure 10: CGT’s duration and yield as at 30 September 2025
| Weight (%) | Duration (years) | Yield (%) | Rating | |
|---|---|---|---|---|
| Cash & TBills | 23 | 1.0 | 4.1 | A+ |
| I/L Bonds | 39 | 7.2 | 4.31 | AA |
| Corporate bonds | 11 | 3.2 | 5.8 | A/A- |
| Risk Assets (HY) | 1 | 1.1 | 9.0 | BB/BB- |
| Risk assets (other) | 26 | n/a | 5.0 | n/a |
| Total | 4.6 |
Source: Capital Gearing Trust. Note 1) 1.4% real yield
Largest underlying holdings
Figure 11: Largest equity and bond positions in the portfolio as at 30 November 2025
| Largest equity holdings | As at 30/11/25 (%) | Largest bond holdings | As at 31/10/25 (%) |
|---|---|---|---|
| North Atlantic Small Companies | 2.1 | UK Index-linked 0.125% 10/08/31 | 6.3 |
| Vanguard FTSE 100 ETF | 2.0 | JGB 0.60% 01/01/27 | 5.3 |
| International Public Partnership | 1.4 | UK Index-linked 0.75% 22/11/33 | 3.9 |
| JPMorgan Japan ETF | 1.2 | US Index-linked 0.125% 15/07/31 | 3.5 |
| BlackRock Energy | 1.2 | US Index-linked 0.175% 15/01/34 | 3.5 |
Source: Capital Gearing Trust
Within its risk asset portfolio, CGT made profits from several discount opportunities, including selling Fidelity Japan Values (FJV) after it was taken over and partially rolled into AVI Japan Opportunity Trust (AJOT). CGT had become a top shareholder in FJV when it failed to meet its single-digit discount target, expecting the board would need to act before the trust’s continuation vote due to weak performance.
CGT also took up recent cash exit offers from Mobius Investment Trust and Polar Capital Global Financials Trust. Positions in Aberdeen Asia Focus (AAS) and Fidelity Emerging Markets performed well this year. For AAS, CGT bought a large amount of convertible loan stock at good prices and benefited when that trust’s NAV rose enough to convert the loan stock into shares.
Crystal Amber was a significant holding, and as its managed wind-down nears completion, CGT has realised some profits. CGT has become less positive on renewables. When many renewable trust prices rose over the summer, the team sold holdings in The Renewables Infrastructure Group (TRIG), Greencoat UK Wind, and Foresight Solar, and reduced its position in Bluefield Solar Income Fund in June and July.
Despite rising share prices, the team grew sceptical about the stated NAVs of these companies, noting that assets in some managed wind-downs, such as Aquila European Renewables, were selling below their reported NAVs. These concerns contributed to the team’s opposition to HICL Infrastructure’s plan to acquire TRIG.
The team strongly supports CGT’s zero-discount model and suggests that a three-year stamp duty holiday for new IPOs could encourage new trusts to adopt this approach. While public campaigns like the one against the infrastructure merger are rare, most of the team’s efforts to push boards to address discounts and uphold discount promises happen privately.
The team has found about 90 investment companies that have either committed to narrowing discounts or offer an exit opportunity. Despite high valuations across many asset classes, these companies offer appealing options for the risk assets part of the portfolio.
Performance
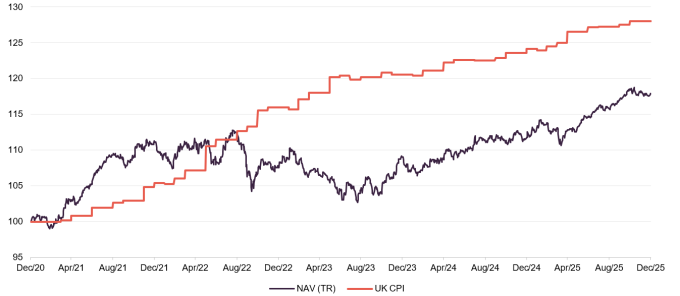
Figure 12: CGT NAV total return and UK inflation (CPI) over five years to end December 2025
Source: Bloomberg, Marten & Co
As Figure 13 shows, CGT has continued to protect and grow shareholders’ capital in real terms over the long term. It is also recovering against the inflation index following the sharp rise in inflation during 2021 and 2022.
Figure 13: Cumulative total returns for periods ended 31 December 2025
| 3 months | 6 months | 1 year | 3 years | 5 years | 10 years | |
|---|---|---|---|---|---|---|
| CGT price | 0.9 | 3.0 | 5.4 | 6.0 | 12.6 | 66.8 |
| CGT NAV | 0.8 | 2.9 | 5.4 | 9.6 | 17.9 | 69.1 |
| CPI | 0.4 | 0.6 | 3.1 | 10.4 | 28.0 | 39.4 |
| MSCI UK | 7.1 | 15.4 | 25.8 | 48.3 | 90.2 | 134.0 |
Source: Bloomberg, Marten & Co
Large-cap UK equities performed well in 2025, beating US indices when measured in sterling. CGT’s returns have been much less volatile than both UK and global indices, with a 10-year annualised standard deviation of 4.8%, compared to 15.1% for the MSCI UK Index and 15.2% for the MSCI World Index.
Over the 10 years to 31 December 2025, CGT’s largest monthly fall was 4.8%, compared to 13.5% for the MSCI UK Index and 10.6% for the MSCI World Index. The team highlights that during the “Liberation Day” market swings, CGT’s share price was only modestly affected. While the S&P 500 dropped over 12% between 2 and 8 April, CGT’s NAV remained stable and its discount did not widen, resulting in a drawdown of less than 2%.
Drivers of returns
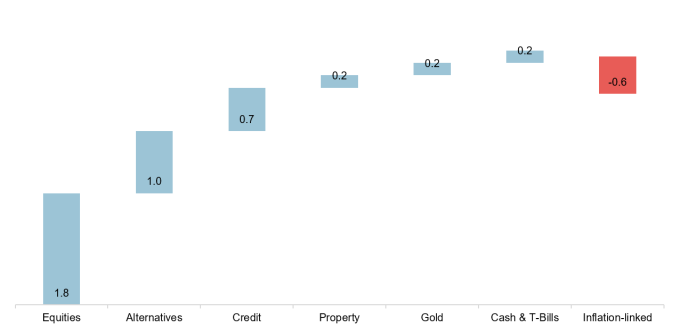
Figure 14 uses data from CGT’s recent interim results for the six months to 3 September 2025. Nearly all parts of the investment portfolio added to the trust’s NAV returns, except for inflation-linked bonds, which fell in value as yields rose, especially in the UK. This decline created a valuation opportunity, prompting a shift from US TIPS to UK index-linked bonds. The risk asset portion performed strongly, helped by narrowing discounts, with both equities and alternatives making significant contributions to CGT’s NAV growth.
Figure 14: Contributions to CGT’s NAV returns over the six months ended 30 September 2025
Source: Capital Gearing Trust
Premium/(discount)
The board believes shareholders should not have to face the risk of a wider discount. Since 2015, CGT has run a discount control policy, aiming to buy or issue shares so they trade close to NAV under normal market conditions.
At each AGM, shareholders are asked to approve issuing up to a third of CGT’s shares and buying back up to 14.99%. The board renews these permissions between AGMs if needed.
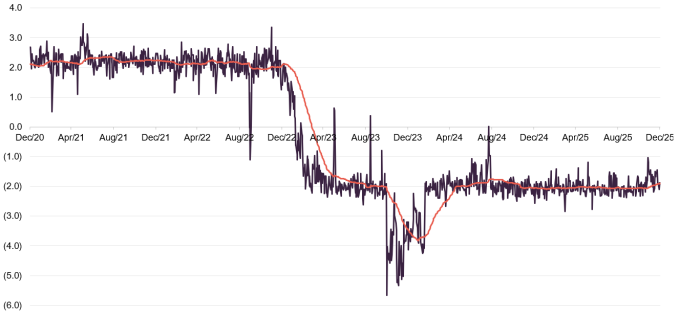
In the 12 months to 31 December 2025, CGT’s shares traded at discounts between 2.8% and 1%, averaging 2.0%. At publication, the shares were at a 1.9% discount.
Figure 15: CGT premium/(discount) over five years to end December 2025
Source: Bloomberg, Marten & Co
Previous publications
We published a number of notes on CGT between September 2018 and March 2020, which are available to view on the QuotedData website.
Our re-initiation note – Cautiously positioned in volatile markets – was published on 10 July 2025.
SWOT analysis
Figure 16: SWOT analysis for CGT
| Great long-term track record of meeting objectives |
| Longevity of manager tenure and his experience of a number of market cycles |
| Rigorous discount control |
| Shorter-term returns have been below inflation |
| Underweight to gold relative to some peers held back returns |
| As investors grow more nervous about stretched market valuations, CGT’s positioning could look attractive |
| Inflation may continue to run ahead of expectations, validating the team’s world view |
| Discount narrowing opportunities are available to add value for CGT investors |
| Most serious threat would be growing concern over UK/US default, which could weigh on bond prices |
| Risk-on environment may persist, and trust continues to shrink |
Source: Marten & Co
Bull vs bear case
Figure 17: Bull vs bear case for CGT
| Performance | CGT is clawing back the short-term underperformance of inflation and demonstrating its ability to add value in its risk assets exposure | Five-year figures will be impacted by the post-COVID run-up in inflation for a couple of years yet |
| Dividends | Not relevant | Not relevant |
| Outlook | Rising inflation, stable/rising interest rates, and cracks in the AI story could derail markets and favour CGT’s asset allocation | A prolonged extension of the current bull market could leave CGT trailing peers |
| Discount | Not relevant – which in itself is a bullish statement | Not relevant |
Source: Marten & Co
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Capital Gearing Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.