
Steady as he goes
CQS New City High Yield Fund (NCYF) has continued to deliver income from a diversified portfolio of higher-yielding credit, while aiming to preserve capital through bottom-up credit selection. Its current yield of around 9% is a potential attraction for some investors, particularly while inflation, interest rates and geopolitical risk continue to affect the market outlook.
Recent years have presented various challenges for credit markets, but NCYF’s NAV and share price total returns have remained stable. The planned transition of manager from Ian “Franco” Francis to Darren Toner is now underway. According to the company, Darren has 15 years of experience working closely with Franco and is familiar with NCYF’s process, portfolio, and underlying credits. Franco is expected to take on a consultancy role after he steps back in May 2027, with the intention that this should help smooth the transition.
High-dividend yield and potential for capital growth
NCYF aims to provide investors with a high-dividend yield and the potential for capital growth by investing mainly in high-yielding fixed interest securities. These include, but are not limited to, preference shares, loan stocks, corporate bonds (convertible and/or redeemable) and government stocks. The company also invests in equities and other income-yielding securities. The manager has a strong focus on capital preservation and is conservative in his approach to growing NCYF’s capital.
| 12 months ended | Share price TR (%) | NAV total return (%) | Libor/SONIA + 3% (%)1 | CPI + 4% (%) |
|---|---|---|---|---|
| 31/05/2022 | 6.3 | 6.6 | 3.4 | 8.4 |
| 31/05/2023 | (0.8) | (0.7) | 6.3 | 14.0 |
| 31/05/2024 | 16.9 | 18.0 | 8.3 | 9.3 |
| 31/05/2025 | 6.5 | 6.8 | 7.9 | 6.4 |
| 31/05/2026 | 8.9 | 9.5 | 7.0 | 7.4 |
Fund profile
Further information can be found at: ncim.co.uk
A predominantly higher-yielding fixed income exposure
NCYF aims to provide a high level of quarterly income, with the prospect of capital growth, by investing primarily in higher-yielding fixed income securities. It also has flexibility to invest in equities and equity-related securities.
The manager seeks securities that are undervalued by the market.
The manager typically seeks securities that it believes are undervalued and capable of generating income above the average relative to their risk, while also offering potential for capital appreciation. The manager also looks to exploit opportunities that may arise from market yield movements and corporate events, including redemptions, conversions, reconstructions and takeovers.
CQS Group and New City Investment Managers
NCIM has managed NCYF since its launch in March 2007.
New City Investment Managers (NCIM) has managed NCYF since its launch in March 2007, having also managed its predecessor, from 2004 until its assets were rolled into NCYF. NCIM joined CQS Group in October 2007. In November 2023, CQS was acquired by Manulife Investment Management, a global asset manager with US$1.3trn of assets under management and administration.
Manager transition underway as Darren Toner joins Franco
Franco will be available for three years after he steps back in May 2027.
On 21 May 2026, Darren Toner, a senior portfolio manager within Manulife | CQS Investment Management’s Multi Asset Credit business, was appointed co-manager of NCYF alongside longstanding manager Ian “Franco” Francis. The appointment is part of a planned succession process, under which Franco is expected to step back from portfolio management in May 2027, while remaining available as a consultant for around three years.
Darren joined CQS in 2010 and has worked with Franco for 15 years. NCYF’s manager says that this has provided Darren with a detailed understanding of NCYF’s strategy, process and portfolio. In recent years, he has been involved in portfolio management support, particularly in identifying and assessing potential investments and portfolio construction.
Shareholders may have some concern about Franco stepping back after a long tenure. Darren is already familiar with NCYF’s portfolio, underlying credits and established investment process. He will also continue to draw on the wider Manulife | CQS credit platform, including the team of asset class specialists and analysts that has supported Franco. There is a handover period and Franco will have an ongoing consultancy role. This change has been described as an evolution intended to preserve continuity rather than disrupt the investment approach.
Constructed without reference to a benchmark
Reflecting its fixed income focus, absolute return approach and diversified portfolio, NCYF is not managed against a benchmark. However, over the longer term, a case can be made that it should be capable of delivering positive real returns and returns above cash rates. Comparisons with LIBOR/SONIA +3% and CPI +4% have been included, although these are not formal benchmarks for the fund.
Manager’s view
Significant inflationary risks in the global economy
NCYF’s manager has long held the view that global inflation risks remain significant and that, in the event of disruption, inflation and interest rates could stay higher for longer than markets expect. The manager also indicated a cautiously constructive outlook entering 2026, noting that the UK economy was performing better than expected, with improving domestic and export demand.
Cost pressures remain an issue, particularly for labour-intensive sectors such as hospitality, following higher national insurance contributions and minimum wages, while supply-chain disruption remains an ongoing risk. Before the outbreak of war in Iran, the UK economy appeared to be showing resilience, with new orders improving across manufacturing and services. Persistent inflation above the Bank of England’s 2% target and softer labour market data were still limiting the Bank’s ability to cut rates.
Few obvious safe havens from effects of Iran war
The war in Iran changed the backdrop. Closure of the Strait of Hormuz, through which a significant share of global oil supply passes, appears to have affected energy markets, with Brent crude rising from just over $72 a barrel at the start of March to almost $104 by month-end. This appears to have influenced rates, credit, equities and currencies. UK gilts weakened, credit spreads widened, equities fell and sterling declined against the dollar, which seemed to reflect concerns that energy and trade disruption could keep inflation higher for longer.
For the UK, renewed inflationary pressure has appeared, while the economy remains fragile. Ian highlights what he sees as the Bank of England’s dilemma: tighter policy may be needed to curb inflation, but the economy may struggle with higher rates. Although the 10-year gilt yield has fallen back from its peak of 5.20% to 4.78%, and the 30-year yield remains around 5.5%, borrowing costs are still elevated and may constrain growth.
Europe faces a similar challenge. Early signs of recovery, led by German manufacturing, appear to have faded as higher input costs and conflict-related uncertainty seem to have weighed on activity and sentiment. Ian expects the ECB to keep rates unchanged until there is greater clarity on the conflict, inflation and the wider economic impact.
In the US, growth has also slowed. Manufacturing strength appears to have reflected front-loaded orders ahead of expected price rises, rather than a durable demand recovery. The Federal Reserve faces a similar situation to the Bank of England and ECB: inflationary pressure has risen, but underlying growth remains weak, which may make rate cuts difficult.
Volatility returns as inflation risks re-emerge
The managers expect volatility to remain elevated while markets assess the duration and economic impact of the conflict. Although the US and Iran have agreed to extend their ceasefire and reopen the Strait of Hormuz, relations appear to remain strained. Key facilities have been damaged, and it may take time to normalise traffic. This suggests that higher inflation and market volatility could persist for some time.
According to NCYF’s managers, volatility can create opportunities for high-yield investors. Some sectors, particularly those linked to oil, appear to have benefitted from the disruption. NCYF’s managers say that credit selection is especially important in this environment, and they are deploying capital where they believe pricing is attractive and the underlying credit risk is acceptable. For example, Frontline was reduced earlier this year after what the managers describe as strong performance, with part of the proceeds reallocated into a new equity position in Ithaca Energy.
Bottom up investment process
NCYF’s portfolio is constructed through a bottom-up process, based on detailed fundamental analysis of each investment’s credit risk and return potential. This analysis assesses free cash flow across the capital structure, including equity, debt, preferred stock and convertibles; the potential impact of changes in cash flow, interest rates or competitive pressures; the company’s track record in meeting obligations; and the quality of management.
The manager seeks securities that are considered undervalued and capable of generating income relative to their risk, with potential for capital appreciation if they rerate. According to the manager, income generation and sustainability are central to the process, and capital preservation is a key focus; the manager says that they are not prepared to sacrifice capital in pursuit of yield.
Low turnover portfolio
NCYF maintains a moderately concentrated portfolio. The top 10 holdings account for 25–30% of the portfolio.
The portfolio typically holds around 110–120 issues and is moderately concentrated, with the top 10 usually accounting for about 25%–30% of assets. The largest positions tend to be relatively liquid in normal market conditions. The manager maintains a core group of holdings that are described as well-understood, which is consistent with the portfolio’s low turnover, excluding called positions.
Given limited secondary-market liquidity in many holdings, investments are selected on the basis that they may offer risk-adjusted returns through to maturity, rather than as trading positions. Where holdings exit early, this is usually because they have been called by the issuer, often at a premium. Annual turnover is typically around 50%, although 30%–40% of this may reflect forced redemptions.
The portfolio typically has a relatively short duration of around three-and-a-half to four years, generates a geared return of about 8% per annum and pays a yield of around 7%. This has been achieved without using options or dividend stripping.
The manager does not hedge currency risk, but takes a macro view on currencies and avoids those it does not favour. For example, NCYF has not held any Australian dollar-denominated assets since 2014/15.
Exposure to niche issues and unrated bonds
The manager’s ability to assign internal credit ratings allows it to assess smaller, niche and unrated issues. These can offer a premium of around 150–200bps for an equivalent level of risk, which the manager says supports NCYF’s ability to generate risk-adjusted returns.
Investment restrictions
No defined limits on type of securities, countries, issue size or sectors.
Alongside fixed income securities, NCYF may invest in equities and other income-yielding securities. There are no formal limits by security type, country, issue size or sector, although exposure to any single investee company is limited to 5% of total investments. The fund may use derivatives, financial instruments, money market instruments and currencies for efficient portfolio management, and may invest in closed-ended and open-ended funds, subject to a 10% limit of total assets at the time of investment.
A maximum of 10% of total assets can be invested in collective investment vehicles.
NCYF may also invest up to 10% of total assets in securities that are neither listed nor traded, measured at the time of investment. This includes unlisted or unquoted securities that are expected to become convertible, at NCYF’s option, into listed or traded securities. Securities that subsequently cease to be listed or traded may also be retained where the manager considers this appropriate, subject to the same limit.
Gearing is currently limited to 25% of net assets by the board. This limit is reviewed periodically.
NCYF is permitted to borrow, with gearing capped at 25% of net assets at the time of borrowing and reviewed periodically by the board. The manager expects the portfolio to be normally fully invested, but may raise cash or increase exposure to money market instruments and derivatives when market conditions appear to warrant a more defensive stance.
Risk management
NCYF’s board monitors the spread of investments.
In addition to the investment restrictions outlined above, the board monitors portfolio diversification to seek to ensure that exposure to individual countries, sectors and other risk factors remains within set parameters. The manager also applies risk controls to monitor the portfolio and to quantify and manage market and other relevant risks.
Oversight is provided by the risk management and performance analysis team within CQS.
Manulife | CQS has a permanent risk management function, that is independent of the portfolio manager. Its risk management and performance analysis team is not involved in managing NCYF’s portfolio, and operates policies, processes and procedures to identify, measure, monitor, report on and manage material risks relevant to the fund’s strategy. Its systems include third-party applications such as Tradar, Sungard Front Arena and MSCI RiskMetrics, along with proprietary tools.
Asset allocation
As at 30 April 2026, NCYF’s portfolio had exposure to 96 issues, down from 99 a year earlier. As Figure 5 shows, the top 10 issues accounted for 35.7% of the portfolio, down from 38.2% at 30 April 2025. Figures 1 to 4 show the most recently available portfolio splits by asset class, fair value hierarchy, sector and currency.
NCYF has no exposure to utilities, which the manager attributes to long-standing concerns over dividend sustainability in the sector.
Exposure to communication services is present. Although the sector has featured previously, the manager believes selectivity is essential given its exposure to high leverage, significant capex requirements, rapid technological change and regulatory risk.
Figure 1: NCYF portfolio split by asset class at 30 April 2026
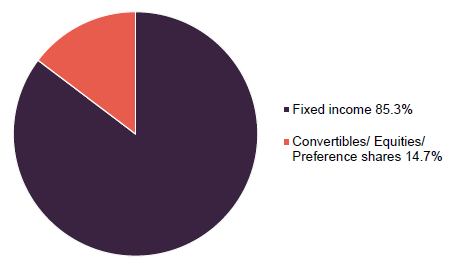
Figure 2: NCYF portfolio split by Fair value hierarchy at 31 December 20251
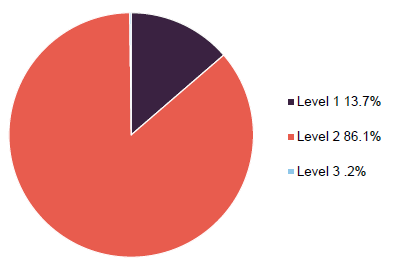
Figure 3: NCYF portfolio split by sector at 31 December 2025
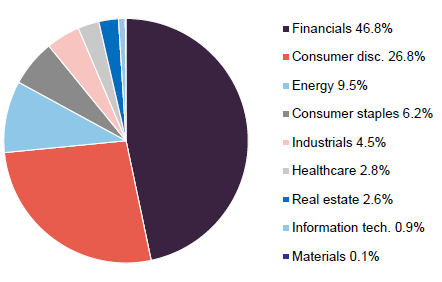
Figure 4: NCYF portfolio split by currency at 30 April 2026
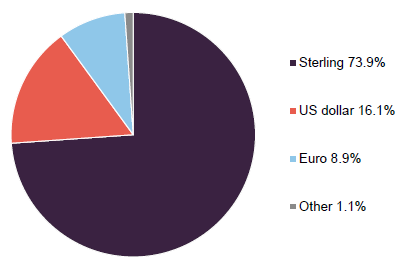
These charts illustrate several themes. The portfolio is primarily invested in fixed income securities, with almost all holdings either quoted in an active market or valued using observable market prices. Approximately 7% of the portfolio trades OTC and may be less liquid, even in normal conditions.
The portfolio is diversified by sector, but has a significant weighting to financials, which the manager attributes to a positive view of selected bank and insurance issues. It is predominantly sterling-denominated, at around 74%, with a US dollar exposure of around 16%, and is entirely invested in developed market currencies.
NCYF’s investments are mainly located in developed jurisdictions that, according to the manager, are currently supportive of businesses.
Top 10 holdings
Figure 5 shows NCYF’s top 10 holdings as at 30 April 2026 and the changes over the preceding year. The manager’s long-term, low-turnover approach may explain why most of the issuers remain consistent with previous portfolio announcements. There appears to have been limited change in the concentration of the largest holdings. Some of the developments are discussed over the following pages. Readers interested in other top 10 names may wish to refer to previous notes, where many have been covered in more detail.
Figure 5: Top 10 holdings as at 30 April 2026
| Holding/issue | Sector | Portfolio weight 30 April 2026 (%) | Portfolio weight 30 April 2025(%)1 | Percentage point change |
|---|---|---|---|---|
| Shawbrook Group 22-08/06/2171 FRN | Banks | 4.7 | 5.1 | (0.4) |
| Stonegate Pub 10.75% 24-31/07/2029 | Restaurants & bars | 4.5 | 3.3 | 1.2 |
| TVL Finance 10.25% 23-28/04/2028 | Hotels | 4.1 | 3.9 | 0.2 |
| RL Finance No6 23-25/11/2171 FRN | Insurance | 3.9 | 4.2 | (0.3) |
| Sherwood Financing 9.625% 24-15/12/2029 | Asset managers | 3.8 | 1.2 | 2.6 |
| Bellis Acquisition 8.125% 24-14/05/2030 | Grocery retail | 3.2 | 1.2 | 2.0 |
| Cidron Aida Finco 9.125% 25-27/10/2031 | Pharmaceutical | 3.2 | – | 3.2 |
| Barclays Plc 22-15/12/2170 FRN | Banks | 2.9 | 3.3 | (0.4 |
| Wheel Bidco 9.875% 21-15/09/2029 | Restaurants & bars | 2.9 | – | 2.9 |
| 888 Acquisitions 10.75% 24-15/05/203 | Gambling & Casinos | 2.7 | – | 2.7 |
| Total of top five | 20.8 | 21.9 | (1.1) | |
| Total of top 10 | 35.7 | 38.2 | (2.5) |
Shawbrook Group 22-08/06/2171 FRN – additional Tier 1 capital
Figure 6: Shawbrook Group 2171 bond price
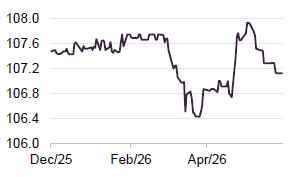
Shawbrook Group (shawbrook.co.uk) is a UK specialist bank focused on selected areas of SME and consumer lending, including specialist mortgages, business finance, asset finance and savings. NCYF has held Shawbrook bonds for several years, reflecting the manager’s familiarity with the credit and the manager’s stated confidence in the bank’s lending model, capital position and management team.
The current holding is a sterling Additional Tier 1 security, which is a deeply subordinated bank-capital instrument rather than a conventional senior bond. It is effectively perpetual and may be called by Shawbrook at specified dates, subject to regulatory approval, but there is no obligation to redeem it. In return for accepting this subordination, extension risk and the potential for coupons to be cancelled in stress scenarios, investors receive a coupon that is currently just over 12%.
Stonegate Pub 10.75% 24-31/07/2029 – significant asset backing
Figure 7: Stonegate Pub 10.75% 2029 bond price
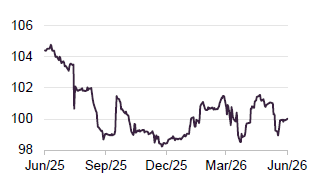
Stonegate Group (stonegategroup.co.uk) is the UK’s largest pub company, operating more than 4,500 pubs, bars and venues across community pubs, traditional inns, high-street bars and late-night venues. Its brands include Slug & Lettuce and Be At One, alongside a large leased and tenanted estate.
Stonegate bonds have been included in NCYF’s portfolio for an extended period. The manager believes the group’s extensive property portfolio provides significant asset backing, and that its scale leaves it well placed to benefit from sector consolidation. The current holding is a sterling senior secured bond issued as part of Stonegate’s 2024 refinancing, which was supported by a £250m equity contribution from its private equity owner, TDR Capital.
Stonegate remains exposed to wage inflation, energy and food costs, business rates, changing consumer spending and a sizeable debt burden. However, NCYF’s manager believes the group is well managed and that these risks are compensated for by the bond’s yield, senior secured ranking and asset backing.
TVL Finance 10.25% 23-28/04/2028 – benefits from scale in the budget hotel segment
Figure 8: TVL Finance 10.25% 2028 bond price
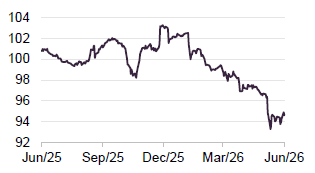
TVL Finance is the financing vehicle for Travelodge (travelodge.co.uk), one of the UK’s largest budget hotel operators, with an estate across the UK, Ireland and Spain. The business has a well-known brand, scale in the budget segment and exposure to both leisure and business travel. Its ongoing hotel refit programme, which had upgraded more than two-thirds of its room estate by the end of 2025, and international expansion, including 21 hotel openings during 2025, may also support trading.
The holding is a sterling senior secured bond with a 10.25% coupon and 2028 maturity. According to NCYF’s manager, the appeal is the high income, secured ranking and exposure to a large, recognisable operator in the value-focused hotel market. The shorter maturity may create some refinancing risk, although Travelodge’s debt profile appears to be reasonably spread, with £415m of senior secured notes due April 2028, €250m of floating-rate notes due June 2030 and a £50m revolving credit facility maturing in October 2027.
RL Finance No6 23-25/11/2171 FRN – Tier 1 capital
Figure 9: RL Finance FRN bond price
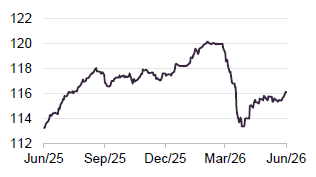
RL Finance Bonds No.6 is a financing vehicle for The Royal London Mutual Insurance Society, one of the UK’s largest mutual life, pensions and investment groups. The bond is a sterling Restricted Tier 1 insurance-capital security, making it a deeply subordinated perpetual instrument rather than a conventional corporate bond. Royal London may call the bond at specified dates, subject to regulatory approval, but is not obliged to redeem it. The instrument is designed to support Royal London’s Solvency II capital position and absorb stress if that position deteriorates. For NCYF, the bond provides income from a large UK mutual insurer, with underlying activities that may be considered defensive. This is accompanied by the complexity and risk associated with subordinated financial debt, which is explicitly designed to absorb losses under stress.
Sherwood Financing 9.625% 24-15/12/2029
Figure 10: Sherwood Fin. 9.625% 2029 bond price
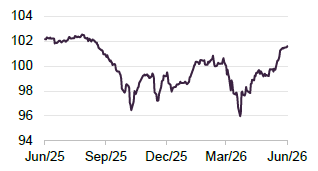
This sterling senior secured high-yield bond is issued by Sherwood Financing Plc, part of Sherwood Parentco/Arrow Global. It sits alongside €1.065bn of floating-rate senior secured notes due 2029 and €300m of 7.625% fixed-rate senior secured notes due 2029.
Arrow Global is a European alternative asset manager and credit investor, backed by TDR Capital, with a focus on credit and real estate opportunities, including performing and non-performing loan portfolios. Its capital-light, fee-based model may be sensitive to funding costs, collections performance, asset valuations, economic conditions and investor appetite for private and opportunistic credit strategies.
The bond is rated single B by Fitch, which affirmed the rating on 22 May 2026, with a stable outlook for Sherwood Parentco Limited, reflecting the group’s 2029 debt stack, including the euro floating-rate notes, euro 7.625% notes and sterling 9.625% notes.
Performance
NCYF’s NAV and share price total returns were ahead of LIBOR/SONIA +3% and CPI +4%, until inflation re-emerged and interest rates rose. This was first apparent after Russia’s invasion of Ukraine and the 2022 UK “mini-budget”, both of which appear to have affected sentiment towards bonds and income-producing assets.
Figure 11: NCYF’s NAV and share price total return versus Libor/SONIA + 3% and CPI +4%, rebased to 100 over five years to 31 May 2026
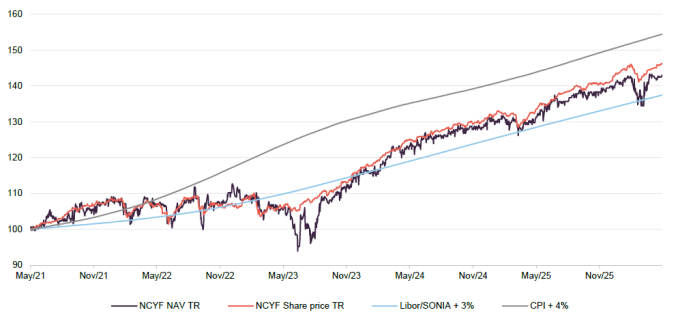
Performance began to recover from July 2023, as markets appeared to rally on signs of cooling US inflation and expectations that major economies could avoid a severe recession. This also suggests the tendency of bonds to pull back to par as they mature. Similar – but shorter-lived – disruptions are visible around the time of President Trump’s tariff announcements in April 2025 and, more recently, the outbreak of war in Iran.
Over five years, NCYF’s NAV and share price total returns are ahead of LIBOR/SONIA +3%, having recovered their earlier underperformance. They have also broadly kept pace with CPI +4%, although they have not yet fully recovered the underperformance experienced during 2022 and the first half of 2023.
Although all of NCYF’s peers are fixed-income-focused, most do not share its emphasis on high income. As Figure 12 shows, NCYF’s NAV appears to have outperformed the peer group average over most periods up to five years. The data is similar for the share price, which has also modestly outperformed the peer group average over 10 years.
Figure 12: Cumulative total return performance over periods ending 31 May 2026
| 1 month (%) | 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | 10 years (%) | |
|---|---|---|---|---|---|---|---|
| NCYF NAV | 1.0 | 0.1 | 4.0 | 9.5 | 38.1 | 46.2 | 64.0 |
| NCYF share price | (0.2) | 0.2 | 3.4 | 8.9 | 35.6 | 43.0 | 99.8 |
| Libor/SONIA + 3%1 | 0.6 | 1.7 | 3.4 | 7.0 | 25.1 | 37.5 | 63.2 |
| CPI + 4% | 0.6 | 1.7 | 3.5 | 7.4 | 25.0 | 54.5 | 104.0 |
| Peer group average NAV | 0.8 | 0.8 | 2.7 | 7.5 | 37.4 | 37.6 | 88.8 |
| Peer group average share price | 0.9 | (0.4) | 1.8 | 6.4 | 40.8 | 39.2 | 99.5 |
Peer group
Please click here to visit QuotedData.com for a live comparison of the Debt – Loans and bonds peer group.
NCYF is a member of the AIC’s debt – loans & bonds sector, which comprises five members, as illustrated in Figures 13 and 14. This peer group appears to have decreased in size in recent years as a number of funds have been wound up or merged. Members of Debt – Loans & Bonds typically have over 80% invested in general debt instruments such as secured loans and bonds and syndicated lending, and an investment objective/policy to invest in general debt instruments such as secured loans and bonds and syndicated lending.
As noted in the performance section above, NCYF’s approach differs from that of its peers, which have less focus on generating high levels of income than NCYF.
NCYF’s was impacted more than the peer group average during the COVID-related market sell-off in March 2020, which continues to influence the 10-year numbers, although it subsequently recovered. It was also affected by bond market conditions in 2022 and the first half of 2023. Over the majority of time periods shown in the table, NCYF ranks in the top half of its peer group, with its three-month figure possibly affected by the rise in inflation expectations following the outbreak of war in Iran.
Figure 13: Peer group cumulative NAV total return performance to 31 May 2026
| 1 month (%) | 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | 10 years (%) | |
|---|---|---|---|---|---|---|---|
| NCYF | 1.0 | 0.1 | 4.0 | 9.5 | 38.1 | 46.2 | 64.0 |
| CVC Income & Growth GBP | 0.6 | 0.4 | 2.6 | 8.1 | 31.4 | 21.8 | 74.5 |
| Invesco Bond Income Plus | 0.7 | 2.0 | 2.3 | 5.9 | 42.9 | 53.0 | 105.9 |
| M&G Credit Income | 0.0 | 0.6 | 1.7 | 4.9 | 24.4 | 28.1 | N/A |
| TwentyFour Select Monthly Income | 1.5 | 0.8 | 2.8 | 9.1 | 50.3 | 38.9 | 110.8 |
| NCYF rank | 2/5 | 5/5 | 1/5 | 1/5 | 3/5 | 2/5 | 4/4 |
| Sector arithmetic avg. | 0.8 | 0.8 | 2.7 | 7.5 | 37.4 | 37.6 | 88.8 |
| Sector arithmetic avg. exc. NCYF | 0.7 | 0.9 | 2.3 | 7.0 | 37.3 | 35.4 | 97.1 |
Figure 14: Peer group comparison – size, fees, discount, yield and gearing as at 12 June 2026
| Market cap (£m) | St. dev. of NAV returns over 1 year | Ongoing charges (%) | Perf. fee | Premium/ (discount) (%) | Dividend yield (%) | Gross gearing (%)1 | Net gearing (%)1 | |
|---|---|---|---|---|---|---|---|---|
| NCYF | 349 | 7.38 | 1.17 | No | 5.2 | 8.9 | 12.5 | 11.8 |
| CVC Income & Growth GBP | 79 | 4.51 | 1.66 | No | (0.8) | 6.84 | 2.0 | 2.0 |
| Invesco Bond Income Plus | 224 | 10.11 | 1.66 | No | 0.5 | 8.36 | 12.0 | 22.3 |
| M&G Credit Income | 480 | 3.73 | 0.88 | No | 1.6 | 7.08 | Nil | (1.8) |
| TwentyFour Select Monthly Income | 189 | 5.63 | 1.18 | No | 0.7 | 8.28 | Nil | (0.8) |
| NCYF rank | 2/5 | 3/5 | 3/5 | 1/5 | 1/5 | 5/5 | 4/5 | |
| Sector arithmetic avg. | 270 | 7.50 | 1.28 | 1.4 | 8.0 | 5.3 | 6.7 | |
| Sector arithmetic avg. exc. NCYF | 255 | 7.52 | 1.30 | 0.6 | 7.8 | 3.5 | 5.4 |
NAV total returns have tended to exceed the peer group average, which suggests that its high yield does not appear to have come at the expense of total return.
NCYF is one of the largest funds in the peer group, ranking second by market capitalisation even after combining the two CVC Credit Partners European Opportunities share classes. Its above-average rating – currently the highest premium in Figure 14, and typically among the top two in the peer group – appears to be a result of its consistently high yield.
NCYF’s ongoing charges are below the sector average, which may reflect its size. The only fund with a lower OCR is M&G Credit Income, which is also the only peer group fund larger than NCYF. If NCYF continues to grow as it has in recent years, its OCR may continue to decrease, assuming other factors remain unchanged. Like most funds in the peer group, NCYF does not charge a performance fee.
NCYF has the second-highest level of net gearing in the sector. However, the underlying strategies appear to be relatively stable, which should be helpful to these funds if they use gearing. If interest rates fall and capital values rise, NCYF could benefit from its higher market exposure, although the reverse may also be true.
NCYF’s NAV return volatility is below the sector average. This may be notable given its higher-yield focus and might suggest that the additional yield has not been accompanied by higher volatility.
Quarterly dividend payments
The total annual dividend has increased every year since launch.
Subject to market conditions, performance and its financial position, NCYF aims to pay a quarterly dividend, with all dividends paid as interims.
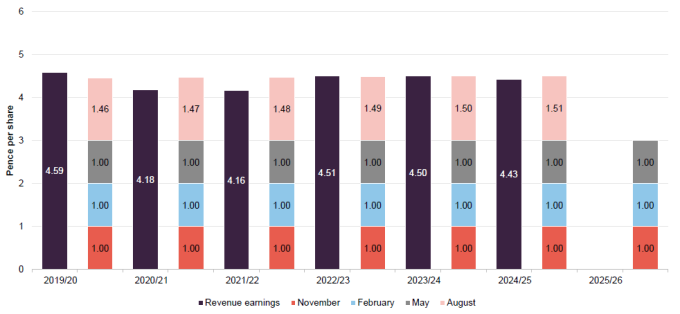
For each financial year, the first interim is paid in November, with the second, third and fourth paid in February, May and August. As Figure 15 shows, the first-quarter dividend rate is generally maintained for the second and third interims, followed by a larger fourth-quarter “balloon” payment. Although not a formal policy, NCYF’s total annual dividend has increased every year since launch.
Over half a year’s worth of dividends in reserve
The board avoids issuing stock close to ex-dividend dates to protect NCYF’s revenue reserve.
Over the longer term, revenue earnings have generally exceeded dividends, which has allowed NCYF to build a revenue reserve. The board may draw on this during periods of shortfall, as occurred in FY2021 and FY2022, and marginally in FY2025. As at 31 December 2025, the revenue reserve stood at 2.26p per share, equivalent to 58% of the total FY2025 dividend. The board states that it is mindful of the dilutive impact of share issuance on the revenue reserve and avoids issuing shares close to ex-dividend dates.
In its interim results for the half year ended 31 December 2025, the board said that, as things stand, it expects to follow the same dividend payment pattern as last year and maintain or slightly increase the total dividend for the year.
Figure 15: NCYF revenue income and dividend by financial year (ended 30 June)
Premium/(discount)
Figure 16: NCYF premium/(discount) over five years to end May 2026
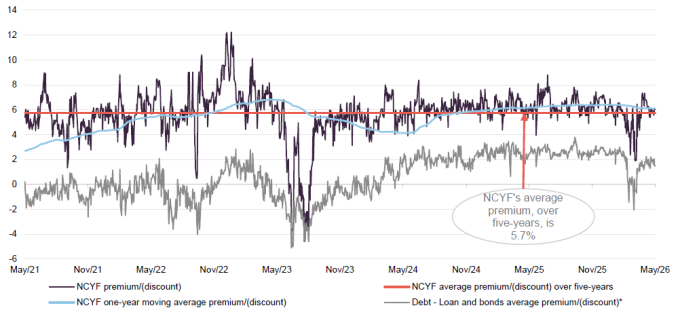
As Figure 16 shows, NCYF has traded predominantly at a premium over the past five years, typically within a 0%–10% range and averaging 5.7%.
Demand for the strategy has supported continued share issuance. In the 12 months to 31 May 2026, NCYF issued 76m shares, increasing its issued share capital by 12.5%. Issuance is accretive to existing shareholders, as NCYF generally issues shares only when the premium exceeds 5%–6%. NCYF’s manager says that this approach allows the fund to grow in a measured way, with care taken to avoid diluting the revenue account; new issuance must generate sufficient income to cover itself before the next ex-dividend date. NCYF has also consistently traded at a premium to the debt – loans and bonds sector average, and this appears to remain the case.
Structure
Fees and costs
NCYF has a tiered management fee.
The manager receives an annual fee of 0.8% of total assets, less current liabilities excluding bank borrowings, up to £200m; 0.7% between £200m and £300m; and 0.6% above £300m. The fee is paid monthly in arrears, with no performance fee, and the agreement is terminable by either party on 12 months’ notice.
BNP Paribas Securities Services S.C.A. provides company secretarial and administrative services, and also acts as custodian, banker and depositary. Secretarial and administration fees were £244,000 for the year ended 30 June 2025, compared with £214,000 in 2024. Bank and custody fees were £69,000, compared with £66,000, while depositary fees were unchanged at £45,000.
Allocation of fees and costs
Figure 17: NCYF Ongoing charges ratio (%)1
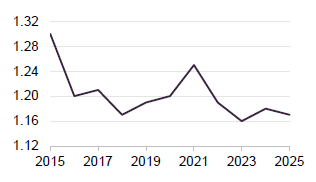
NCYF allocates investment management fees 40% to capital and 60% to revenue. Its ongoing charges ratio was 1.17% for the year ended 30 June 2025, compared to 1.18% in 2024 and 1.16% in 2023.
As Figure 17 shows, the broader trend over the past decade appears to have been lower ongoing charges, which appears to have been supported by growth in net assets from share issuance. The main exceptions were FY2015, during the Greek debt crisis and wider market turbulence, and the COVID period, when higher bond yields appear to have depressed capital values.
Further share issuance may continue to put downward pressure on the ongoing charges ratio, while falling interest rates over the past two years appear to have supported capital values. However, renewed inflationary pressure and the potential for higher rates could weigh on asset values in the near term.
Capital structure and life
Simple capital structure
NCYF has one class of ordinary share in issue.
NCYF has a simple capital structure, with a single class of ordinary shares listed on the premium segment of the London Stock Exchange. As at 16 June 2026, there will be 690,451,858 shares in issue, with none held in treasury. NCYF has a retail presence on its share register, with platforms accounting for over 60%.
The board has set a borrowing limit equal to 25% of NCYF’s net assets. NCYF has a £50m loan facility with BNP Paribas, London Branch.
NCYF is permitted to borrow, with the board setting and regularly reviewing gearing limits to ensure they remain appropriate. As at 30 June 2025, the maximum gearing limit was 25% of net assets. The company has a £50m loan facility with BNP Paribas, London Branch, priced at a 1.40% margin over the daily non-cumulative compounded risk-free rate. The facility expires on 18 December 2026 and carries a 0.45% commitment fee on the undrawn balance. As at 30 April 2026, NCYF’s gearing was 12.6%.
The facility includes covenants covering minimum NAV, loan-to-value, indebtedness cover and restrictions on additional borrowings, all of which NCYF has met.
Unlimited life with an annual continuation vote
NCYF has no fixed winding-up date, but shareholders vote annually on its continuation as an investment company. If the ordinary resolution is not passed, the board would bring forward proposals to liquidate, reconstruct or reorganise the company.
Financial calendar
NCYF’s year-end is 30 June. Annual results are typically released in October, interims in March, and AGMs are held in November. The company pays quarterly dividends in November, February, May and August.
Board
NCYF’s board comprises five independent non-executive directors, with no shared directorships outside the company. Aggregate directors’ fees are capped at £250,000 per annum under the articles of association, and all directors stand for re-election annually.
Director’s average length of service is 5.6 years.
The board’s average tenure is 5.6 years, although three directors – Ian Cadby, John Newlands and Caroline Hitch – have now served for more than eight years. Board policy limits service to nine years, except in exceptional circumstances, and a succession plan is in place to support refreshment. Based on current tenures, this may be a focus over the next couple of years, with the nomination committee also incorporating diversity targets into its plans.
At the time of writing, the board has a 60/40 gender split, with a woman serving as chair and men holding the next two senior roles; audit committee chair and senior independent director. The board is currently entirely white British or white other, and acknowledges that it falls short of the target of at least one director from a minority ethnic background. The board says that this, alongside knowledge and expertise, will be a key consideration in its next recruitment process.
As Figure 18 shows, all directors have personal investments in NCYF. The chair’s holding is worth more than two years of her fees. Three directors bought NCYF shares over the past 12 months: Andrew Dann purchased 25,000 shares at 51.892p on 27 June 2025, Caroline Hitch bought 50,000 shares at 50.415p on 8 April 2026, and Joanne Dentskevich bought 39,180 shares on 21 May 2026 at 50.499p. No directors sold shares during the period.
Figure 18: Board member – length of service and shareholdings
| Director | Position | Date of appointment | Length of service (years) | Annual fee (£)1 | Share-holding2 | Years of fee invested3 |
|---|---|---|---|---|---|---|
| Caroline Hitch | Chair | 16 March 2018 | 8.3 | 50,000 | 261,500 | 2.7 |
| Andrew Dann | Chair of the audit and risk committee | 1 February 2025 | 1.4 | 44,000 | 25,000 | 0.3 |
| Ian Cadby | Senior independent director, chair of the nomination committee and chair of the remuneration committee | 18 January 2017 | 9.4 | 37,500 | 25,000 | 0.3 |
| John Newlands | Chair of the management engagement committee | 5 October 2017 | 8.7 | 37,500 | 10,000 | 0.1 |
| Joanna Dentskevich | Director | 1 February 2026 | 0.4 | 37,500 | 39,180 | 0.5 |
| Average (service length, annual fee, shareholding, years of fee invested) | 5.6 | 41,300 | 72,136 | 0.8 |
Caroline Hitch (chair)
Caroline has worked in financial services since the early 1980s, including 24 years with HSBC Group in London, Jersey, Monaco and Hong Kong. Her roles focused on multi-asset and institutional global fixed income portfolios, with a particular interest in transparency and governance, and included a period as head of wealth portfolio management at HSBC Global Asset Management (UK) Ltd. Prior to HSBC, she worked at James Capel and Standard Chartered. Caroline is also a director of Schroder Asian Total Return Investment Company Plc and Standard Life Equity Income Trust Plc, and holds a degree in economics from the University of Cambridge.
Andrew Dann (chair of the risk and audit committee)
Andrew has more than 40 years’ experience advising local and international financial services clients, including regulated funds, fiduciary businesses and investment management structures. He spent almost 38 years as managing partner of Ernst & Young Channel Islands before becoming chairman. He has been a Fellow of the Institute of Chartered Accountants in England and Wales since 1987, and is a member of both the Institute of Directors and the Association of Investment Companies’ Channel Islands Committee.
Ian Cadby (senior independent director, chair of the nomination committee and chair of the remuneration committee)
Ian has more than 27 years’ experience as a board executive and investment manager in the hedge fund and derivatives trading industry, across Asia, the US, the UK and Jersey. He also has extensive experience in board strategy, corporate governance and risk management. He was formerly CEO of Ermitage Ltd and has held senior roles at Cadby Wauton, Regent Pacific and Citibank. A Jersey resident, Ian is founder and group CEO of fintech business Sequential Ermitage Limited and co-founder and CEO of its wholly-owned subsidiary, Tiller Investments Limited. Ian holds a Combined Science degree from Coventry University and has completed the Advanced Management Programme in Business/Finance at Harvard Business School. He is also a director of Aberdeen Asian Income Fund Limited.
John Newlands (chair of the management engagement committee)
Following a 26-year career in the Royal Navy, John moved into the City in 1995. He was most recently head of investment companies research at Brewin Dolphin from 2007 until his retirement in 2017, having previously held roles at Greig Middleton and Williams de Broë. He also founded Newlands Funds Research in 2003 and was a member of the Association of Investment Companies’ Statistics Committee from 2000 to 2017. John has an MBA from Edinburgh University Business School and is a Chartered Engineer, having gained a degree in Electrical and Electronic Engineering from the University of Brighton. He is a member of Durham Cathedral’s investment committee and has written four books on financial history, the latest covering Dunedin Income Growth Investment Trust.
Joanna Dentskevich (director)
Joanna has more than 35 years’ experience in risk, finance and investment banking, gained across global banks, alternative investments and the offshore funds industry. She was previously a director at Morgan Stanley, where she headed its customer valuations group, director of risk at Deutsche Bank, and chief risk officer of London-based hedge fund Allometry Capital. She has also served as a non-executive director of GCP Asset Backed Income Fund Ltd and EJF Investments Ltd. Joanna holds a BSc (Hons) in Maths and Accounting from Oxford Brookes University.
Previous publications
Figure 19: QuotedData’s previously published notes on NCYF
| Title | Note type | |
|---|---|---|
| “Conservative and boring” | Initiation | 28 March 2018 |
| Escalators do not go to the sky! | Update | 13 November 2018 |
| Same as it ever was… | Annual overview | 29 July 2019 |
| Sitting pretty | Update | 30 June 2020 |
| A short-term opportunity? | Annual overview | 15 April 2020 |
| Interest rate rises maybe too little, too late | Update | 17 May 2022 |
| Riding the wave of shifting interest rates | Annual overview | 19 June 2024 |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on CQS New City High Yield Fund Limited.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have
regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.