
The long and short of emerging markets
Fidelity Emerging Markets Limited (FEML) gives investors access to a wide range of emerging market shares. The managers have a flexible approach, investing in companies of all sizes and spreading investments across different countries and sectors. A key feature is the use of both long and short positions, allowing the fund to benefit from opportunities in both strong and weaker companies.
Performance has been strong over the past year, supported by favourable conditions for emerging markets. The discount to net asset value (NAV) has also narrowed, and there is potential for it to reduce further if investor sentiment improves.
Long-term capital growth from emerging markets
FEML aims to achieve long-term capital growth from an actively managed portfolio made up primarily of securities and financial instruments providing exposure to emerging market companies, both listed and unlisted.
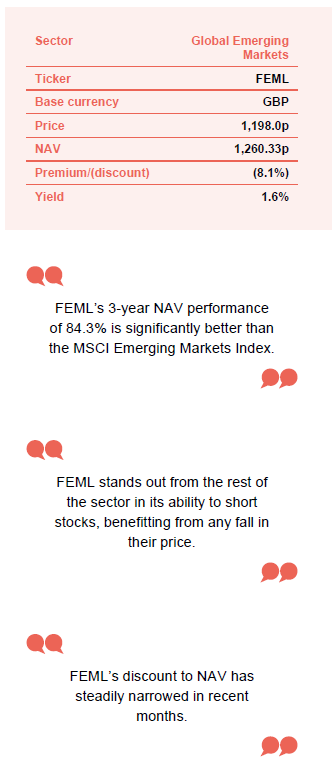
At a glance
Share price and discount
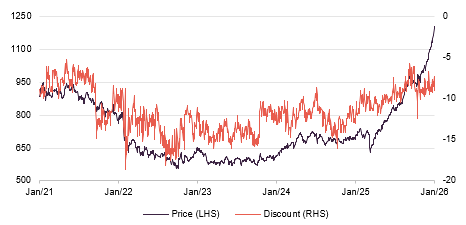
FEML’s share price rose significantly over 2025. Although this was partly due to the rally in emerging markets, there was also very strong outperformance of the MSCI Emerging Markets Index. The discount to NAV has also continued to narrow.
Performance over five years
Fidelity took over management of FEML in October 2021. Performance initially struggled, but has been very strong during the last year, with both the NAV and the share price outperforming the MSCI Emerging Markets Index by a significant margin.
Time period 31/01/2021 to 30/01/2026
Time period 31/01/2021 to 30/01/2026
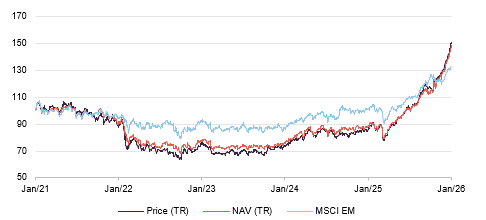
| Year ended | Share price total return (%) | NAV total return (%) | MSCI Emerging Markets total return (%) | MSCI World total return (%) |
|---|---|---|---|---|
| 31/01/22 | (10.0) | (8.3) | (5.1) | 19.4 |
| 31/01/23 | (16.9) | (15.8) | (3.9) | 1.4 |
| 31/01/24 | (1.3) | (1.9) | (5.6) | 14.0 |
| 31/01/25 | 18.7 | 17.8 | 17.7 | 24.5 |
| 30/01/26 | 71.2 | 59.6 | 30.4 | 9.1 |
Fund profile
Fidelity took over management of the trust in October 2021.
FEML, launched in 1989, invests in emerging and select frontier markets to achieve long-term capital growth. In October 2021, Fidelity International became manager, and the trust was renamed from Genesis Emerging Markets Fund. Since then, it has used Fidelity’s global analyst network to build a focused portfolio of long positions in quality companies and selective short positions. The trust mainly invests in listed companies and can use derivatives, giving managers additional ways in which they express their views and manage the portfolio’s risk, beyond just holding equities.
Nick Price leads the portfolio, with Chris Tennant as comanager since Fidelity’s appointment. Both are experienced in emerging markets and use Fidelity’s team of around 50 analysts to find opportunities and monitor risks. They follow a disciplined investment process that is focused on undertaking detailed research into individual stocks.
The managers use an “extension” approach, combining long positions in strong businesses with short positions in weaker ones, sometimes using pair trades. This can help hedge (offset) risk and add returns. Gross market exposure can exceed shareholders’ funds, but net equity exposure usually stays close to 100% of net assets. The portfolio is diversified by market cap and sector, with the long book focused on companies generating steady cash at reasonable valuations.
FEML’s benchmark is the MSCI Emerging Markets Index. While stock selection is bottom-up, the managers consider index country weightings.
For investors wanting a research-driven, high-conviction approach to emerging markets in a closed-ended fund, FEML stands out from traditional long-only peers. Its mix of active stock selection, selective shorting and gearing aims to capture emerging market growth while reducing volatility.
Manager’s view & current themes
Multi-country emerging markets funds typically hold a diverse mix of companies across sectors and regions. Although the portfolio is built from the bottom up, several clear themes run through its holdings.
Artificial intelligence
The recent global equity rally has mainly been fuelled by enthusiasm for artificial intelligence (AI), especially among large US technology companies known as the “Magnificent Seven.” However, less attention has been given to the important role emerging markets play in AI supply chains. Taiwan Semiconductor is a key example of this trend.
Companies like Elite Material, which makes copper-clad laminates for printed circuit boards, are often valued more attractively further down the supply chain. While Taiwan’s technology-focused stock market is cheaper than the US, it is usually pricier than other emerging markets. The sharp market drop after “Liberation Day” in April, when President Trump announced major tariffs, created a good buying opportunity as the market hit its daily trading limit several times. Since then, the market has recovered strongly.
Gold and copper
Nick and Chris believe the current market is favourable for both gold and copper. Gold benefits from strong demand from retail buyers and central banks, especially with ongoing geopolitical tensions. Gold miners are attractive, as their costs remain contained due to weak oil prices. Copper prices are supported by its key role in the energy transition and limited supply.
Gold prices have risen sharply since early 2024, significantly boosting FEML’s performance. Nick and Chris have adjusted their gold holdings, taking profits from strong performers and reinvesting in those that have lagged. They believe FEML’s gold companies remain appealing, even if gold prices fall, because of their low valuations.
Copper prices also rose in 2025, though less dramatically. Growth in data centres, driven by artificial intelligence, has increased demand for copper, while supply remains tight.
China
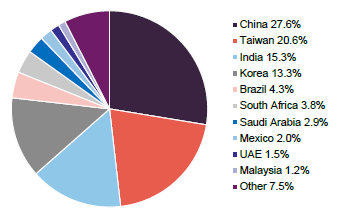
China is the largest emerging market and the biggest part of the index (see Figure 3). FEML’s managers avoid Chinese banks, citing low profit margins, weak earnings, and concerns about asset quality. Instead, they prefer leading technology companies in industrials and some consumer businesses, such as music streaming. The main Chinese exposure is through Naspers, a South African-listed company with a major stake in Tencent, a leading Chinese internet firm.
Financials
FEML’s managers say that their investment in the financial sector is not based on predicting interest rate movements. Some companies in the portfolio, like fintech firms, benefit from lower rates, while others, such as Indonesian banks, perform better when rates are higher.
The investments aim to capture long-term growth trends. Holdings in Indian and Indonesian banks offer exposure to the expanding middle class in markets where many companies are already highly valued. In contrast, Hungarian and Greek banks are held because they trade at lower prices than their peers and historical averages, mainly due to their location rather than their financial health.
Investment process
Nick and Chris also run the open-ended Fidelity FAST Emerging Markets Fund.
Nick and Chris manage FEML and the Fidelity FAST Emerging Markets Fund, which was launched in 2011 with the same long-short approach. Both funds are run in a similar way, with only minor differences. The open-ended fund has been managed by Nick, and more recently Chris, since launch.
FEML is not bound by UCITs rules, so it can hold over 10% of assets in a single company, as shown by its current position in Taiwan Semiconductors. There are also some small legacy holdings from when Nick and Chris took over from Genesis in 2021.
Figure 1: FEML’s research and investment process
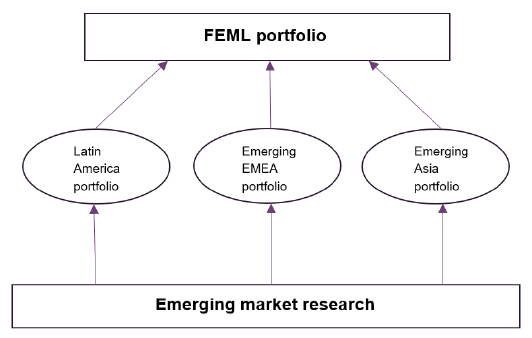
Nick and Chris are supported by a large team of analysts, each covering 20-30 stocks.
FEML’s investment process uses Fidelity’s wider resources, including the research team and regional emerging market portfolios. Chris and Nick are backed by a large analyst team, split between Asia and the UK, each covering 20 to 30 stocks. Regional portfolio managers shortlist their top ideas for sub-portfolios, from which Chris and Nick select their preferred stocks for FEML after further review. They also use insights from shorting analysts, including a dedicated emerging markets specialist. Chris and Nick make all final investment decisions, and while most stocks are first held in sub-portfolios, this is not a strict requirement.
FEML takes a flexible approach, using its closed-ended structure to invest in smaller companies without worrying about liquidity issues faced by open-ended funds. The managers aim to hold high-quality stocks in the long portfolio.
Here, quality means companies that deliver strong, sustainable returns throughout different market conditions. Favoured companies usually have net cash on their balance sheets, strong returns, good corporate governance and protect minority shareholders. They must also offer good value as well as quality.
The ability to short
FEML’s ability to short makes it unique in the emerging markets sector.
FEML stands out in the sector by holding both long and short positions. The short positions, which make up about 30-35% of the portfolio, allow the fund to benefit if certain companies fall in value. These are a mix of one-off shorts and pair trades, where a short is matched with a long in a related company.
Short positions should be the opposite of the long holdings. To be included, a company must be in fundamental or cyclical decline and show several balance sheet warning signs. Shorts are not based on valuation alone – there must be real concerns about the company’s finances. Individual short positions usually average 40 basis points and do not exceed 100 basis points.
The short book also helps the managers increase long exposure, allowing the portfolio to reach 130-135% long exposure while aiming for net exposure of around 100%.
The managers do not disclose which companies are held as active shorts.
Asset allocation
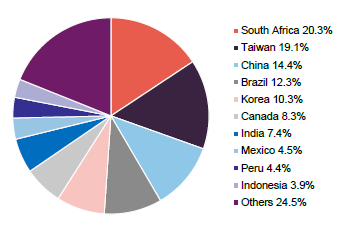
As of 31 December 2025, FEML’s gross market exposure was 157.1%, due to holding both long and short positions. Net equity exposure stood at 106.9%. As shown in Figures 2 and 3, FEML’s geographic exposure is very different from the index, highlighting that MSCI Emerging Markets is used as a reference, not a strict benchmark that the constrains the managers. The portfolio’s active share was 129.9% for the year to 30 June 2025.
Figure 2: FEML geographic allocation as at 31 December 2025*
Source: Fidelity Investment Companies. *Note: as a proportion of net assets
Figure 3: MSCI Emerging Markets geographic allocation as at 31 December 2025
Source: MSCI
Some allocations in Figure 2 can be misleading. The large overweight in South Africa, FEML’s biggest geographical weighting, mainly reflects its holding in Naspers, the fund’s second-largest position. Much of Naspers’ value comes from its stake in Chinese company Tencent. As a result, the apparent underweight in China is less significant when considering the indirect Tencent exposure.
Outside China and South Africa, FEML is underweight in Taiwan, as this market usually trades at higher valuations than other emerging markets. The managers believe better opportunities exist elsewhere but have recently increased exposure to Taiwan’s AI supply chain. The fund is also underweight India and Korea, but overweight in Brazil.
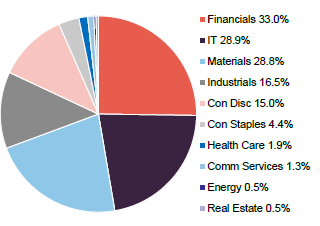
Figure 4: FEML sector allocation as at 31 December 2025*
Source: Fidelity Investment Companies. *Note: as a proportion of net assets
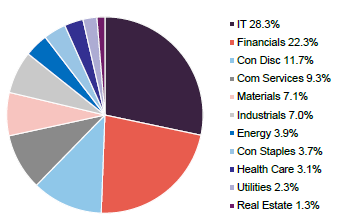
Figure 5:MSCI Emerging Markets sector allocation as at 31 December 2025
Source: MSCI
FEML has a slight 1.3% negative net exposure to utilities, mainly because of short positions. The fund’s largest long exposure is to financials, with two of its top 10 holdings in this sector (see Figure 6). The second-largest allocation is to IT, which is similar to the index. Materials is the third-largest holding and the biggest overweight compared to the index, showing the managers’ strong belief in this sector, especially in gold and copper.
Top 10 holdings
Figure 6: Top 10 holdings as at 31 December 2025
| Holding | Sector | Country | Allocation 31 December 2025 (%) | MSCI Emerging Markets Index (%) | Relative versus index |
|---|---|---|---|---|---|
| Taiwan Semiconductor | Information technology | Taiwan | 13.8 | 11.9 | 1.9 |
| Naspers | Consumer discretionary | South Africa | 7.8 | 0.5 | 7.3 |
| Pan African Resources | Materials | South Africa | 4.1 | 0.0 | 4.1 |
| Samsung Electronics | Information technology | Korea | 3.7 | 4.3 | (0.6) |
| OTP Bank | Financials | Hungary | 3.1 | 0.2 | 2.9 |
| Aura Minerals | Materials | Brazil | 3.0 | 0.0 | 3.0 |
| Contemporary Amperex Technology | Industrials | China | 3.0 | 0.2 | 2.8 |
| Sieyuan Electric | Industrials | China | 2.9 | 0.0 | 2.9 |
| TBC Bank | Financials | UK | 2.8 | 0.0 | 2.8 |
| Cia de Minas Buenaventura | Materials | Peru | 2.5 | 0.0 | 2.5 |
| Total of top 10 | 46.9 | 16.6 |
Sieyuan Electric
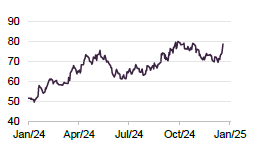
Figure 7: Sieyuan Electric (CNY)
Source: Bloomberg
Sieyuan Electric (www.sieyuan.com) is a Chinese grid equipment supplier and the only private sector business competing with less efficient State-Owned Enterprises. Originally focused on high-voltage gas insulated switches, Sieyuan has used its private ownership to attract top R&D engineers and quickly expand into new product lines. This has helped it gain market share in a fast-growing sector.
FEML’s managers believe Sieyuan will benefit from rising demand as the global shift to renewables and increased power generation require major upgrades to electricity grids.
TBC Bank
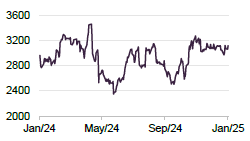
Figure 8: TBC Bank (GBP)
Source: Bloomberg
TBC Bank (www.tbcbankgroup.com) is a leading Georgian bank, sharing about 80% of the market with one other major bank. Despite earning returns on equity above 25%, TBC trades at a P/E ratio of around 5x, which Nick and Chris consider very cheap for such a profitable and dominant bank.
TBC has recently launched a digital bank in Uzbekistan, a country with a population 10 times larger than Georgia’s. With an experienced CEO who has a strong fintech background, FEML’s managers see this move as a significant growth opportunity.
Aura Minerals
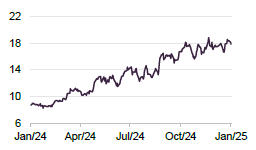
Figure 9: Aura Minerals (CAD)
Source: Bloomberg
Aura Minerals (www.auraminerals.com) is a Brazilian gold miner that Nick and Chris still see as cheap despite this year’s gold price rise. At current production, Aura can deliver a free cash flow yield above 20% even if gold falls to $3,000 an ounce, which is well below current prices.
The company’s capital spending is high but can be covered by cash flow while still paying a strong dividend. Production is expected to double once its current projects are finished.
Other notable holdings
Alfamart
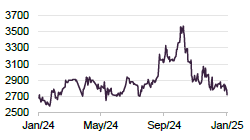
Figure 10: Alfamart (IDR)
Source: Bloomberg
Alfamart (www.alfamart.co.id) is a major Indonesian grocery retailer focused on minimarkets. Its shares are at a historic low, trading at about 20 times earnings, due to economic uncertainty in Indonesia and weak profit margins. Despite this, FEML’s managers see long-term potential for strong growth.
Formal retail is still underdeveloped in Indonesia, giving Alfamart plenty of room to expand by opening new stores. Nick and Chris also highlight Alfamart’s strong position as the leading company in a two-player market.
Orizon
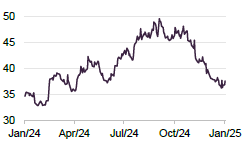
Figure 11: Orizon (BRL)
Source: Bloomberg
Orizon (www.orizonvr.com) operates landfill sites in Brazil and benefits from strong pricing power thanks to its local monopolies. FEML’s managers expect margins to keep improving as the company negotiates higher prices. With landfill use in Brazil at about 60%, there is still plenty of room for growth as regulations on waste treatment become stricter.
Orizon can also increase earnings by adding biomethane capacity or by buying other assets at low prices.
Kazatomprom
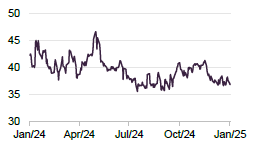
Figure 12: Kazatomprom (USD)
Source: Bloomberg
Kazatomprom (www.kazatomprom.kz) is one of the world’s largest uranium producers, responsible for about 20% of global output. It is well placed to benefit from a positive supply and demand outlook for uranium, which could boost its valuation.
FEML’s managers believe that the rapid growth of AI and data centres will drive up energy demand, with nuclear power seen as a key solution. This should help support uranium prices. Kazatomprom trades at a low valuation and pays out most of its earnings as dividends, offering strong returns to shareholders.
Performance
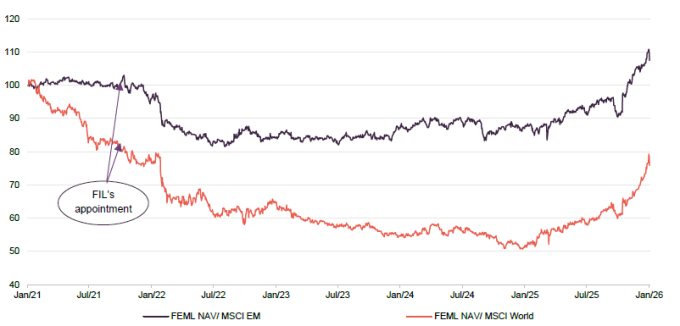
Figure 13: FEML’s NAV total return relative to emerging market and global indices, over five years to 30 January 2026
Source: Bloomberg, Marten & Co
Figure 14: Cumulative total return performance over periods ending 30 January 2026
| 1 month (%) | 3 months(%) | 6 months (%) | 1 year (%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|---|
| FEML NAV | 9.0 | 23.2 | 41.1 | 59.6 | 84.3 | 42.2 |
| FEML share price | 12.4 | 29.0 | 46.5 | 71.2 | 100.6 | 50.0 |
| MSCI Emerging Markets index | 6.8 | 4.9 | 19.6 | 30.4 | 44.9 | 32.3 |
| MSCI World index | 0.3 | (0.9) | 7.9 | 9.1 | 54.8 | 87.4 |
The fund’s current management took over in late 2021. In 2022, underperformance was mainly due to a large exposure to Russia at the time of the Ukraine invasion. These Russian holdings were written down to zero because trading was not possible, though some have since been sold over the counter while others remain. The fund also held fewer shares in areas like the Middle East, which performed well during that period. However, FEML’s performance later improved, with its NAV outperforming the index.
FEML has underperformed the MSCI World Index since the managers took over. The index is heavily weighted towards the US market, which makes up over 70% and is led by large technology companies. These US tech firms have delivered strong returns in recent years, while emerging markets have seen more mixed results.
Peer group
FEML is part of the global emerging markets sector, which has 11 members, excluding Africa Opportunity due to its small £6m market cap. Funds in this sector generally have:
- over 80% invested in listed emerging market shares;
- less than 80% in any one region;
- an investment policy focused on global emerging markets; and
- use a global emerging market benchmark.
Peer group performance
Figure 15: Peer group cumulative NAV total return performance to 30 January 2026
| 1 month (%) | 3 months(%) | 6 months (%) | YTD (%) | 1 year (%) | 3 years(%) | 5 years(%) | FIL’s tenure*(%)1 | |
|---|---|---|---|---|---|---|---|---|
| FEML | 9.0 | 23.2 | 41.1 | 9.0 | 59.6 | 84.3 | 42.2 | 48.2 |
| Ashoka WhiteOak EM | 6.7 | 5.3 | 19.4 | 6.7 | 29.2 | – | – | – |
| Barings Emerging EMEA | 10.2 | 11.1 | 21.6 | 10.2 | 31.9 | 68.9 | 42.7 | 21.2 |
| BlackRock Frontiers | 6.8 | 9.4 | 15.6 | 6.8 | 19.9 | 52.6 | 99.5 | 70.3 |
| JPMorgan Emerging EMEA | 8.7 | 10.1 | 17.4 | 8.7 | 25.9 | 56.6 | (88.8) | (91.8) |
| JPMorgan Emerging Mrkts | 8.3 | 7.7 | 25.2 | 8.3 | 29.1 | 36.9 | 25.2 | 25.7 |
| JPMorgan Global EM Inc | 8.5 | 8.3 | 22.0 | 8.5 | 31.3 | 48.1 | 54.9 | 51.0 |
| Mobius | 5.8 | 4.2 | 11.2 | 5.8 | 3.2 | 19.3 | 45.8 | 13.7 |
| Templeton Emerging Mrkts | 12.7 | 11.0 | 31.1 | 12.7 | 49.0 | 73.2 | 49.0 | 65.2 |
| Utilico Emerging Markets | 5.9 | 9.4 | 16.9 | 5.9 | 23.5 | 40.4 | 69.1 | 49.1 |
| FEML rank | 3/10 | 1/10 | 1/10 | 3/10 | 1/10 | 1/9 | 7/9 | 5/9 |
| Sector arithmetic avg. | 8.3 | 10.0 | 22.1 | 8.3 | 30.3 | 53.4 | 37.7 | 28.1 |
| Sector arithmetic avg. exc. FEML | 8.2 | 8.7 | 20.3 | 8.2 | 27.3 | 49.9 | 37.2 | 25.8 |
As shown in Figure 15, FEML’s NAV performance over one year is very strong, outperforming all other funds in its sector. Its three-year performance is also impressive, ranking highest among peers. The five-year figure, which covers the period under Genesis’s management, is weaker. Since Nick and Chris took over, FEML ranks fifth out of nine funds.
Figure 16: Peer group comparison – size, fees, discount, and yield as at 26 November 2025
| Market cap (£m) | St. dev. of NAV returns over one year | Ongoing charges (%) | Perf. fee | Premium/ (discount) (%) | Dividend yield(%) | Gross gearing(%)3 | Net gearing(%)3 | |
|---|---|---|---|---|---|---|---|---|
| FEML | 450 | 13.9 | 0.83 | No | (9.8) | 2.0 | 70.9 | 61.3 |
| Ashoka WhiteOak EM | 56 | 14.1 | 1.90 | Yes1 | (0.9) | – | Nil | (7.5) |
| Barings Emerging EMEA | 89 | 23.4 | 1.70 | No | (14.6) | 2.2 | Nil | (1.8) |
| BlackRock Frontiers | 330 | 10.6 | 1.41 | Yes | (4.3) | 4.3 | 23.9 | 11.9 |
| JPMorgan Emerging EMEA | 115 | 52.5 | 4.17 | No | 344.6 | 0.2 | Nil | (2.7) |
| JPMorgan Emerging Mrkts | 1,303 | 14.6 | 0.79 | No | (8.5) | 3.8 | Nil | (2.7) |
| JPMorgan Global EM Inc | 431 | 10.8 | 0.96 | No | (9.5) | 3.5 | Nil | (0.2) |
| Mobius | 160 | 14.1 | 1.4 | No | (10.1) | 1.2 | Nil | (6.4) |
| Templeton Emerging Mrkts | 2,221 | 16.2 | 0.95 | No | (8.6) | 2.3 | 3.0 | (0.2) |
| Utilico Emerging Markets | 475 | 11.2 | 1.5 | No | (11.1) | 3.4 | 3.1 | 3.0 |
| FEML rank2 | 4/10 | 4/10 | 2/10 | 7/10 | 7/10 | 10/10 | 10/10 | |
| Sector arithmetic avg.4 | 563 | 18.1 | 1.56 | (8.6) | 2.5 | 10.1 | 5.5 | |
| Sector arithmetic avg.4 exc. FEML | 576 | 18.6 | 1.64 | (8.5) | 2.6 | 3.3 | (0.7) |
FEML is one of the larger emerging market trusts, though it remains smaller than sector leaders JP Morgan Emerging Markets and Templeton Emerging Markets. Its ongoing charges are very competitive within the sector, and like most peers, it does not charge a performance fee.
FEML’s dividend yield is average for the sector, where income payments are generally low. Its discount to NAV is also typical, with most trusts trading at high single- or low double-digit discounts.
FEML stands out for its much higher gross and net gearing compared to peers, most of whom hold net cash. This higher gearing comes from the fund’s extended positions on both the long and short side.
FEML’s NAV returns show average volatility compared to its peers.
Dividend
FEML mainly aims for capital growth, with income being a secondary focus, so shareholders should not expect significant income returns. However, some income is generated and, after costs, most revenue earnings are paid out as a final dividend, usually in December.
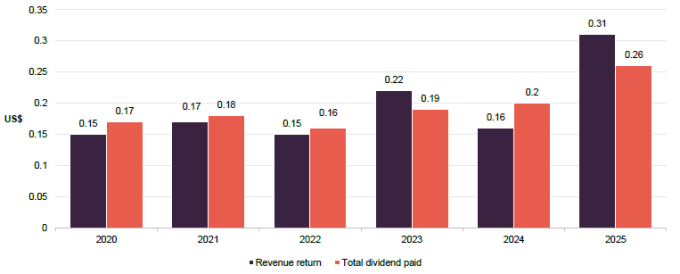
For the year ended 30 June 2025, FEML’s board has approved a final dividend of US$0.26 per share (up from US$0.20 in 2024), giving a yield of 1.6% based on a share price of 1,198p as at 30 January 2026.
Figure 17: FEML revenue income and dividend by financial year (ended 30 June)
Source: Fidelity Emerging Markets Limited
The 2025 dividend was 30% higher than last year but was fully covered by revenue. In recent years, dividends sometimes exceeded revenue income, but over the long term, FEML has usually paid covered dividends. This approach has helped FEML build a revenue reserve, which reached US$59.1m or US$0.9185 per share as of 30 June 2025, up from US$51.3m or US$0.6877 per share a year earlier.
Premium/(discount)
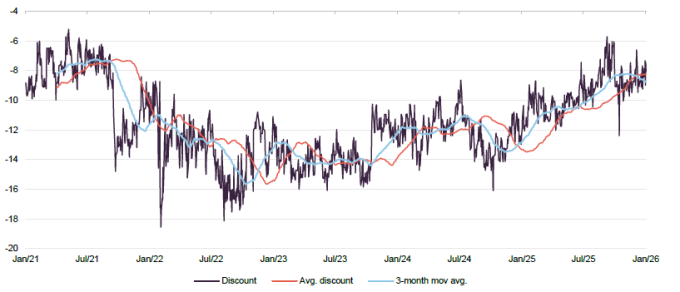
As shown in Figure 18, FEML’s discount to NAV widened from late 2021 as emerging-market equities lost popularity, global interest rate expectations rose, and the fund changed managers while running an over-subscribed tender offer. The discount narrowed for a time, but widened sharply after Russia invaded Ukraine. More recently, the discount has narrowed again, staying below 10% for much of 2025. Over the past year, the average discount was 9.5%, ranging from 5.7% to 12.4%. On 30 January, the discount stood at 8.1%, near the lower end of this range.
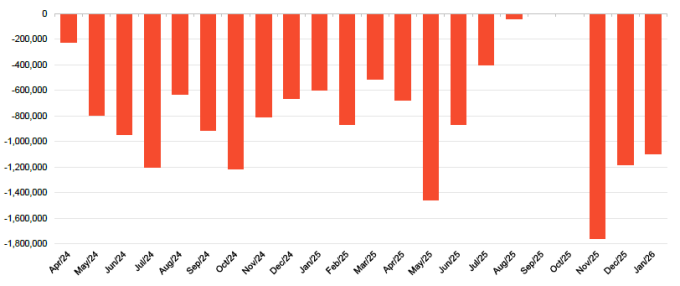
The company aims to keep the discount in single digits and has actively bought back shares to support this. The latest tender offer was in March 2024, and monthly share buybacks since then, shown in Figure 19, have totalled 22% of the share capital. The board plans to continue this buyback approach.
Figure 18: FEML premium/(discount) over five years to 30 January 2026
Source: Bloomberg, Marten & Co
The company has an aim of keeping the trust’s discount to single digits, and to this end has been active in buying back shares. FEML’s most recent tender offer was in March 2024, and the monthly share repurchases since then are shown in Figure 19. These have totalled 22.0% of the total share capital over this period, and the board intends to continue with this buyback strategy in the future.
Figure 19: FEML share buybacks and issuance
Source: Fidelity Emerging Markets Limited
Strathclyde Pension Fund sale
At an EGM on 24 October, FEML shareholders approved the repurchase of 16,441,177 shares (25% of the fund) from Strathclyde Pension Fund, its second-largest shareholder. The buyback was completed on 13 November 2025 at a 14% discount to NAV, compared to the market discount of 9.8% that day.
Strathclyde’s holding dated back to FEML’s previous management by Genesis. The sale led to an approximate 4.5% increase in NAV for remaining shareholders.
Capital structure
FEML is a Guernsey-based closed-end investment company with two types of shares: founder shares and participating preference shares. Only the participating preference shares are listed on the London Stock Exchange and carry economic rights, including access to profits, assets, and dividends. Founder shares, created in 1989 to meet Guernsey company law, have no economic rights and do not benefit from the company’s performance. Since 7 October 2021, FIL Investment Services (UK) Limited holds the founder shares, which only provide limited voting rights on issues affecting that share class. Founder shares do not dilute or impact the rights of participating preference shareholders.
Gearing
FEML can borrow, but net gearing is limited to 10% of net assets. It also aims to use its overdraft facility for trading only when necessary. As of 31 December 2025, FEML had net gearing of 6.9% of net assets. Gross gearing was higher at 57.1%, reflecting both short and long equity positions.
Major shareholders
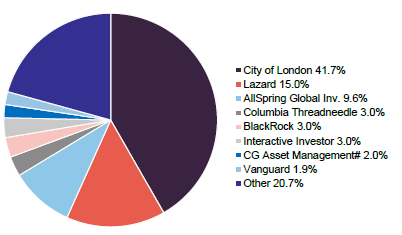
FEML has a significant institutional presence on its share register.
Figure 20 shows that FEML’s share register is dominated by institutional investors.
Figure 20: Major shareholders as at 31 December 2025
Source: Bloomberg, Marten & Co.
Unlimited life with a five-yearly continuation vote
FEML does not have a set end date, but following changes in management in 2021, the company agreed to give shareholders a continuation vote in 2026 and every five years after. This vote will take place at the AGM in December.
A conditional tender offer is planned for September 2026. If the fund underperforms its benchmark over the five years to 30 September 2026, shareholders will be able to tender up to 25% of their shares. The offer applies if the fund’s NAV total return does not beat the benchmark over that period. As of December 2025, the fund was more than 8% ahead of the benchmark in GBP terms for the period so far.
Financial calendar
FEML’s financial year ends on 30 June. Annual results are released in October, with interim results in March. The AGM is usually in December, with this year’s on 1 December. FEML pays one final dividend each December, after approval at the AGM.
Fees and costs
The investment manager receives a fee of 0.6% of net asset value, calculated daily and paid monthly in arrears.
Management team
Nick Price (portfolio manager)
Nick set up Fidelity’s Emerging EMEA group in 2005.
Nick Price founded Fidelity’s Emerging EMEA group in 2005 and created the investment process now central to Fidelity’s emerging markets equity strategies. This approach expanded globally in 2009. In 2011, Nick launched the FAST (Fidelity Active STrategy)-Emerging Markets strategy, which he still leads and which closely mirrors FEML, offering a longer-term performance record.
Nick joined Fidelity in 1998 as a research analyst covering pan-European sectors, later becoming assistant portfolio manager of the European Growth Fund in 2004. Earlier, he worked in London at SBC Warburg, Daiwa Europe Bank, and JP Morgan, after starting his career as an auditor with Price Waterhouse in Johannesburg. He holds a Bachelor of Commerce and a Diploma in Accounting from the University of Natal, is a member of the South African Institute of Chartered Accountants, and is a CFA charterholder.
Chris Tennant (co-portfolio manager)
Chris has spent his entire career at Fidelity, starting in 2011 as an equity analyst covering European transportation. In 2012, he joined the London-based emerging markets team, focusing on EMEA and Latin American metals and mining. In 2015, he became an EM shorting analyst, working with Nick to develop the short book for EMEA and Latin America.
He was appointed assistant portfolio manager on the FAST-Emerging Markets strategy in 2019 and promoted to co-portfolio manager in 2021. Chris is also part of the Emerging EMEA and Latin America equities portfolio management teams. He holds a Master’s in engineering from Imperial College.
Board
FEML’s board has five non-executive directors, all independent of the investment manager. According to FEML’s articles, new directors must stand for election at the next AGM. Board policy is that all directors retire and stand for re-election at every AGM.
The average director has served for 5.1 years, with Katherine Tsang being the longest at 8.4 years. Apart from FEML’s board, the directors do not share any other directorships. The articles of association cap total directors’ fees at US$400,000 per year. For the current financial year, average director fees have risen by 3.9% compared to the previous year.
Figure 21: Board member length of service and shareholdings
| Director | Position | Date of appointment | Length of service (years) | Annual fee (GBP) 1 | Shareholding2 | Years of fee invested3 |
|---|---|---|---|---|---|---|
| Heather Manners | Chairman | 5 May 2022 | 3.6 | 52,000 | 10,000 | 1.9 |
| Mark Little | Chair of the audit committee | 17 January 2024 | 1.9 | 39,500 | 3,869 | 1.0 |
| Torsten Koster | Senior independent director | 1 July 2020 | 5.4 | 39,500 | 15,000 | 3.8 |
| Dr Simon Colson | Director | 1 July 2019 | 6.4 | 37,500 | 4,416 | 1.2 |
| Katherine Tsang | Director | 19 July 2017 | 8.4 | 37,500 | 8,000 | 2.1 |
| Average (service length, annual fee, shareholding, years of fee invested) | n/a | n/a | 5.1 | 41,200 | 8,257 | 2.0 |
Recent share purchase and disposal activity by directors
All of FEML’s directors have personal investments in the fund.
Since mid-2024, three FEML directors have bought company shares for the first time. Mark Little bought 2,850 shares at £7.01 each on 14 October 2024 and 1,019 shares at £9.82 on 8 October. Katherine Tsang bought 8,000 shares at £6.80 each on 6 November 2024. No directors have sold shares during this period. As shown in Figure 21, all FEML directors now hold shares in the fund, which helps align their interests with shareholders. On average, their holdings are equal to 1.9 years of their fees.
Heather Manners (chairman)
Heather joined FEML’s board in May 2022 and became chairman in December 2022. She has 34 years’ experience investing in Asia, including 15 years as co-founder, CEO and CIO of Prusik Investment Management. Heather started her career at Henderson Global Investors, where she was head of Asia and emerging markets. She is also a non-executive director at Montanaro Asset Management and Collidr Asset Management, and was previously a non-executive director at Aberdeen New Dawn Investment Trust.
Mark Little (chairman of the audit committee)
Mark is a chartered accountant with broad experience in fund management, research and private banking. He also has a solid understanding of compliance and regulation in the modern financial services world.
Mark began his career as a fund manager at Scottish Widows Investment Management after qualifying as a chartered accountant with Price Waterhouse in 1991. He later became global head of automotive research at Deutsche Bank and joined Barclays Wealth in 2005, where he served as Managing Director for Scotland and Northern Ireland.
Mark is currently a non-executive director and chairs the audit committees of BlackRock Smaller Companies Trust Plc, Majedie Investments Plc, and Abrdn Equity Income Trust Plc. He has also been a non-executive director and chair of the audit and risk committee at STS Global Income & Growth Trust Plc, and previously held senior roles at Barclays Wealth and Deutsche Bank. Mark holds a degree in Accountancy and Economics from Aberdeen University.
Torsten Koster (senior independent director)
Torsten has over 30 years’ experience with major international companies. He worked at Nestle SA from 1991 to 1997 and again from 2003 to 2016, serving as chief financial officer for Nestle Russia & Eurasia from 2007 to 2011 and for Nestle Nespresso SA from 2011 to 2016.
He was also chief financial officer at Lukoil SA from 1998 to 2000 and at ELCA Informatique SA from 2000 to 2003. In 2016, he founded Baussan Concept SA, a consultancy providing due diligence and portfolio services to private equity firms in Europe and the US.
Torsten has held several board roles, including director of SodaStream International (2016-2018), vice chairman of Natra SA, Spain (2019-2022), and is currently chairman of Banque Heritage SA and director of ECOM Agroindustrial SA, both unlisted. He holds a Master’s degree from HEC Lausanne and lives in Switzerland.
Dr Simon Colson (director)
Simon, based in the UK, has over 30 years’ experience in financial markets, including roles in investment banking, investment management and consulting. From 1995 to 2001, he was managing director at Deutsche Bank AG London, leading closed-end fund origination and distribution. He has launched, restructured and repurposed many investment companies, and served as a non-executive director of The Association of Investment Companies from 2002 to 2005.
In 2002, Simon set up his own FCA-regulated consulting and distribution business, raising assets for emerging managers across various asset classes, including closed-end funds. Since 2017, he has focused on advisory and non-executive roles, and is currently a non-executive director of the Children’s Liver Disease Foundation. Simon is a qualified medical doctor and holds an MBA in Finance & Investment from Bayes Business School, City St George’s, University of London.
Katherine Tsang (director)
Before retiring in 2014, Katherine spent 22 years at Standard Chartered Bank, finishing as Chairperson of Greater China. After retiring, she founded Max Giant, which trades and invests across Asian markets.
Based in Hong Kong, Katherine is now an independent non-executive director at China CITIC Bank International and Budweiser Brewing Company APAC. She is also on the City of London’s Advisory Council for China and is an honorary Board member at Shanghai Jiao Tong University. Previously, she was an independent non-executive director at Gap Inc. and Baoshan Iron & Steel, and served on the World Economic Forum’s Global Agenda Council on China and Sotheby’s Advisory Board.
SWOT analysis
Figre 22: SWOT analysis for FEMLhe investment process is demonstrably strong, with the managers supported by a large team of analysts.
| FEML is unique in the sector in taking short positions alongside the long book, allowing investors to potentially profit from both ends of the quality spectrum. | FEML has previously had to write off a portion of its portfolio, the Russian assets in 2022. Given the higher risk nature of emerging markets investing, risk of unforeseen events is ever-present, albeit the managers have indicated the process enhancements they have made in recent years regarding management of country risk. |
| The investment process is demonstrably strong, with the managers supported by a large team of analysts. | |
| FEML’s gearing is achieved using CFDs. These are an efficient, cost effective and flexible form of financing and enable the portfolio manager to be nimble in the deployment of gearing. | |
| FEML’s fee structure is competitive, ranking 2nd lowest in the peer group |
| Emerging markets are currently enjoying a very positive period of performance, with signs that this will continue, given a weakening US dollar and appealing valuations, despite the rally. | Emerging markets are volatile |
| Emerging markets tend to be dynamic, with new themes becoming investable over time, and therefore the opportunity set expands. | The US dollar experienced a period of weakness last year. This may not continue, and any period of dollar strength is generally negative for emerging markets. |
| Emerging markets are sensitive to interest rates, due to capital flows, particularly in Asia. |
Source: Marten & Co
Bull vs bear case
Figure 23: Bull vs bear case for FEML
| Performance | FEML’s performance this year has been strong in both absolute and relative terms. The same can be said for three-year performance. | Five-year numbers are less robust (noting that Fidelity took over management in October 2021), with FEML’s performance particularly struggling in 2022. |
| Dividends | FEML is primarily focused on generating capital growth. An annual dividend is paid given that income from the portfolio occurs naturally. | FEML’s modest dividend makes it unsuitable for income-seeking investors. |
| Outlook | Emerging markets are currently enjoying a period of positive performance, underpinned by a strong macro environment. This could well continue through 2026. | Bull markets in emerging markets can turn into bears very quickly. Emerging markets are often sensitive to global economic output due to their particular reliance on exports. The likelihood of a turnaround is increased by the uncertain policy environment in the US, which could have severe knock-on effects. |
| Discount | FEML’s Board continues to be proactive in repurchasing shares, aiming to keep the discount in single digits under normal market conditions. |
FEML has traded on a discount for a number of years, and the current discount could widen back to double digits if conditions and/or performance deteriorate. |
Source: Marten & Co
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Fidelity Emerging Markets Limited.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.