
Diversification pays dividends
Foresight Environmental Infrastructure (FGEN) appears to have benefitted from its diversified portfolio during a period of significant regulatory and market uncertainty for the renewable energy sector. Whilst reductions in power price forecasts and government policy changes – including revisions to inflation-linked renewable subsidies, the planned removal of the Carbon Price Support mechanism and the extension of the Electricity Generator Levy – have weighed on sentiment across the sector, FGEN’s broad portfolio may have limited the impact on its NAV and cash flows.
Recognition of the benefits of diversification may be behind FGEN’s material discount narrowing in recent months, but it continues to offer a high yield, a progressive dividend and multiple avenues for potential future value creation. This includes both growth assets that are ramping up operations and across its anaerobic digestion portfolio, which we explore further in this note.
Progressive dividend from investment in environmental infrastructure assets
FGEN aims to provide its shareholders with a sustainable, progressive dividend, and offer opportunities for capital growth. It invests in a diversified portfolio of environmental infrastructure technologies, targeting projects characterised by long-term stable cash flows, secured revenues, and inflation linkage. Investment in these assets is driven by the need to address climate change and societal demand for sustainability.
| 12 months ending | Share price TR (%) | NAV total return (%) | Earnings per share (pence) | Adjusted EPS (pence) | Dividend per share (pence) |
|---|---|---|---|---|---|
| 31/03/2022 | 7.3 | 34.1 | 30.6 | 7.0 | 6.80 |
| 31/03/2023 | 12.2 | 13.1 | 14.9 | 6.7 | 7.14 |
| 31/03/2024 | (15.8) | (1.8) | (2.1) | 7.5 | 7.57 |
| 31/03/2025 | (15.9) | 0.6 | (0.4) | 8.6 | 7.80 |
| 31/03/2026 | 5.4 | 6.6 | 5.9 | 9.4 | 7.96 |
Fund profile
Further information can be found at FGEN.com
FGEN invests in a diversified portfolio of private infrastructure assets that are intended to deliver returns, long-term income, and opportunities for growth while supporting decarbonisation and sustainable resource management.
FGEN invests in three core areas of environmental infrastructure: renewable energy generation, other energy infrastructure, and sustainable resource management. Renewable energy generation investments include wind, solar, anaerobic digestion (AD), biomass, energy from waste, and hydropower. Other energy infrastructure assets include battery energy storage and low carbon transport. Sustainable resource management includes wastewater, waste processing, and sustainable solutions for food production, including agri- and aquaculture-controlled environment projects.
FGEN’s portfolio is diversified across complementary sectors, technologies and geographies, which may reduce its exposure to fluctuations in weather patterns and may differentiate the company from its peers.
FGEN’s mandate allows it to invest in emerging areas of environmental infrastructure, provided that they are sufficiently mature and display infrastructure characteristics.
FGEN’s AIFM is Foresight Group LLP (Foresight). Foresight is an investor in renewable infrastructure assets, with £13.0bn of AUM at 31 March 2026. This includes Foresight Solar Fund, which sits in FGEN’s peer group. Foresight has a global infrastructure team with 185 infrastructure professionals managing around 5.0GW of energy infrastructure. It is a global business, with offices in seven countries. The co-lead managers for FGEN are Edward Mountney and Charlie Wright.
Market backdrop
Government policy changes weighed on sentiment towards renewable energy infrastructure sector
The many government policy changes may have added an additional layer of uncertainty to the UK renewable energy infrastructure sector, and appear to have influenced investor sentiment over the past few months. The inflation measure used in existing clean energy incentives used in the renewables obligation (RO) and feed-in-tariffs (FIT) schemes switched to CPI from the historically higher RPI in April.
The Carbon Price Support mechanism (CPS) will also be abolished from April 2028. This is expected to reduce the marginal cost of gas-fired generation that typically sets UK wholesale power prices, which could result in lower long-term power price forecasts.
Meanwhile, following a spike in fuel prices that appears to be linked to the conflict in the Middle East, the government extended and increased the Electricity Generator Levy (EGL). The tax rate on exceptional generation receipts from UK-based electricity generators rose from 45% to 55% from 1 July. Additionally, the levy will be extended past its previously scheduled end date of 31 March 2028.
FGEN’s diverse portfolio has shielded it from worst of policy impact
Due to FGEN’s diversified portfolio, the impact of these policy changes on the company’s NAV appears to have been small, especially when compared to its pure-play renewable peers. Less than 30% of FGEN’s portfolio revenue is subject to RO and FIT incentives and therefore the change to CPI inflation linkage reduced NAV by 0.5p per share or 0.5%. Likewise, the removal of the CPS was assessed in FGEN’s 2026 valuation and resulted in a 0.4p reduction in NAV.
FGEN’s manager is not forecasting any extra payments due to the EGL extension. Whilst the company is still earning revenues on some assets above the benchmark price, the manager does not expect that to go beyond the £10m de minimis level.
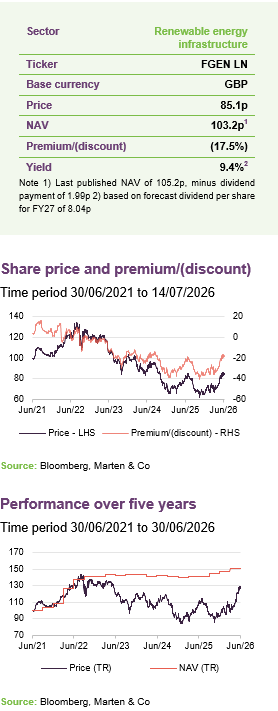
This appears to be reflected in its NAV and share price performance relative to its peer group (see page 14).
Under a likely Burnham premiership, FGEN’s manager says that it expects the broader policy direction to remain supportive for renewables, grid investment, energy security and regional infrastructure. If there is any shift, the manager believes it would more likely be across regulated utilities where public control, affordability and returns may come under greater scrutiny, affecting ownership models more than decarbonisation ambition. The manager states that it does not expect FGEN to be materially impacted, as it has limited exposure to UK regulated utility assets, no reliance on a single policy framework, and a diversified portfolio across renewable generation, energy infrastructure and sustainable resource management, with revenues supported by contracted, subsidised and diversified merchant streams.
Annual results
FGEN reported a NAV of £655.5m or 105.2p per share at 31 March 2026 – a 1.2% fall over the year. Factoring in dividends of 7.96p, this equated to a 6.2% NAV total return for the year.
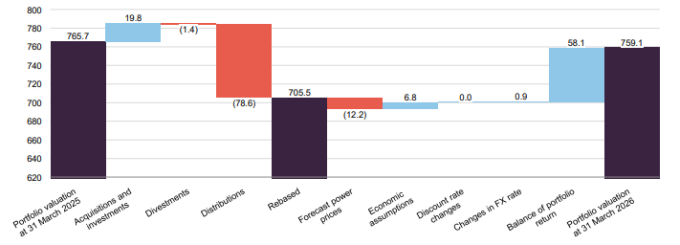
Figure 1: FGEN portfolio valuation in £m, as at 31 March 2026
Dividend comfortably covered by portfolio cash flows
Distributions received from projects over the year were £78.6m (2025: £90.4m). The manager says that the reduction in revenues from the previous year was primarily influenced by the rolling off of higher power price fixes entered into post-Ukraine conflict, with some downtime across the biomass and foodwaste AD parts of the portfolio also contributing. Dividend coverage remained at a level of 1.25x. The value of the portfolio fell £6.6m over the year, as shown in Figure 1.
Drivers of portfolio returns
Several factors impacted FGEN’s NAV. The following sections set out these factors and their sensitivities, beginning with power prices.
Power prices
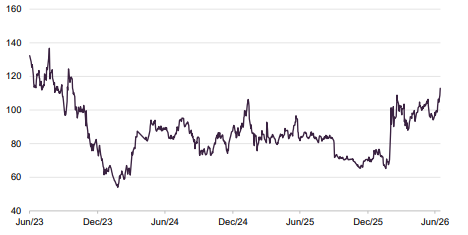
Power prices increased in March, which the manager attributes to the conflict in the Middle East, as shown in Figure 2. However, lower forecasts for future electricity and gas prices compared to forecasts at 31 March 2025 contributed to a £12.2m reduction in FGEN’s NAV. This appears to have been a factor in the falling NAVs of FGEN’s peers, but FGEN’s diversified portfolio may make it less sensitive to this issue.
Figure 2: UK power prices
Updated forecasts reflect the expected impact of the abolition of the Carbon Price Support mechanism. The removal of the CPS was assessed in FGEN’s 2026 valuation and resulted in a £2.3m reduction in NAV (or 0.4p per share).
Fixed prices secured on the majority of portfolio
FGEN looks to fix the prices for most of its output, in an attempt to reduce its exposure to volatile market prices. At 31 March 2026, the portfolio had price fixes secured at 80% for the Summer 2026 season, 70% for the Winter 2026/27 season, and 17% for Summer 2027.
FGEN’s manager has assessed that, over the life of the asset, an increase in electricity and gas prices of 10% would add £36.2m (or 5.8p) to NAV and a 10% fall in power prices would reduce NAV by £36.3m (or 5.8p).
FGEN’s manager states that in the event that electricity prices fall to £50/MWh (they are currently at around £110/MWh) and gas prices fall by a corresponding amount, the company would likely maintain dividend cover for the next three financial years.
Inflation
Short-term RPI inflation assumptions raised 50bps
Inflation assumptions used to value FGEN’s portfolio at 31 March 2026 (based on actual data and independent forecasts) were raised by 50bps to 4.0% RPI inflation for 2026, 3.0% until 2030 and 2.25% thereafter. This was associated with a £7.7m uplift in NAV.
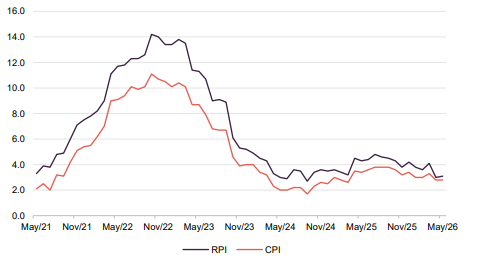
From 1 April 2026, the inflation measure used on RO and FIT contracts switched to CPI. FGEN’s CPI inflation assumptions were 3.0% in 2026, 2.5% to 2030 and 2.25% thereafter. CPI was 2.8% at the end of May 2026. Figure 3 shows RPI and CPI inflation over the past five years.
Figure 3: UK RPI and CPI year-on-year (%)
Changes to RO and FIT indexation were incorporated into FGEN’s March 2026 valuation and reduced NAV by £3.1m, equivalent to 0.5p per share.
Looking forward, FGEN’s manager has assessed that a decrease in the inflation rate of 0.5% over its base case would result in a fall in the portfolio valuation of £13.5m (2.2p per share), compared to an uplift in value of £13.9m (2.2p per share) if inflation increased by the same amount.
Anaerobic digestion life extension
The potential for life extensions on FGEN’s AD assets was outlined in a previous note. They were being valued over the 20-year life of the renewable heat incentive subsidy (RHI) that they receive, but the manager says that evidence across Europe and the UK, including several market transactions, suggests valuing the AD facilities beyond the end of the tariffs and possibly into perpetuity. FGEN, with an independent consultant, modelled revenues being derived from a range of sources including corporate offtakes, green certificates and/or a lower level of government support mechanisms.
FGEN extended the lives of seven AD assets
FGEN recognised an £8.7m (or 1.4p per share) NAV uplift from extending the lives of seven of its 11 AD assets that the manager states possess the most compelling extension potential – mainly waste-based AD assets that it believes have greater sustainability credentials than agricultural AD and could therefore be more attractive to corporate offtakers or receive greater government support.
The manager says that it used conservative assumptions and valuations were based on regulated market drivers and excluded higher voluntary green premiums that may emerge over time.
Some clarity is still required on the position that biomethane may take in the wider net zero and energy transition plans in the UK, with the government currently developing a biomethane policy framework, but the manager says that there is support and recognition from government of biomethane’s role in decarbonising hard-to-abate sectors.
Work is ongoing with a specialist independent consultant to further assess the remaining ADs in the portfolio before extensions and valuation uplifts may be applied.
Discount rates
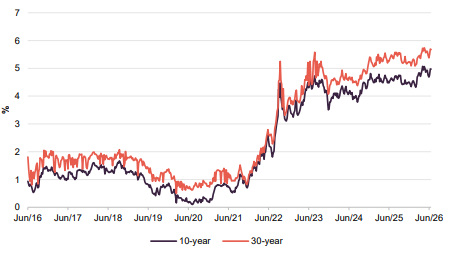
Figure 4: Long-term (10-year and 30-year) UK gilt yields
The weighted average discount rate now sits at 9.9%
UK gilt yields remain at elevated levels, as shown in Figure 4. There appear to have been no macro-driven changes to discount rates, but some project specific changes related to AD life extension and growth asset progression. FGEN’s weighted average discount rate moved out slightly to 9.9% (from 9.7%), primarily due to ongoing investment into growth assets and increases in their values. There was no change to NAV resulting from changes to the discount rate.
FGEN’s manager has assessed that a reduction in the discount rate of 0.5% would result in an uplift in value of £23.1m (or 3.7p per share), while a downward movement in the portfolio valuation of £21.2m (3.4p per share) would occur if discount rates were increased by the same amount.
Investment process
Foresight selects projects based on their risk-return profile and consistency with its investment policy, operating within a limited set of investment restrictions. Assets are acquired predominantly through secondary market transactions with third parties.
The AIFM seeks to maintain a balanced, diversified portfolio and adopts an approach it describes as cautious. Whilst FGEN can invest across all OECD countries, the portfolio remains predominantly UK-focused, with modest exposure to mainland Europe through Norway and Italy. The managers says that it favours jurisdictions and regulatory or subsidy regimes that they know well or where they have established partner relationships.
Investment restrictions
- No more than 25% of the portfolio may be invested in assets under construction or not yet operational, of which up to 5% may be invested in development-stage assets.
- At least 50% of the portfolio must be invested in the UK, with the balance invested in other OECD countries.
- No new investment may exceed 30% of NAV (or 25% of NAV based on acquisition cost, taking existing holdings into account).
Purchases from third parties
Deals can be introduced by the wider Foresight team
The manager says that opportunities are sourced through project developers, specialist consultancy firms and the wider Foresight team. Acquisition prices are negotiated on an arm’s-length basis, the manager adds, and reflect its assessment of each project’s risks, returns and capital structure.
ESG assessment
Previously, Foresight’s due diligence processes were structured around its proprietary Sustainability Evaluation Tool (SET), which was designed to consolidate a broad range of sustainability frameworks and assess material sustainability and ESG factors across both existing and prospective investments, while accommodating different investor preferences. As investor and sustainability expectations appear to be converging around a smaller set of common frameworks, Foresight says that it has evolved its approach. The manager says that the SET has been redesigned primarily as a portfolio management tool, while pre-investment due diligence and ongoing ESG monitoring are now expected to be aligned with regulatory requirements and three core frameworks: the SASB Standards, Paris Agreement alignment, and the EU Taxonomy.
In a bid to strengthen internal capabilities, the manager says that the division is piloting a geospatial risk platform developed with Frontierra that provides location-based insights into climate- and nature-related risks and opportunities. Following development, the platform entered initial testing and implementation across infrastructure, investment and portfolio management teams during FY2026. FGEN also obtained third-party assurance over key sustainability metrics in accordance with ISAE 3000 and intends to repeat this annually in line with sustainability reporting practice.
Ongoing management
Day-to-day facilities management, operation and maintenance are generally outsourced, with the managers overseeing these arrangements, approving payments, identifying opportunities that may improve efficiency and capacity, and reviewing project SPV financial structures.
Disposals and hedging
FGEN typically holds assets for the long term, but may dispose of investments where the managers believe the sale price is attractive or where there are other reasons to sell.
The managers may hedge non-sterling currency exposure, as well as interest-rate, inflation, power-price and commodity-price risks. All hedging decisions are subject to board discretion.
Sustainability
FGEN voluntarily discloses under Article 9 of the Sustainable Finance Disclosure Regulation (SFDR) and has a sustainable investment objective. Although, as a Guernsey company, it falls outside the UK Sustainability Disclosure Requirements (SDR) and associated labels, it voluntarily aligns with the SDR Sustainability Focus label and publishes the relevant disclosures.
During the year ended 31 March 2026, the portfolio generated 1,338GWh of renewable energy (2025: 1,272GWh), treated more than 35.8bn litres of wastewater (2025: 34.7bn litres) and diverted more than 653,464 tonnes of waste from landfill (2025: 703,470 tonnes).
GHG emissions avoided during FY2026 totalled 223,140 tCO₂e, while total portfolio emissions (Scope 1, 2 and 3) were 128,308 tCO₂e.
Foresight Group is a signatory to the United Nations Principles for Responsible Investment (UNPRI). In FY2026, Foresight Group was awarded five-star ratings across both the Policy, Governance and Strategy module and the Infrastructure division. ESG analysis is incorporated in both FGEN’s investment process and ongoing portfolio monitoring. More information is included in the ESG section above.
Asset allocation
FGEN has a portfolio that includes investments in 10 sectors across 39 projects. The manager splits the portfolio into three key environmental infrastructure pillars: renewable energy generation (71% of the portfolio – wind, solar, AD, biomass, energy from waste, and hydropower); other energy infrastructure (11% – battery energy storage and low carbon transport assets); and sustainable resource management (18% – waste and water management assets and controlled environment assets).
Figure 5: Portfolio value split by sector, as at 31 March 2026
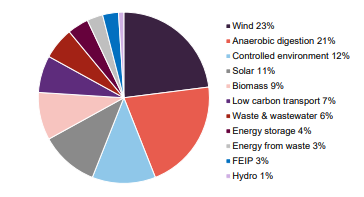
Figure 6: Portfolio split by remaining asset life as at 31 March 2026
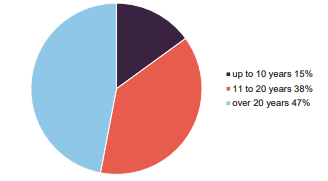
Figure 5 displays FGEN’s portfolio by project type, as at 31 March 2026. The weighted average remaining asset life of the portfolio increased to 18.5 years from 16.2 years, following the extension of the lives of some of its AD assets, as discussed earlier. Most of its portfolio (90%) is located in the UK, with the 10% outside the UK accounted for by FGEN’s Italian and Norwegian investments.
Figure 7: Portfolio split by operational status as at 31 March 2026
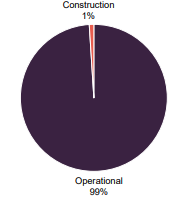
Figure 8: Net present value of future revenues by type as at 31 March 2026
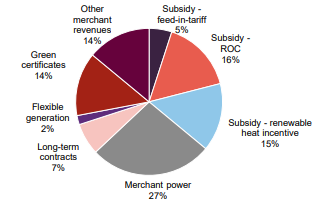
FGEN’s construction exposure has fallen below 1%, with early-stage assets, including the Rjukan project, transferring to operational.
The top 10 largest assets make up 56% of the total portfolio value. Figure 9 details the assets in FGEN’s portfolio, at 31 March 2026. The company’s exposure to individual assets appears to be low, with no asset accounting for more than 10% of the portfolio.
Figure 9: FGEN portfolio1 of projects by type, as at 31 March 2026
| Asset | Location | Type | Ownership | Capacity(MW) | Commercial operations date |
|---|---|---|---|---|---|
| Renewable energy generation | |||||
| Bilsthorpe | UK (Eng) | Wind | 100% | 10.2 | Mar 2013 |
| Burton Wold Extension | UK (Eng) | Wind | 100% | 14.4 | Sep 2014 |
| Carscreugh | UK (Scot) | Wind | 100% | 15.3 | Jun 2014 |
| Castle Pill | UK (Wal) | Wind | 100% | 3.2 | Oct 2009 |
| Dungavel | UK (Scot) | Wind | 100% | 26.0 | Oct 2015 |
| Ferndale | UK (Wal) | Wind | 100% | 6.4 | Sep 2011 |
| Hall Farm | UK (Eng) | Wind | 100% | 24.6 | Apr 2013 |
| Llynfi Afan | UK (Wal) | Wind | 100% | 24.0 | Mar 2017 |
| Moel Moelogan | UK (Wal) | Wind | 100% | 14.3 | Jan 2003 & Sep 2008 |
| New Albion | UK (Eng) | Wind | 100% | 14.4 | Jan 2016 |
| Wear Point | UK (Wal) | Wind | 100% | 8.2 | Jun 2014 |
| Biogas Meden | UK (Eng) | Anaerobic digestion | 49% | 5.3 | Mar 2016 |
| Egmere Energy | UK (Eng) | Anaerobic digestion | 49% | 6.3 | Nov 2014 |
| Grange Farm | UK (Eng) | Anaerobic digestion | 49% | 6.3 | Sep 2014 |
| Icknield Farm | UK (Eng) | Anaerobic digestion | 53% | 7.4 | Dec 2014 |
| Merlin Renewables | UK (Eng) | Anaerobic digestion | 49% | 6.3 | Dec 2013 |
| Peacehill Farm | UK (Scot) | Anaerobic digestion | 49% | 6.8 | Dec 2015 |
| Rainworth Energy | UK (Eng) | Anaerobic digestion | 100% | 2.2 | Sep 2016 |
| Vulcan Renewables | UK (Eng) | Anaerobic digestion | 49% | 12.6 | Oct 2013 |
| Warren Energy | UK (Eng) | Anaerobic digestion | 49% | 6.3 | Dec 2015 |
| Amber | UK (Eng) | Solar | 100% | 9.8 | Jul 2012 |
| Branden | UK (Eng) | Solar | 100% | 14.7 | Jul 2013 |
| CSGH | UK (Eng) | Solar | 100% | 33.5 | Mar 2014 & Mar 2015 |
| Monksham | UK (Eng) | Solar | 100% | 10.7 | Mar 2014 |
| Pylle Southern | UK (Eng) | Solar | 100% | 5.0 | Dec 2015 |
| Codford Biogas | UK (Eng) | Waste anaerobic digestion | 100% | 3.8 | 2014 |
| Bio Collectors | UK (Eng) | Waste anaerobic digestion | 100% | 11.7 | Dec 2013 |
| Cramlington Renewable Energy Developments | UK (Eng) | Biomass combined heat and power | 100% | 32.0 | 2018 |
| Energie Tecnologie Ambiente (ETA) | Italy | Energy-from-waste | 45% | 16.8 | 2012 |
| Northern Hydropower | UK (Eng) | Hydropower | 100% | 2.0 | Oct 2011 & Oct 2017 |
| Yorkshire Hydropower | UK (Eng) | Hydropower | 100% | 1.8 | Oct 2015 & Nov 2016 |
| Other energy infrastructure | |||||
| West Gourdie | UK (Scot) | Battery storage | 100% | 50.0 | May 2023 |
| Clayfords | UK (Scot) | Battery storage | 50% | 50.0 | Pre-construction |
| Sandridge | UK (Eng) | Battery storage | 50% | 50.0 | Dec 2025 |
| Asset | Location | Type | Ownership | Capacity(MW) | Commercial operations date |
| CNG Fuels | UK (Eng) | Low carbon transport | Minority2 | n/a | Various |
| Sustainable resource management | |||||
| Glasshouse | UK (Eng) | Controlled environment | 10% | n/a | Mar 2025 |
| Rjukan | Norway | Controlled environment | 25% | n/a | Aug 2025 |
| ELWA | UK (Eng) | Waste management | 80% | n/a | 2006 |
| Tay | UK (Scot) | Wastewater treatment | 33% | n/a | Nov 2001 |
The waste management and wastewater treatment assets – East London Waste Authority (ELWA) and Tay – are subject to PFI contracts that are approaching the end of their concession periods. Some public authorities have attempted to withhold final unitary payments or retain funds within the structure, but FGEN’s manager states that, as yet, there are no indications that handover risk will manifest, particularly given the vintage of the PFI contracts in question have a more limited set of handback conditions compared to later such contracts.
On ELWA, which is due to hand back by the end of 2027, the debt has been fully repaid and FGEN expects to start taking surplus cash (which amounts to around £30m-£40m) out of the project over the next two years.
The two controlled environment projects in FGEN’s portfolio are both now operational and production is increasing, with the Glasshouse increasing commercial activity and Rjukan producing and harvesting trout. Meanwhile, FGEN’s other growth asset, CNG Fuels, continues to scale its renewable biomethane platform.
FGEN has indicated that it could sell these assets over the medium term once operations have fully ramped up, subject to value and timing. If so, the manager says that the disposal proceeds would be reinvested into new environmental infrastructure opportunities that are intended to balance income, growth and risk, and does not expect to make further standalone controlled-environment investments (given it has stated new investments will retain a more disciplined focus on core environmental infrastructure).
Any new investment would be expected to share the investment characteristics of traditional infrastructure including inflation linkage, high barriers to entry, stable cash flows, and predictable output profiles. The manager states that these characteristics are more important to it than a particular sector.
Portfolio activity
FGEN made no acquisitions and disposals since our last note in December, but did make several follow-on investments, including into carbon capture across three AD assets, further investment into the pressure reduction system at the Vulcan AD, and a debt investment into CNG Fuels.
Distributions from FGEN’s portfolio were £78.6m over the year to 31 March 2026 – a shortfall of 2.9% (or £2.3m) against budget, although the company expects to recover around £4.2m through contractual compensation mechanisms. Solar and wind assets were 10.0% and 12.5% below target respectively. Meanwhile, AD assets were 19.0% above budget.
FGEN’s largest asset, the Cramlington biomass scheme (which accounts for 9% of portfolio value), generated 25.2% below target in the year, mainly due to a six-week extension of a planned outage in July and recurring boiler issues. Expected compensation reduces the shortfall to 15.7%. Following remediation works, FGEN’s manager states that plant reliability and availability has improved, with performance exceeding budget since March.
Performance
FGEN’s NAV returns appear to have started to pick up over the past year perhaps as a result of organic growth within its portfolio feeding through to valuations. This follows a flat three years as the sector appears to have faced substantial headwinds.
Figure 10: FGEN NAV TR over five years to 30 June 2026
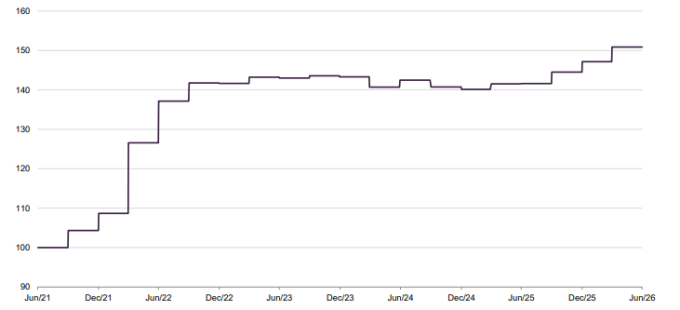
Figure 11: FGEN cumulative performance to 30 June 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| FGEN NAV total return | 0.0 | 2.5 | 6.5 | 5.5 | 50.9 |
| FGEN share price total return | 28.2 | 36.2 | 17.9 | 6.4 | 27.2 |
Peer group
Figure 12: AIC renewable energy infrastructure sector comparison table, as at 15 July 2026
| Market cap (£m) | Premium/(discount) (%) | Yield(%) | Ongoing charge (%) | 1 yr NAV TR (%) | 3 yr NAV TR (%) | 5 yr NAV TR (%) | 10 yr NAV TR (%) | |
|---|---|---|---|---|---|---|---|---|
| FGEN | 530 | (19.3) | 9.4 | 1.11 | 8.6 | 2.3 | 9.0 | 7.7 |
| Aquila European Renewables Income | 53 | (63.6) | 31.3 | 1.20 | (23.0) | (14.8) | (6.4) | – |
| Bluefield Solar Income | 546 | (11.8) | 9.7 | 1.02 | (2.8) | (2.6) | 4.9 | 7.6 |
| Ecofin US Renewables Infrastructure | 15 | (50.6) | 0.0 | 2.30 | (7.1) | (26.0) | (14.6) | – |
| Foresight Solar | 387 | (28.6) | 11.4 | 1.15 | (1.1) | 0.7 | 7.2 | 6.6 |
| Gore Street Energy Storage Fund | 249 | (43.2) | 8.1 | 1.38 | (10.6) | (3.6) | 3.1 | – |
| Greencoat Renewables | 683 | (26.0) | 9.2 | 1.18 | 3.6 | 3.1 | 6.3 | – |
| Greencoat UK Wind | 2,235 | (23.0) | 10.3 | 0.83 | 0.8 | (0.4) | 8.0 | 9.0 |
| Gresham House Energy Storage | 544 | (16.6) | 0.4 | 1.16 | 6.5 | (6.7) | 3.6 | – |
| NextEnergy Solar | 275 | (37.4) | 17.6 | 1.17 | (8.7) | (3.4) | 2.6 | 4.4 |
| Octopus Renewables Infrastructure | 331 | (33.0) | 10.0 | 1.22 | (0.2) | 1.0 | 4.8 | – |
| SDCL Efficiency Income | 422 | (50.2) | 16.4 | 1.05 | (11.5) | (3.3) | (0.0) | – |
| The Renewables Infrastructure Group | 1,711 | (29.9) | 10.3 | 0.94 | 3.3 | (1.7) | 4.2 | 7.0 |
| US Solar Fund | 82 | (42.6) | 6.3 | 1.61 | (0.8) | (6.4) | (2.6) | – |
| VH Global Energy Infrastructure | 291 | (29.3) | 7.9 | 1.50 | 7.4 | 2.9 | 5.7 | – |
| Peer group median | 387 | (29.9) | 9.7 | 1.17 | (0.8) | (2.6) | 4.2 | 7.3 |
| FGEN rank | 6/15 | 3/15 | 9/15 | 5/15 | 1/15 | 3/15 | 1/15 | 2/6 |
You can access up-to-date information on FGEN and its peers on the QuotedData website.
FGEN has one of the broader remits of the 15 companies that comprise the members of the AIC’s renewable energy infrastructure sector. Most of these funds are focused on solar or wind or some combination of the two. Two of these funds are focused solely on energy storage. There is variation of geographic exposure within the peer group too, with a number of funds that are heavily exposed to the North American market (which has a different risk/reward structure).
The sector has been shrinking through a combination of private acquisitions (taking advantage of what appear to be wide discounts in the sector) or through managed wind-downs. The sector has lost Aquila Energy Efficiency and Hydrogen Capital Growth to managed wind-downs since our last note. Meanwhile, Bluefield Solar Income’s board has recommended the sale of the company to Drax Group and US Solar Fund has also received a bid for its portfolio. Meanwhile, NextEnergy Solar has put itself up for sale and Aquila European Renewables Income is in a managed wind-down.
A proposed merger of The Renewables Infrastructure Group (TRIG) with InfraRed Capital stablemate HICL Infrastructure was abandoned last year following shareholder opposition. TRIG passed a continuation vote at the end of June 2026.
FGEN is one of the larger funds within this peer group. Its discount is one of the narrowest in the peer group, which may reflect the composition of its diversified portfolio. FGEN’s yield is higher than some peers, with coverage of 1.25x. Its ongoing charges ratio is among the lowest in the peer group, following a reduction in the management fee. Its NAV returns are among the highest in the peer group over all time periods.
Dividend
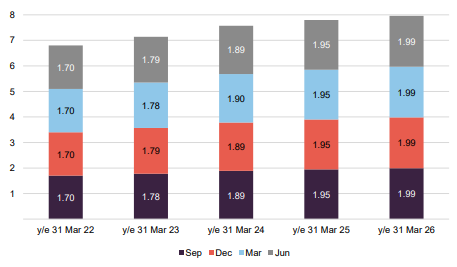
FGEN has a progressive dividend policy and has grown the dividend every year since launch. For the accounting year ended 31 March 2026, the company declared a dividend of 7.96p (up 2.1% from 7.80p in 2025), which was 1.25x covered by net cash flows from the portfolio. The board said that it was targeting a total dividend of 8.04p for the 2027 financial year, representing a 1.0% increase, and expects this to be covered by cash flows.
Figure 13: FGEN five-year dividend history, pence per share
Premium/(discount)
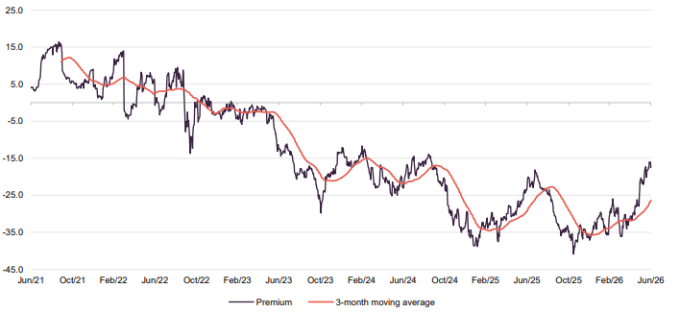
FGEN’s discount had been narrowing from all-time lows that followed the government proposals to bring forward the change in the inflation measure for incentives at the end of 2025.
Over the year to 30 June 2026, FGEN’s shares traded in range of a 16.0% and a 40.9% discount to NAV, and averaged a discount of 29.5%. FGEN’s discount at 14 July 2026 was at 17.5%.
The company is again facing a continuation vote at its AGM in September, as its discount averaged more than 10% over FY2026. Shareholders have voted for continuation in the previous two years, and the board has said that it is confident of the same outcome this time.
Figure 14: FGEN premium/(discount) (%) over five years to 30 June 2026
Fees and costs
FGEN’s ongoing charges ratio for the year ended 31 March 2026 was 1.11% (2025: 1.24%). The board expects the ongoing charges ratio to fall to 1.05% for FY2027, factoring in the full benefit of the investment management fee reduction and assuming no change in NAV.
The investment management fee was reduced in October 2025 and is now calculated 50% based on NAV and 50% on market capitalisation (capped at NAV), having changed from a tiered structure based on NAV in October 2025. The change appears to have reduced the investment management fee from £7.2m in 2025 to £5.8m in 2026.
There is no performance fee, and the manager’s contract can be terminated on one year’s notice.
For the year ended 31 March 2026, directors’ fees and expenses totalled £314,000 (2025: £327,000) and the administration fee was about £110,000 (2025: £124,000).
Capital structure
FGEN has 623,338,335 ordinary shares in issue and 38,192,894 shares held in treasury, as at 15 July 2026.
FGEN has an indefinite life, but a continuation vote may be triggered if its shares trade at a discount in excess of 10% for a prolonged period (which was the case in the financial years 2024, 2025 and 2026). The company’s financial year end is 31 March and AGMs are typically held in August or September.
Gearing
FGEN has a £150m multi-currency RCF that at 31 March 2026 was £123.1m drawn. In April, FGEN signed a one-year extension to the RCF and activated a £15m accordion facility. The additional capacity may provide greater headroom to fund existing portfolio commitments.
The RCF – which is provided by National Australia Bank, Royal Bank of Scotland International, ING, HSBC, and Clydesdale Bank – matures in June 2028.
The loan bears interest of SONIA (for sterling drawdowns) and EURIBOR (for euro drawdowns) +210bps. Interest charged is linked to meeting certain agreed sustainability goals, with the rate rising or falling 5bps based on performance against these ESG targets:
Environmental: increase coverage of independent biodiversity assessments and implement initiatives to enhance biodiversity net gain across the portfolio;
Social: increased volume of contributions to local communities; and
Governance: maintaining a low number of work-related accidents, as defined under the Reporting of Injuries, Diseases and Dangerous Occurrences (RIDDORS) by the Health and Safety Executive.
At the project level, FGEN is constrained to a maximum of 65% gearing on gross project value for renewable energy generation projects and a maximum of 85% gearing on gross project value for PFI/PPP type projects. In practice, actual project gearing appears to be lower than this. At 31 March 2026, project-level gearing across the portfolio was 16.1%.
Including the amount drawn under the RCF, FGEN’s gearing ratio was 28.8% at 31 March 2026.
Major shareholders
FGEN’s largest shareholders at 31 March 2026 were Hargreaves Lansdown (8.36%), Interactive Investor (6.39%) and Gravis Capital Management (6.26%).
Lead managers
Edward Mountney
Edward has been a part of FGEN since 2016 and joined the senior management team in 2022. Before this, he served as head of valuations at Foresight Group and John Laing Capital Management. Edward has over 15 years of experience in infrastructure and renewables and is a member of the Institute of Chartered Accountants in England and Wales. He holds a BA (Hons) in Business and Management from Oxford Brookes University.
Charlie Wright
Charlie joined Foresight Group in 2017 and has recently joined FGEN’s senior management team. He has over 19 years of experience in infrastructure and renewables as an adviser, equity investor and project director, and has overseen a range of investments across Europe. Charlie previously worked at John Laing Group and KPMG. He holds a BA in History from Exeter University and an ICAEW & CISI Diploma in Corporate Finance.
Board
FGEN’s board is currently composed of five directors, all of whom are non-executive and considered to be independent of the investment manager.
Chair Ed Warner announced that he will step down from the board at the AGM in September. He will be replaced by current senior independent director Stephanie Coxon. Alan Bates will resume the role of senior independent director, and a search is underway for a new board member.
Figure 15: Board members – length of service and shareholdings
| Director | Position | Date of appointment | Length of service (years) | Annual fee (GBP) | Shareholding |
|---|---|---|---|---|---|
| Ed Warner | Chair | 2 August 2022 | 3.9 | 85,000 | 75,000 |
| Stephanie Coxon | Audit committee chair | 11 June 2020 | 6.0 | 65,500 | 65,000 |
| Alan Bates | Risk committee chair | 10 June 2021 | 5.0 | 55,500 | 25,000 |
| Jo Harrison | ESG committee chair | 10 June 2021 | 5.0 | 55,500 | 8,066 |
| Nadia Sood | Director | 10 February 2023 | 3.4 | 53,000 | 6,796 |
Ed Warner
Ed gained financial services experience from senior positions held at several investment banks and financial institutions, including IFX Group, Old Mutual, NatWest Markets and Dresdner Kleinwort Benson. He also has investment trust experience, having been chair of both Standard Life Private Equity Trust Plc and BlackRock Energy and Resources Income Trust Plc. He is currently chair of HarbourVest Global Private Equity. Ed has also previously served as chair of Air Partner Plc and non-executive director and interim chair of Clarkson Plc.
Stephanie Coxon
Stephanie is a fellow of the Institute of Chartered Accountants in England and Wales and is currently a non-executive director of several London listed companies. Prior to her non-executive director career, she led the investment trust capital markets team at PwC for the UK and Channel Islands. During her time at PwC, Stephanie specialised in advising FTSE 250 and premium London listed companies on accounting, corporate governance, risk management and strategic matters.
Alan Bates
Alan has over 33 years’ experience in the energy and infrastructure sectors, including electricity, gas and water utilities. He has developed an understanding of the dynamics behind the energy transition and has assisted the government of Guernsey in developing its energy policy. Alan started his career with P&O and Princess Cruises as a Marine Engineering Officer, followed by 19 years in the oil and gas industry working for Mobil Oil/BP Oil and then International Energy Group before becoming the managing director of Manx Gas in the Isle of Man. He is the CEO of Guernsey Electricity and is a director of the Channel Islands Electricity Grid and Alderney Electricity Limited. Alan is a Chartered Engineer, Fellow of the Institute of Mechanical Engineers and a Member of the Institute of Engineering Technology.
Jo Harrison
Jo has over 25 years’ experience working in the water industry and is the director of strategic planning & sustainability at United Utilities, where she is responsible for leading the approach to environmental and long‑term planning, including developing and maintaining the approach to aspects of the environment, climate change and carbon, asset strategy, risk and resilience. Jo is a chartered member of the Institute of Water and Environmental Managers and is a Chartered Environmentalist. She is also a trustee of the Rivers Trust.
Nadia Sood
Nadia has experience of executing, managing and overseeing complex infrastructure investments. She has run renewable energy infrastructure investment portfolios worth billions of dollars in multiple countries and served as a director on the board of more than 20 privately owned companies. Nadia is currently CEO of CreditEnable, a credit insights and technology solutions company, and a member of the IFC/World Bank SME Finance Forum. She holds a Bachelor of Science in Foreign Service from the Edmund A. Walsh School of Foreign Service at Georgetown University in Washington D.C., and a Masters in International Affairs from Columbia University, New York. Nadia is fluent in English, French and Norwegian.
Previous publications
You can read our previous notes on FGEN by clicking on them below or by visiting our website.
Figure 16: QuotedData’s previously published notes on FGEN
| Title | Note type | Date |
|---|---|---|
| Diverse renewables exposure | Initiation | 6 September 2017 |
| Anaerobic diversification | Update | 6 March 2018 |
| Diversification benefits shine through | Annual overview | 12 September 2018 |
| Life extensions to boost NAV? | Update | 15 March 2019 |
| Battery storage potential | Annual overview | 9 September 2019 |
| Reliable source of income | Update | 14 May 2020 |
| Increasingly diversified as green-led recovery looms | Annual overview | 16 February 2021 |
| On the front foot | Update | 4 August 2021 |
| It’s all about renewables | Annual overview | 29 March 2022 |
| Further portfolio diversification | Update | 29 September 2022 |
| Laying the foundations for NAV growth | Annual overview | 31 March 2023 |
| Backing the green hydrogen revolution | Update | 28 November 2023 |
| Vote against discontinuation | Annual overview | 17 July 2024 |
| Looking to bounce back | Update | 3 December 2024 |
| Strategic refresh | Annual overview | 21 July 2025 |
| Pushing on despite regulatory upheaval | Update | 17 December 2025 |
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Foresight Environmental Infrastructure Limited.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it.
Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.