
The elastic band stretches further
Montanaro UK Smaller Companies (MTU) invests in three areas currently out of favour: the UK, small caps, and high-quality companies. While its portfolio companies are still growing revenues and earnings, this is not reflected in their share prices, which has hurt MTU’s performance. The manager believes patient investors will be rewarded over time. Meanwhile, MTU offers an attractive dividend yield, helping to keep its share price discount to NAV relatively narrow.
Large withdrawals from the UK small-cap market have put pressure on valuations, but if sentiment improves, a strong rebound could follow.
Access to some of the UK’s best small companies, and a high yield
MTU aims to achieve capital appreciation through investing in small quoted companies listed on the London Stock Exchange or traded on AIM, and to outperform its benchmark, the Deutsche Numis Smaller Companies Index (excluding investment companies). MTU also provides shareholders with an attractive yield of approximately 6% of NAV.
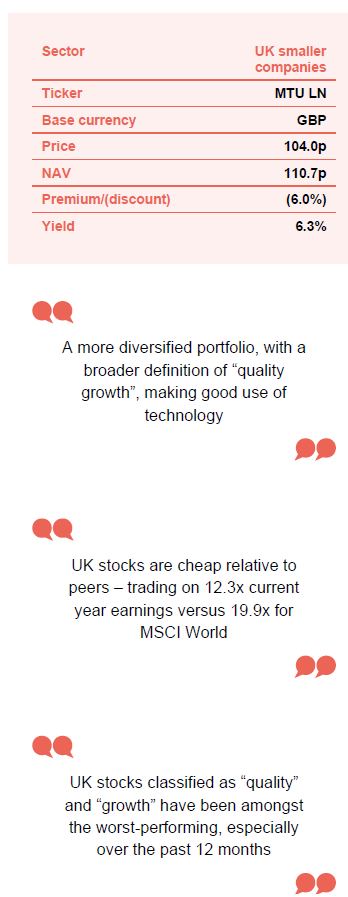
At a glance
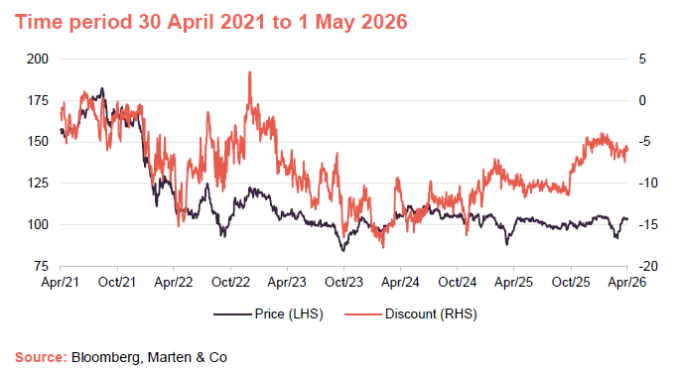
Share price and discount
Over 2026, MTU’s share price discount to net asset value (NAV) appears to have settled in the mid-single digits, which is the narrowest in its peer group. The adoption of the enhanced dividend strategy in December 2024 has likely contributed to MTU’s narrower discount as has its share buyback programme.
MTU buys back its shares when the opportunity arises, and since the start of 2025 it has bought back over 30% of its shares.
Performance over five years
MTU’s quality-focus has held back returns relative to comparative indices and that has pushed it towards the lower end of the peer group rankings over most time periods. However, performance appears to be improving in 2026.
Three months is too short a period to draw firm conclusions from, but – relatively, at least – the three-month numbers are better.
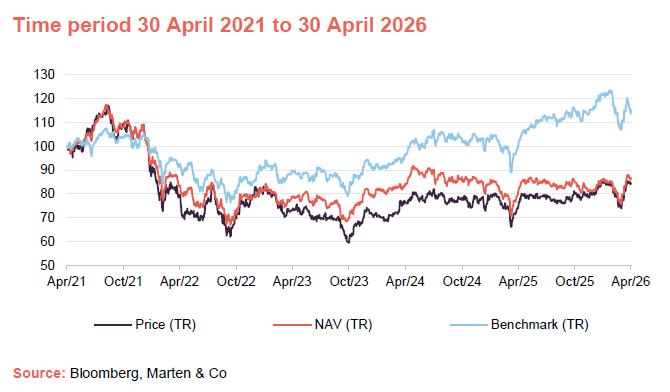
| 12 months ended | Share price total return (%) | NAV total return (%) | Deutsche Numis Small Cap ex Inv Cos TR (%) | MSCI UKtotal return (%) |
|---|---|---|---|---|
| 30/04/2022 | (20.4) | (16.4) | (7.4) | 15.6 |
| 30/04/2023 | (7.9) | (5.6) | (3.0) | 8.3 |
| 30/04/2024 | 4.8 | 6.3 | 7.2 | 7.7 |
| 30/04/2025 | (2.9) | (3.6) | 4.0 | 8.1 |
| 30/04/2026 | 13.5 | 7.3 | 15.0 | 26.6 |
Fund profile – a strengthened investment process
More information is available at the manager’s website www.montanaro.co.uk/muscit
MTU invests long-term in high-quality UK smaller companies, aiming for capital growth and an attractive dividend yield of 1.5% of NAV each quarter, or about 6% per year, funded by both revenue and capital gains.
Montanaro Asset Management Limited (MAML) is the trust’s manager. Founded 35 years ago by Charles Montanaro, who still leads MTU, the firm has over £2bn in assets, no debt, no outside shareholders, and a strong client base. This stability supports a long-term investment approach, including continued investment in its team even during market downturns.
One of the largest teams in Europe focused on researching and investing in quoted small- and mid-cap companies
MAML has one of Europe’s largest teams focused on small- and mid-cap companies, soon to expand with three new hires. The team is diverse and experienced, with half having worked at MAML for over a decade. Team members own about 35% of the firm and are encouraged to invest alongside clients, aligning interests and fostering a family-like culture.
We provided a detailed description of MAML’s stock selection approach in our last note. While MAML’s investment philosophy and disciplined process remain unchanged, the manager continually seeks to improve outcomes. In response to a challenging economic environment, MAML has broadened and diversified MTU’s portfolio, increasing the target number of holdings to 50–60 and expanding its definition of quality growth to include both structural and cyclical growth companies.
A more diversified portfolio, with a broader definition of “quality growth”, making good use of technology
MAML has also invested in new systems, including a proprietary data insights platform and secure AI tools. These help analysts and managers identify investment themes, speed up due diligence, incorporate real-time data, spot accounting issues, and analyse third-party insights. This automation frees up time for higher-value analysis and discussion.
Sustainability remains central to MAML’s approach. The firm has managed an impact strategy for over a decade and became a B Corp in 2019.
MTU is benchmarked against the Deutsche Numis Smaller Companies Index and the MSCI UK Index, but these benchmarks do not influence stock selection or position sizes.
UK, quality, and small-cap are all out of favour
UK stocks are cheap relative to peers – 12.3x current year earnings versus 19.9x for MSCI World
Figure 1 shows that UK stocks have lagged behind global peers for over a decade, though the decline has recently levelled off. Brexit, weak public finances, and high energy costs are often blamed for this trend.
UK large-cap stocks are heavily weighted towards value sectors. After the 2008 financial crisis, investors preferred growth stocks, which hurt UK performance while interest rates and inflation stayed low. This trend reversed at the end of 2021, leading to a slight improvement in the UK’s relative performance.
Figure 1: MSCI UK versus MSCI ACWI
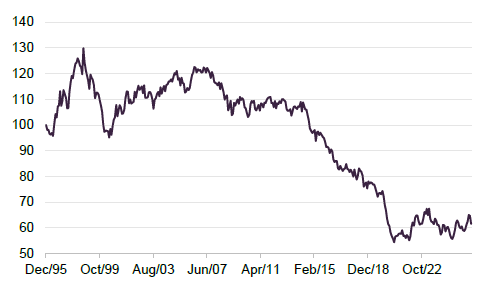
Figure 2: MSCI ACWI Quality versus MSCI ACWI
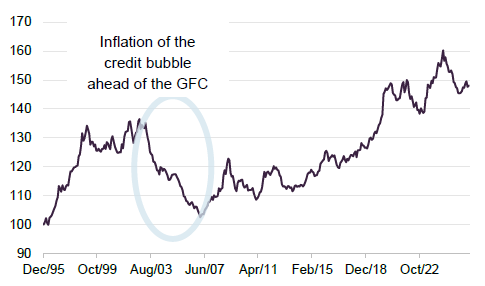
UK stocks classified as “quality” and “growth” have been amongst the worst-performing, especially over the past 12 months
Recently, quality stocks have also underperformed after years of strong returns. Figure 2 highlights the global context, while Figure 3 shows the UK market performance, with particularly wide differences in one-year returns.
Figure 3: Returns of MSCI UK style factor indices for periods ending 30 April 2026
| 5 years annualised (%) | 3 years annualised (%) | 1 year (%) | YTD (%) | |
|---|---|---|---|---|
| MSCI UK | 13.0 | 13.8 | 26.6 | 6.2 |
| Growth | 7.6 | 7.1 | 10.9 | 1.4 |
| Value | 16.4 | 18.2 | 38.2 | 9.6 |
| Quality | 5.7 | 6.6 | 4.8 | (0.9) |
| Momentum | 12.4 | 18.2 | 22.2 | 3.4 |
Quality style investments have underperformed mainly because they became too expensive, especially during COVID. More recently, worries about AI disrupting the business models of software and data companies once seen as high quality have also hurt share prices.
The underperformance of small cap versus large cap may be coming to an end
Small caps have also lagged behind large caps for some time, but there are signs this trend may be reversing in some countries. Figure 4 shows UK small caps fell sharply compared to large caps from August 2021, as interest rate rise expectations grew. However, the strong run for small caps after March 2020, when COVID hit and rates dropped, now looks like a brief exception in a longer downward trend since 2018.
Figure 4: Deutsche Numis Small Cap ex Investment Companies versus MSCI UK
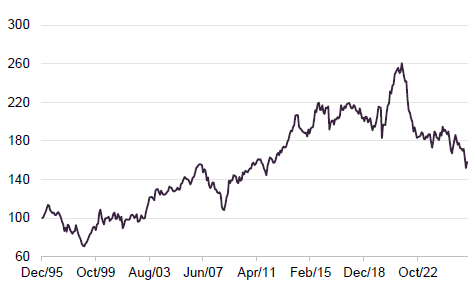
Figure 5: Deutsche Numis Small Cap ex Investment Companies versus Deutsche Numis Large Cap
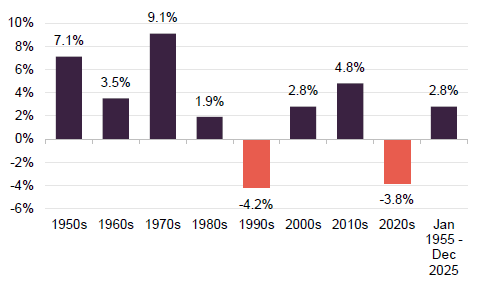
Figure 5, using MAML data, shows that over 70 years, small caps have outperformed large caps by 2.8% per year, leading to returns nearly six times higher. This is because small companies can grow faster, adapt quickly, and are often mispriced due to less research coverage.
Prolonged periods of small-cap underperformance have happened before, but do not last forever
The 1990s were an anomaly, marked by repeated crises of confidence – the oil price spike associated with the First Gulf War, the bursting of Japan’s asset bubble, the Asian financial crisis, the collapse of LTCM, the Russian financial crisis, and the rise of the dotcom bubble. There are clear parallels with today’s environment. The key message, though, is that this period passed and small caps eventually returned to form.
Valuations are cheap which suggests upside to come
MAML saw some improvement in MTU’s returns in Q1 2026, ranking in the top quartile of UK small-cap funds according to Bloomberg. There was a slight improvement for small-cap growth over value, and for the first time since 2020, AIM stocks outperformed main market small-caps. This suggests the underperformance of small caps versus large caps may be ending.
Figure 6: UK small-cap 12m forward P/E
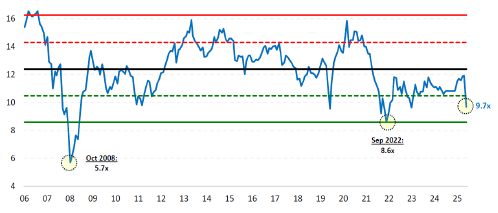
Figure 7: UK small- versus large-cap P/E
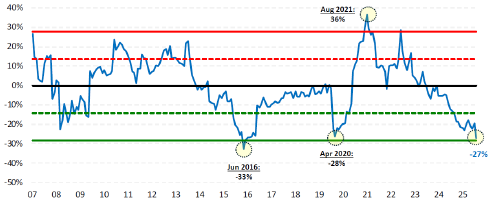
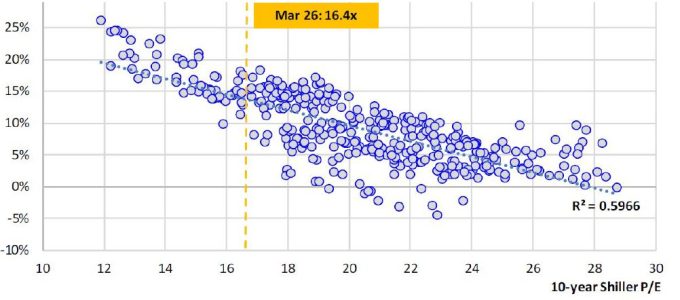
UK small caps still have significant potential, as shown by their low valuations compared to larger UK stocks (see Figures 6 and 7). Figure 8 shows annualised five-year total returns on the Numis Smaller Companies Index since December 1978. The chart compares the starting cyclically-adjusted (Shiller) P/E ratio with the following five-year return. Based on a starting P/E of 16.4x at the end of March 2026, returns could range from 10% to 20% per year over the next five years.
It is difficult to predict what will change investor sentiment, but a re-rating of UK small caps is easier to see. Over the past four years, UK small-cap funds have seen £4.9bn in net outflows, according to the Investment Association. If returns improve, this could attract new investment and create a positive cycle where more interest leads to further gains.
Figure 8: UK small- cap annualised five-year return versus starting 10-year Shiller P/E
Asset allocation
As of 31 March 2026, MTU held 59 companies, up from 40 a year earlier, showing the impact of recent improvements to its investment process.
Over the past year, the portfolio increased its exposure to basic materials by 6 percentage points and reduced its technology holdings by 9 points.
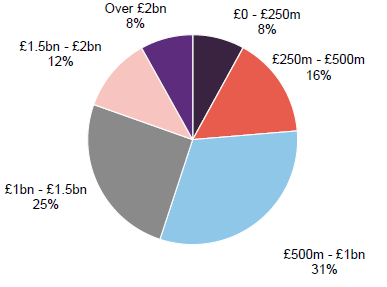
There has also been a shift towards smaller companies, especially those valued between £250m and £500m, as the manager found new opportunities in this range.
The portfolio remains quite different from its benchmark, with an active share of 81.8%. It is also slightly less volatile, with a beta of 0.88 and a three-year standard deviation of 14.2%, compared to the index’s 14.8%.
Figure 9: MTU sector split at 31 March 2026
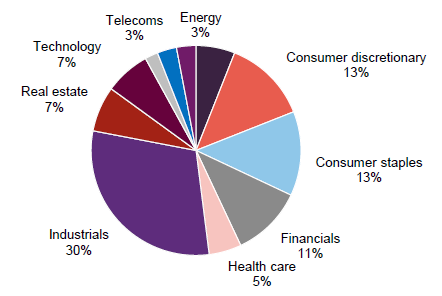
Figure 10: MTU sector split at 31 March 2025
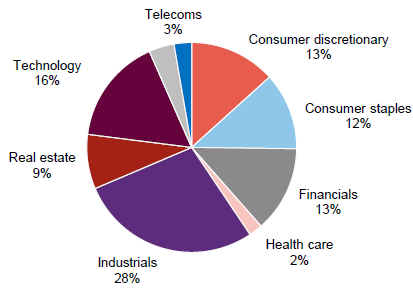
Figure 11: MTU split by market cap at 31 March 2026
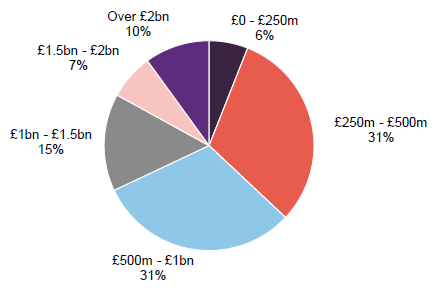
Figure 12: MTU split by market cap at 31 March 2025
At the end of March 2026, the portfolio was valued at just 13.6 times 2026 earnings or 10.3 times EV/EBITDA, highlighting the value in UK small caps. This comes with expected annual earnings growth of 12.8% and a return on equity of 14.4%. The portfolio’s balance sheets are strong, with average net debt to equity of only 0.4%.
About 52% of portfolio revenues come from the UK, 19% from North America, 12% from Western Europe, and 8% from Asia.
Top 10 holdings
Since our last note, which used 31 March 2025 data, there have been six new entrants to MTU’s top 10: IntegraFin Holdings, Bloomsbury Publishing, Cranswick, MP Evans, Luceco, and XP Power.
These replaced Telecom Plus (whose shares fell on the back of weak profit figures in its interim results), Baltic Classifieds (which sold off after a broker downgraded its forecasts to reflect the impact of a new vehicle tax in Estonia, and has since been perceived as threatened by agentic AI), Porvair (which is still in the top 20), 4Imprint (which was perceived as being particularly threatened by the imposition of tariffs, but actually managed to deliver flat revenue and profits for 2025 over 2024), Bytes Technology Group, and JTC.
Bytes Technology and JTC were exits during Q1 2026. JTC was taken over by Permira at a 50% premium. Bytes Technology performed poorly after posting some disappointing figures, coupled with a poorly handled internal reorganisation.
Figure 13: MTU top 10 equity holdings at 31 March 2026
| Business | % as at 31 March 2026 | % as at 31 March 2025 | Change (%) | |
|---|---|---|---|---|
| IntegraFin Holdings | Software and computer services | 3.8 | 2.4 | 1.4 |
| discoverIE | Electronic and electrical equipment | 3.8 | 5.2 | (1.4) |
| Bloomsbury Publishing | Media | 3.8 | 2.8 | 1.0 |
| Cranswick | Food producer | 3.3 | 3.1 | 0.2 |
| XPS Pensions | Pension provider | 3.0 | 4.8 | (1.8) |
| MP Evans | Food producer | 2.9 | 3.2 | (0.3) |
| Luceco | Electronic and electrical equipment | 2.9 | 1.7 | 1.2 |
| XP Power | Electronic and electrical equipment | 2.8 | 1.9 | 1.0 |
| Hilton Food | Food producer | 2.8 | 4.4 | (1.6) |
| Big Yellow | Self-storage | 2.6 | 4.7 | (2.0) |
| Total of top 10 | 31.7 | 40.9 |
Looking at the new entrants in more detail:
IntegraFin Holdings
Figure 14: IntegraFin Holdings
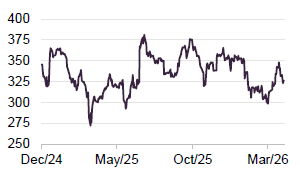
IntegraFin (integrafin.co.uk) runs the Transact investment platform, which managed £77.8bn of assets at the end of March 2026, up 18% from the previous year. Client numbers also rose from 241,000 to 255,000.
The company expects 11% revenue growth for the first half of 2026. Administrative expenses are forecast to rise by just 3% in both 2026 and 2027, supported by cost-saving measures, which should boost earnings.
While investor platforms were thought to be at risk from advances in AI, strong results in early 2026 have eased concerns.
Bloomsbury Publishing
Figure 15: Bloomsbury Publishing
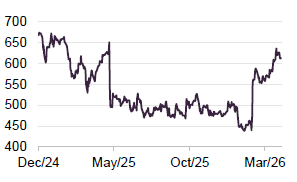
Bloomsbury Publishing (bloomsbury-ir.co.uk) saw its share price fall in May 2025 after annual profits missed expectations. However, a trading update in March 2026 renewed interest in the stock. MAML believes Bloomsbury will benefit from the upcoming Harry Potter TV series and the release of two new Sarah J Maas novels expected in late 2026 and early 2027.
Sarah J Maas was the best-selling author in the US in 2024 and the top Fantasy author in the UK in 2025. Bloomsbury also reports strong performance in its academic publishing division. More details are expected when the company releases its annual results.
Cranswick
Figure 16: Cranswick
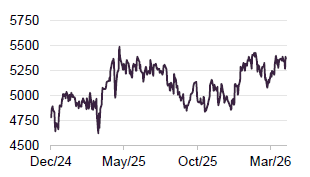
UK premium, fresh and added-value food products business Cranswick (cranswick.plc.uk) has been in MTU’s portfolio for 12 years, delivering a 6.3x return. Its latest trading update for Christmas 2025 was positive, with full-year adjusted profit before tax expected at the higher end of market forecasts.
The company continues to grow both organically and through small acquisitions, such as adding feed mills and genetics production to its pig business last year. It has also invested in expanding its branded and own-label convenience foods.
MP Evans
Figure 17: MP Evans
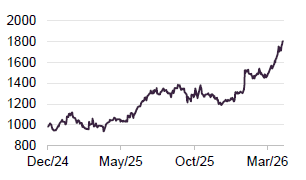
MP Evans (mpevans.co.uk) owns sustainable oil palm plantations in Indonesia and holds a stake in a Malaysian property company. Palm oil, used in many everyday products, has seen steady demand growth. Only about 20% of global supply is certified as sustainable. MP Evans manages over 70,000 hectares.
In 2025, the company’s harvest reached 1.3 million tonnes, up 7% from the previous year. Palm oil prices rose from $823 to $866 per tonne, supporting higher revenue and profits, with earnings per share up 24%. MP Evans has increased its dividend by 14% for 2025, well above inflation. The company is also acquiring more land to support future growth.
Luceco
Figure 18: Luceco
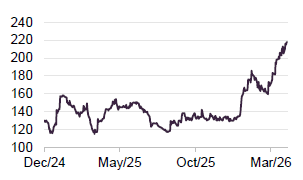
Luceco (lucecoplc.com) is a lighting and electricals company offering products like wiring accessories, LED lighting, and portable power, including EV chargers.
Full-year results for 2025 were strong, with revenue up 12%, margins improving, adjusted operating profit rising 17%, and earnings per share up 20%. The dividend increased by 20%, and the company expects higher profits in 2026. Strong cash flow has left Luceco with a solid balance sheet, supporting potential acquisitions.
MAML points to the success of Luceco’s EV charging products. The company expects a 17% annual growth rate in charger installations to 2030, with potential for even faster growth as a mature market could be six times larger than the 2025 base. This growth is part of the broader shift towards electrification in the UK.
XP Power
Figure 19: XP Power
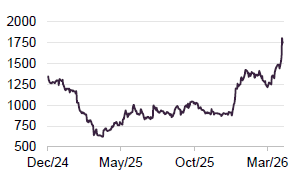
XP Power (corporate.xppower.com) produces AC-DC and DC-DC power supplies, high voltage equipment, RF power, three-phase supplies, and electromagnetic interference filters. Its products are used in healthcare, industry, and semiconductor manufacturing.
US export restrictions affected its Chinese semiconductor business in 2025, and customer destocking followed tariff disruptions. However, MAML now reports rising demand across all segments. In 2025, orders rose by 28%, and the company expects revenue recovery to accelerate in the second half of 2026.
New investments
The evolution of the portfolio, and the emphasis on increased diversification, over the past year is reflected in the long list of new positions. These are listed below, grouped by theme and category, with commentary from MAML.
High growth strategic themes
Electrification, energy transition, and grid upgrade
- Hill & Smith (HILS) – UK-headquartered manufacturer of infrastructure products including road safety barriers, galvanising services and electrical grid components.
- Volex (VLX) – Global manufacturer of power products, cable assemblies and complex wiring systems for electric vehicles, data centres and industrial applications.
- Volution Group (FAN) – Manufacturer and supplier of ventilation products and solutions for residential and commercial buildings across the UK and Europe.
Nuclear
- Avingtrans (AVG) – Buy-and-build acquirer of specialist engineering businesses serving the aerospace, energy and medical sectors.
- Goodwin (GDWN) – Family-controlled UK engineer producing high-integrity castings and refractory products for the energy, defence and petrochemical industries.
Defence, security, and space
- Cohort (CHRT) – A UK group of specialist defence technology companies providing electronic systems, sensors and cyber capabilities to military and government customers.
- Filtronic (FTC) – Designer and manufacturer of radio frequency and microwave electronics for defence, space and telecommunications applications, with notable supply links to SpaceX.
- SRT Marine Systems (SRT) – Developer of maritime vessel tracking and coastal surveillance technology based on AIS, supplying coast guards and navies globally.
Indirect/enabling exposure
Resources nationalism, critical minerals, energy security
- Amaroq (AMRQ) – Gold developer and explorer focused on advancing its large-scale Nalunaq gold project in Greenland.
- Capital Ltd (CAPD) – Diversified mining services company providing drilling, blast-hole and geotechnical services predominantly across Sub-Saharan Africa.
- Ecora Royalties (ECOR) – London-listed royalty and streaming company holding a diversified portfolio of royalties over mining assets including copper, cobalt and other critical minerals.
Infrastructure upgrade/environment
- Renew Holdings (RNWH) – Specialist engineering services provider focused on the maintenance and renewal of UK critical infrastructure including rail, nuclear and water.
- Restore (RST) – Data/storage compliance, demand driven by regulation.
Digitalisation, SaaS, data
- Craneware (CRW) – Provider of SaaS-based financial intelligence and analytics software to US hospital and healthcare systems.
- Elixirr International (ELIX) – Challenger management consulting firm offering strategy, digital transformation and innovation services to blue-chip and high-growth clients globally.
- Pinewood Technologies Group (PINE) – Provider of cloud-based dealer management system (DMS) software to automotive retailers across the UK and international markets.
Domestic/consumer
- A.G. Barr (BAG) – Scottish soft drinks manufacturer best known for the iconic IRN-BRU brand, also producing Rubicon, Funkin and other beverages.
- Angling Direct (ANG) – UK’s largest specialist fishing tackle retailer, but currently the smallest company in MTU’s portfolio, operating stores and an e-commerce platform serving anglers across the UK and Europe.
- Hollywood Bowl Group (BOWL) – Operator of the UK’s largest ten-pin bowling and mini-golf estate, with a growing presence in Canada through its Splitsville brand.
- The Beauty Tech Group (TBTG) – Provider of technology-enabled beauty devices and connected personal care products sold under multiple consumer brands.
Financials and real estate
- Derwent London (DLN) – London-focused office REIT specialising in the creative regeneration of commercial property in the West End and Tech Belt areas.
- FRP Advisory Group (FRP) – Specialist advisory firm focused on restructuring, insolvency, debt and corporate finance across the UK mid-market.
- Mortgage Advice Bureau (MAB1) – UK’s largest directly authorised mortgage broker network, connecting consumers with mortgage advisers across the country.
- Rathbones Group (RAT) – UK-based wealth management firm offering discretionary investment management and financial planning services to private clients and charities.
- Savills (SVS) – Global real estate services firm offering transaction advisory, property management and consultancy across residential and commercial markets worldwide.
Performance
The chart in Figure 20 shows that MTU’s three main features – being UK-based, focused on quality, and small-cap – have all been unpopular with investors. This has contributed to the decline in MTU’s NAV since 2021.
Figure 20: MTU NAV relative to Deutsche Numis Smaller Companies ex Investment Companies Index in total return terms over five years to 30 April 2026
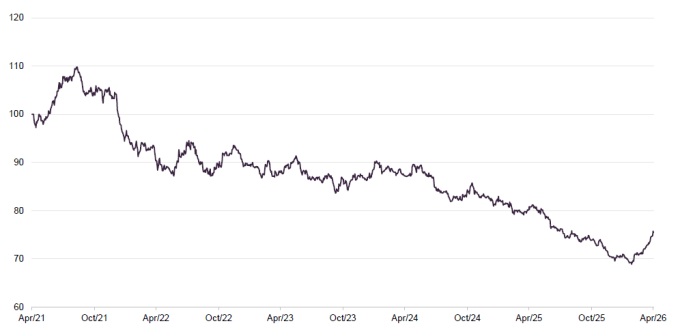
Figure 21: Total return performance over periods ending 30 April 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| MTU share price | 0.0 | 5.6 | 13.5 | 15.5 | (15.4) |
| MTU NAV | 0.8 | 2.3 | 7.3 | 10.0 | (13.2) |
| Deutsche Numis Smaller Companies ex IC | (5.1) | 0.3 | 15.0 | 28.3 | 15.1 |
| Peer group median NAV1 | (4.0) | 1.3 | 10.0 | 11.8 | (14.6) |
| Peer group share price median | (4.8) | 1.5 | 13.7 | 16.1 | (15.9) |
Three months is a short period to judge performance, but Figures 20 and 21 show some improvement. As noted in the peer group section on page 15, MTU ranked second out of eight trusts over this time. The Iran war has delayed the UK small-cap recovery but also made valuations more attractive.
Performance attribution
Figures 22 and 23 show which stocks most affected MTU’s returns compared to its Deutsche Numis ex investment companies Index benchmark during the 12 months to 31 March 2026.
Contributors
Figure 22: Relative performance positive attribution, 12 months to 31 March 2026
| Contribution to return in MTU’s portfolio (%) | Contribution to benchmark return (%) | Contribution to relative return (%) | |
|---|---|---|---|
| XP Power | 1.33 | 0.06 | 1.25 |
| JTC | 1.56 | 0.41 | 0.85 |
| Alpha Group International | 1.24 | 0.48 | 0.81 |
| MP Evans | 0.84 | – | 0.69 |
| Hays | – | (0.46) | 0.59 |
| Total | 4.19 |
XP Power made the largest contribution to returns. JTC, the fund administrator, and Alpha Group International, which handles foreign exchange and payments, were both acquired. MP Evans was covered earlier in the report.
Detractors
Figure 23: Relative performance negative attribution, 12 months to 31 March 2026
| Contribution to return in MTU’s portfolio (%) | Contribution to benchmark return (%) | Contribution to relative return (%) | |
|---|---|---|---|
| Hilton Food | (1.13) | (0.17) | (1.46) |
| Bytes Technology | (1.24) | (0.29) | (1.45) |
| Indivior Pharmaceuticals | – | 1.51 | (1.43) |
| XPS Pensions | (0.81) | (0.10) | (1.37) |
| Baltic Classifieds | (1.07) | (0.30) | (1.19) |
| Total | (6.90) |
Hilton Food
Figure 24: Hilton Food
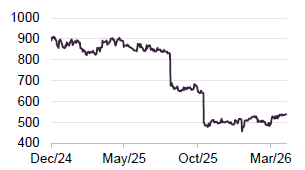
Hilton Food (hiltonfoods.com) is a food processing and packaging company focused on meat, seafood, and vegetarian products. The company recently faced a series of profit warnings, with 2025 earnings per share expected to be 8% lower than 2024. Rising raw material costs hit its Seachill white fish business, while its Foppen smoked salmon operations were disrupted by moving production from Greece to the Netherlands. This shift followed US FDA restrictions due to unsanitary conditions in Greece causing Listeria contamination.
Peer group comparison
For this report, we have selected a peer group of eight investment companies from the AIC‘s UK smaller companies subsector. We excluded very small trusts, those with unusual capital structures, activist strategies, and those focused on micro-cap companies.
MTU’s focus on quality has limited its returns compared to similar indices, placing it near the bottom of peer rankings over most periods. However, its performance is showing signs of improvement in 2026. Aberforth Smaller Companies uses a value approach, which has outperformed in recent years. Artemis Future Leaders was previously Invesco Perpetual UK Smaller Companies, but the 1-year figures in the table reflect its results under the current managers.
MTU’s efforts to manage its discount have reduced the trust’s size, placing it at the smaller end of its peer group, though some even smaller trusts were excluded from this comparison. MTU trades on the narrowest discount among its peers, likely due to its attractive dividend yield – the highest in the group – and active share buybacks. If sentiment improves, MTU could trade at a premium and start issuing new shares.
This peer group generally keeps running costs low, with all excluded trusts having higher ongoing expenses. MTU manages its overheads well, supported by a competitive management fee of 0.50% on net assets.
Figure 25: Listed UK smaller companies peer group NAV total return performance over periods ending 30 April 2026
| 3 months (%) | 6 months (%) | 1 year (%) | 3 years (%) | 5 years (%) | |
|---|---|---|---|---|---|
| MTU | 0.8 | 2.3 | 7.3 | 10.0 | (13.2) |
| Aberdeen UK Smaller Companies Growth | (5.1) | (4.9) | 2.5 | 13.0 | (18.0) |
| Aberforth Smaller Companies | (2.9) | 2.9 | 18.0 | 30.4 | 24.7 |
| Artemis UK Future Leaders | (7.8) | (7.3) | 0.2 | (10.6) | (27.8) |
| BlackRock Smaller Companies | (5.0) | (0.2) | 8.6 | 5.8 | (16.4) |
| Henderson Smaller Companies | (5.0) | 0.4 | 13.9 | 10.5 | (16.0) |
| JPMorgan UK Small Cap Growth & Income | (2.9) | 2.2 | 11.4 | 30.0 | 1.0 |
| Rights & Issues | (3.0) | 2.3 | 14.4 | 16.5 | 4.9 |
| Peer group median | (4.0) | 1.3 | 10.0 | 11.8 | (14.6) |
| MTU rank | 1/8 | 2/8 | 6/8 | 6/8 | 4/8 |
Figure 26: Listed UK smaller companies funds, comparison as at 1 May 2026
| Market cap (£m) | Discount (%) | Dividend yield (%) | Ongoing charge (%) | |
|---|---|---|---|---|
| MTU | 118 | (6.0) | 6.3 | 0.91 |
| Aberdeen UK Smaller Companies Growth | 231 | (8.4) | 2.7 | 0.85 |
| Aberforth Smaller Companies | 1,204 | (11.7) | 3.0 | 0.80 |
| Artemis UK Future Leaders | 102 | (13.5) | 4.5 | 1.00 |
| BlackRock Smaller Companies | 637 | (12.7) | 3.5 | 0.80 |
| Henderson Smaller Companies | 488 | (9.3) | 3.2 | 0.45 |
| JPMorgan UK Small Cap Growth & Income | 400 | (10.3) | 4.5 | 0.76 |
| Rights & Issues | 100 | (19.6) | 2.2 | 1.00 |
| Peer group median | 316 | (11.0) | 3.4 | 0.83 |
| MTU rank | 6/8 | 1/8 | 1/8 | 6/8 |
Enhanced dividend – c.6% yield on NAV
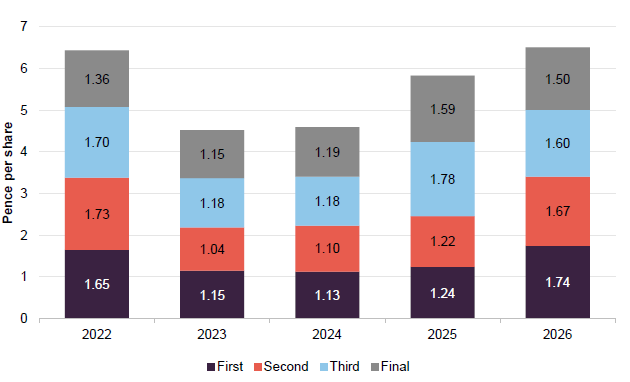
MTU pays dividends every quarter. From December 2024, each dividend is 1.5% of the previous quarter’s NAV, up from 1% before. For the year ending 31 March 2025, MTU earned a net revenue return of 3.3p per share (up from 3.2p) and paid dividends totalling 5.83p. For the year ending 31 March 2026, dividends total 6.51p.
At March 2026, the portfolio yield was 3.1%, with dividends expected to grow by 5.6%. Any shortfall in income is covered from distributable capital reserves. When the new dividend policy started in December 2024, the board estimated MTU had enough reserves to support the policy for 28 years, even with no growth in capital or income.
Figure 27: MTU ordinary dividends (pence per share)
Premium/(discount)
During the year to 30 April 2026, MTU’s shares traded at a discount between 11.7% and 3.9%, averaging 8.2%. On 5 May 2026, the discount was 6.0%.
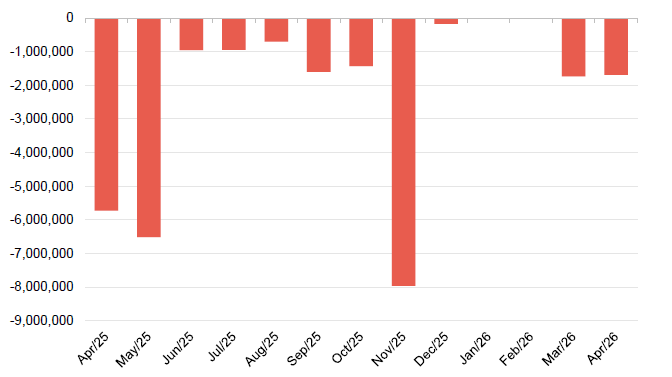
In 2026, MTU’s discount has settled in the mid-single digits, the narrowest among its peers, helped by its enhanced dividend strategy adopted in December 2024 and its ongoing share buyback programme. Since early 2025, MTU has bought back over 30% of its shares. After Saba Capital Management LP sold its entire stake last November, the pace of buybacks slowed. MTU has now called a meeting for 20 May 2026 to seek shareholder approval to renew its buyback authority. As of 1 May 2026, MTU had 167,379,790 shares in issue, with 54,348,650 held in treasury, leaving 113,031,140 shares with voting rights.
Figure 28: MTU premium/(discount) over five years ending 30 April 2026
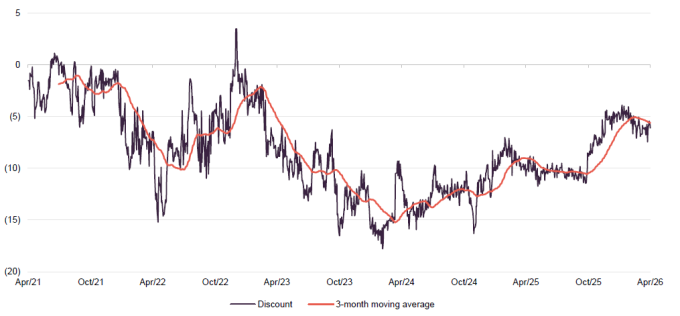
Figure 29: MTU share buybacks by month over the past year
SWOT analysis
Figure 30: SWOT analysis for MTU
| Strengths | Weaknesses |
|---|---|
| Well-regarded manager and considerable depth of resource | Long-term track record looks weak relative to peers and the trust’s benchmark |
| MAML continually strives to improve its investment process – reducing the concentration of the portfolio to reflect a more challenging environment, for example | |
| Quality bias should make MTU’s investments more resilient to economic shocks | |
| Opportunities | Threats |
| Low valuation of UK, quality, growth and small caps suggests upside when sentiment improves | Higher energy costs from Iran war are impacting on the UK economy and are likely to keep interest rates higher for longer |
| Switch in sentiment could drive self-reinforcing re-rating | Aggressive activists are stalking UK small-cap trusts |
| MAML expecting double-digit earnings growth in 2026 and 2027 |
Bull vs. bear case
Figure 31: Bull vs. bear case for MTU
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | Attractively valued, high-quality portfolio poised to re-rate when sentiment improves | This period of underperformance of small caps is one of the longest on record, but some years off that of the 1990s and macroeconomics remain unhelpful |
| Dividends | Attention-grabbing dividend yield differentiates MTU from peers | Dividend based on NAV and so would fall if NAV falls |
| Outlook | Stocks in MTU’s portfolio have good track record of delivering revenue and earnings growth | Worsening energy crisis could drive higher inflation, weighing on sentiment |
| Discount | MTU discount under control helped by buybacks and dividend yield | Further shrinkage of the trust could make it less attractive to wealth managers, reducing appetite for the shares |
Previous publications
Readers interested in further information about MTU may wish to read our previous notes listed below. You can read them by clicking on the links or by visiting the QuotedData website.
Figure 32: QuotedData’s previously published notes on MTU
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Montanaro UK Smaller Companies Investment Trust Plc.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.