
20 years on, potential undiminished
Vietnam Holding (VNH) has just turned 20. Both Vietnam and VNH have come a long way over the past 20 years. There have been both successes and setbacks along the way. Over the long term, VNH’s investment approach has delivered returns that are well ahead of local benchmarks. However, more recently, VNH’s quality growth and ESG-focused approach has been out of favour. Its companies continue to deliver impressive results, helped by Vietnam’s strong economy, but this is not being reflected in their ratings.
As we lay out in this note, Vietnam’s potential is undiminished. The government has ambitious but achievable targets that would deliver a remarkable economic transformation. VNH’s portfolio is primed to benefit, and in time that should be recognised by investors, particularly – we suspect – when foreign investors decide to return to the market. Vietnam’s upcoming inclusion in the FTSE Russell index series may help with that.
Capital growth from a concentrated portfolio of high growth Vietnamese companies
VNH aims to provide investors with long-term capital appreciation by investing in a portfolio of high-growth companies in Vietnam. These should come at an attractive valuation and demonstrate strong environmental, social, and corporate governance awareness.
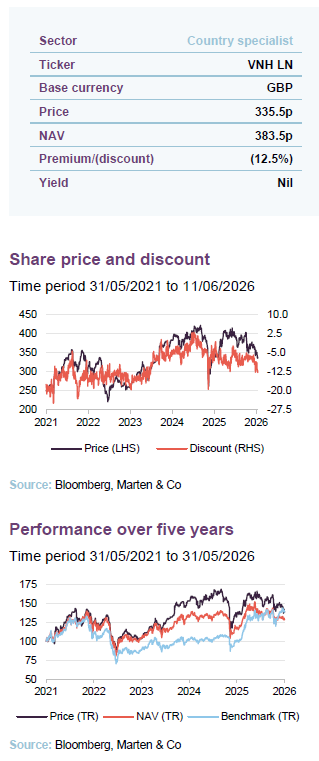
| 12 months ended | Share price TR (%) | NAV total return (%) | Vietnam All-Share TR (%) | MSCI Emerging Mkts TR (%) |
|---|---|---|---|---|
| 31/05/2022 | 26.4 | 22.7 | 10.9 | (8.5) |
| 31/05/2023 | (18.2) | (14.2) | (19.5) | (6.4) |
| 31/05/2024 | 48.2 | 25.8 | 14.2 | 9.7 |
| 31/05/2025 | (10.2) | (11.0) | (1.3) | 7.4 |
| 31/05/2026 | 1.2 | 9.1 | 37.7 | 55.0 |
Fund profile – listed Vietnamese equities with strong ESG focus
Further information on VNH can be found at the company’s website: www.vietnamholding.com
VNH is a closed-end fund, domiciled in Guernsey, that aims to provide investors with long-term capital appreciation by investing in a concentrated portfolio of high-growth companies in Vietnam that demonstrate strong environmental, social, and corporate governance (ESG) awareness.
VNH invests predominantly in publicly-traded companies in Vietnam, but it may also – subject to certain restrictions – invest in foreign companies if a majority of their assets and/or operations are based in Vietnam (up to a maximum of 25% of its net assets). It can invest in equity-like securities, such as convertible bonds, and may also hold private companies (up to a maximum of 20% of its net assets).
VNH does not have a formal benchmark. However, for the purposes of performance evaluation, the manager has traditionally included comparisons against the VN All-Share and the MSCI Emerging Markets Index in its literature.
Dynam Capital is searching for high-growth, compounding businesses that it can hold for the long-term.
In managing VNH’s portfolio, Dynam Capital (dynamcapital.com) is looking for high-growth, compounding businesses that it can hold for the long term. This can be summarised as growth at an attractive valuation. Dynam manages its portfolios using a mixture of top-down and bottom-up investment strategies. The top-down element of the investment process guides the manager towards the key sectors and sub-sectors on which to focus its attention, with the aim of achieving superior long-term returns. The bottom-up element of the process uses extensive fundamental research to select the best companies in those sectors and sub-sectors.
ESG incorporated into all investment and monitoring procedures
ESG research is fully integrated into its investment process.
An analysis of ESG criteria is central to Dynam’s approach, and has been part of its DNA since the beginning. Vu Quang Thinh, Dynam’s CIO, is very well-regarded in this area. He is a founding member and former chairman of the Vietnam Institute of Directors (VIOD). Established in April 2018, VIOD was the first private and independent organisation in Vietnam, aimed at promoting the highest standards and best practices in corporate governance among domestic firms.
More information on VNH’s investment approach is contained within our April 2025 note.
A 20 year growth story…
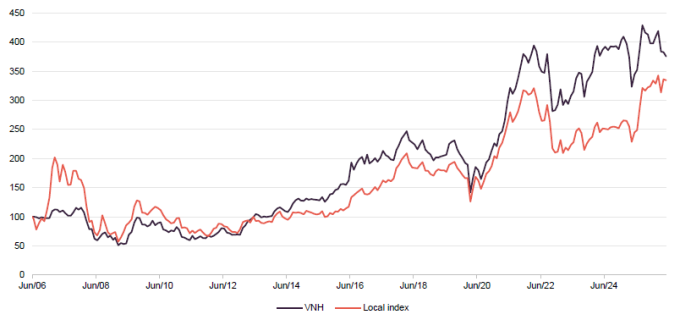
VNH launched in April 2006, was admitted to trading on AIM in June 2006, and moved to the main market in March 2019. An investment of £1000 at launch would be worth £3,140 by the end of May 2026.
Figure 1: Total return in sterling of VNH (NAV terms) and local indices since VNH’s launch
The market cap of Vietnam’s stock exchange today is over 19x larger than it was in June 2006
In 2006, economic growth was already around 7.5% per annum. The manager was looking forward to Vietnam’s accession to the World Trade Organization. At the outset, its primary focus was on former State-Owned Enterprises (SOEs). The government had just announced a list of 178 SOEs that it planned to list on the Vietnam Stock Exchange.
At the time, Ms Min Hwa Hu Kupfer, VNH’s first chair, said: “This is a historically important period for Vietnam, as the country prepares its accession to the WTO. The announced wave of privatizations is expected to provide attractive investment opportunities for the global investment community. VNH is excited about being able to contribute to Vietnam’s economic growth through its strategic investments.”
The development of the market was rapid. In June 2006, Vietnam’s market capitalisation was just $2.8bn but by June 2007 it was already $16.9bn. However, at the end of April 2026 it had swollen to about $347.5bn. FTSE Russell recently confirmed that Vietnam would low suit.
…with a long way to run
Vietnam is a far richer country than it was in 2006 but still has big ambitions
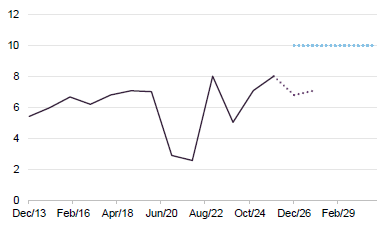
Over the past 20 years, Vietnam has become a far richer country, helped by considerable growth in exports, particularly of manufactured goods. However, on a GDP per capita basis, it still lags its northern neighbour China by a significant margin. The Vietnamese government is determined to narrow that gap, and its policy agenda supports that ambition. It is targeting 10% GDP growth per annum between 2026 and 2030 with the aim of hitting GDP per capita of $8,500 by 2030. The World Bank is more sanguine in its targets of 6.8% for 2026 and 7.1% in 2027. It revised down its forecasts in May 2026, aiming to factor in the possible impact of the Iran war on the economy.
Figure 2: GDP per capita in US dollars
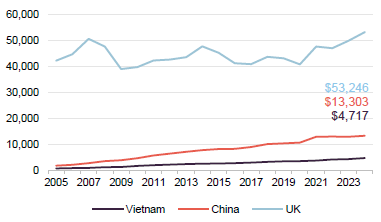
Figure 3: Real GDP growth rate (%)
It may help that it has demographics on its side, as China’s population is ageing fast, whereas the proportion of under-15s in the Vietnamese population has remained fairly stable. Standards of education are high, too, with plans to ensure that students are bilingual in Vietnamese and English. Vietnam is experiencing ongoing urbanisation, but the proportion of the population in rural areas is still fairly high (62% rural:38% urban in 2024 – the manager says that split is closer to 60:40 now), so there is also more to go for on that front.
Figure 4: Population
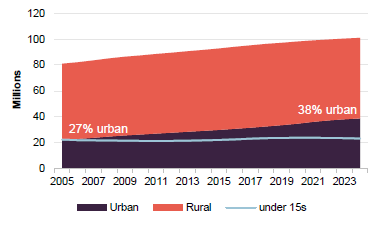
Figure 5: Index of value of exports (2015 = 100)
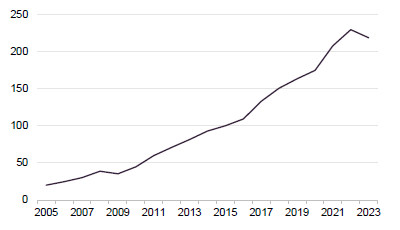
Economic growth was strong in 2025, seemingly shrugging off the effects of last year’s surprise US tariff announcements (discussed at length in previous notes); Q1 GDP growth was 7.8%. US data shows that US goods exports to Vietnam in 2025 were $15.7bn (+20.0%), but imports were $193.8bn (+42.0%), leaving it with a 44.3% increase in its trade deficit.
The composition of Vietnam’s exports has also evolved, from commodities to low-value-added goods, and then high-value-added goods. In part, this reflects a shift of manufacturing from China as firms sought to bypass US controls on Chinese imports.
Figure 6: US dollar / Vietnamese Dong exchange rate
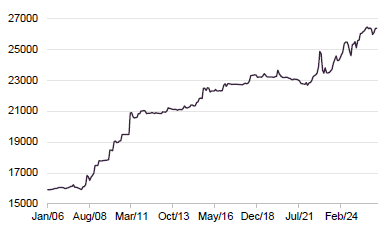
Figure 7: Inflation rate (%)
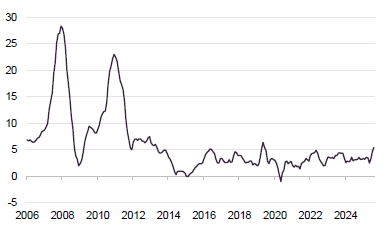
The Vietnamese Dong has been weakening relative to the dollar, boosting the attraction of its exports. Inflation is much better controlled than it was in VNH’s early days. However, it is currently running ahead of a State Bank of Vietnam target of 4.5%.
Significant infrastructure investment underway
Vietnam’s government debt is about 33% of GDP (according to Moody’s) and the budget deficit for 2026 is forecast at about 4.2% of GDP. The government is pushing ahead with its $129bn infrastructure investment plan, which we discussed in our last note, alongside government resolutions 68 and 79, which are designed to support the growth of private businesses.
New government pushing to accelerate growth of digital economy
In April 2026 a new Prime Minister, Le Minh Hung, was elected by the National Assembly. VNH’s manager says that he and Tô Lâm, the general secretary of the party and now also the President, are business-minded and the manager sees this as good news for the country. In May Le Minh Hung published a decree which identified 70 technologies and over 100 high-tech products that the government will prioritise for investment and development. This followed the announcement of a digital technology plan, targeting $300bn of revenue from this area by 2030.
One of the enablers for this will be the work that Vietnam has already undertaken in connection with “Project 6”, a programme of digitising government administration and the economy that began in 2022 and is supposed to run until 2030. By the end of this year, everyone will have a biometric digital ID (based on the VNeID scheme that was boosted to tackle COVID). That is facilitating rapid growth in areas such as e-payments.
Bold plans and long-term vision, such as this and the infrastructure programme, are a core characteristic of Vietnam’s economy and have played a big part in its evolution over the past 20 years. There have been bumps along the way, too, such as real estate booms and busts, and the $44bn Saigon Commercial Bank fraud, but the government has clamped down hard on corruption, initially handing out death sentences in the latter case.
Figure 8: Number of mobiles and fixed broadband connections per 100 people
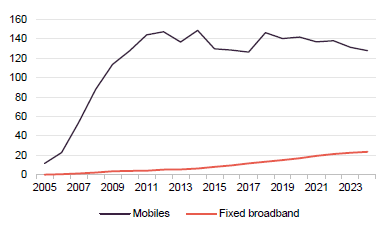
Figure 9: International tourist arrivals
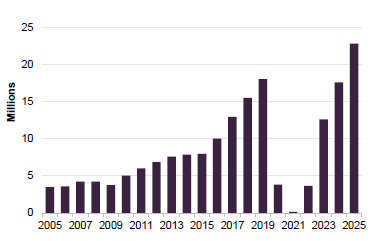
A surge in tourist arrivals over 2025 was good news. This sector is an increasingly important contributor to GDP.
Figure 10: Vietnam energy generation by type
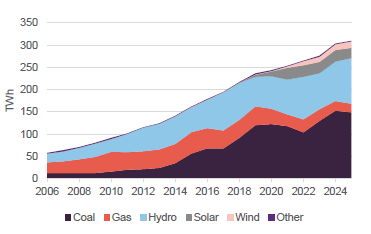
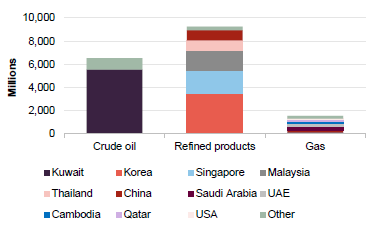
Figure 11: Oil & gas imports by value (in millions of dollars)
Iran war could have an impact
One risk on the horizon is the knock-on effect of the Iran war on the cost of energy. Fortunately, the government has been pushing the development of renewable energy, and this will cushion the impact a little. The data in Figure 11 is slightly out of date, but assuming it reflects a fair picture, there is an obvious problem with relying on Kuwait for crude oil and this will have to be sourced elsewhere. What we do not know yet is what the effect will be on the Asian refineries that supply products to the country. This all suggests heightened inflationary pressures, but Vietnam will not be alone in this, which could have a secondary effect on global demand for Vietnamese exports. Higher air fares might have an effect on tourism.
Valuations of Vietnamese stocks are depressed
What we can say is that valuations of Vietnamese stocks are already depressed relative to international peers. Foreign investors have been withdrawing capital from the market (now owning just 14.5% of it) and retail investors (now more than 12m of them) are dominating trading. Unfortunately, that has contributed to distortions such as the elevated value of Vingroup that we discussed in the last note. VNH continues to avoid the stock on governance and valuation grounds.
Figure 12: Valuation data
| Historic P/E (x) | Current P/E (x) | Forecast P/E (x) | |
|---|---|---|---|
| Vietnam Ho Chi Minh VN All-Share (VNAS) | 12.3 | 10.8 | 8.9 |
| Vietnam Ho Chi Minh Stock Index (VNI) | 15.0 | 12.5 | 10.7 |
| MSCI Vietnam | 19.3 | 15.5 | 13.2 |
| MSCI Emerging Markets | 18.8 | 13.3 | 11.0 |
| MSCI ACWI | 22.7 | 19.3 | 16.9 |
One thing that is evident in Figure 12 is the wide range of valuations for different Vietnamese indices. In our last note, we discussed the distorting effect of the extraordinary price moves within the Vingroup conglomerate on the indices. The different ratings are heavily influenced by variances in the weightings of these companies within the indices. VNH has an underweight exposure to companies within the conglomerate, and this has held back its returns relative to comparative indices in recent months.
Asset allocation
As at 30 April 2026, VNH’s portfolio had exposure to 25 securities (unchanged from 31 December 2025, the data that we used in our last note). On average, these were valued on just 10.1x prospective earnings despite offering the potential for 18.6% earnings growth. The top 10 holdings accounted for 63.2% (63.7%) of VNH’s portfolio as at 30 April 2026.
Figure 13: VNH portfolio sectoral allocation as at 30 April 2026
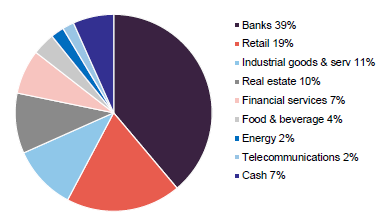
Figure 14: VNH change in portfolio sectoral allocation since 31 December 2025
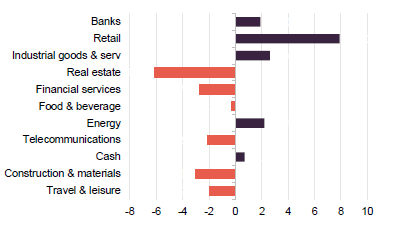
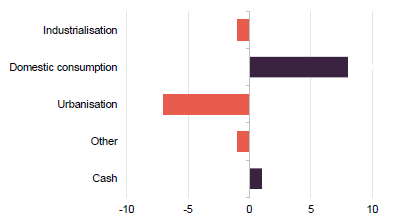
As at the end of April 2026, since we last published, using data as at the end of December 2025, there has been a shift in the portfolio from real estate to retail, and from urbanisation to domestic consumption. In part, that reflects profit taking by the manager following the run-up in Vinhomes’s share price and a strong outlook for the domestic economy – the manager observes that retail sales were up 12.1% YoY in April and 11.1% YoY for the first four months of 2026.
Figure 15: VNH portfolio by theme as at 30 April 2026
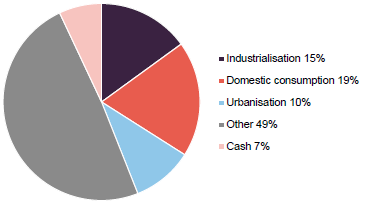
Figure 16: VNH change to split of portfolio by theme since 31 December 2025
Top 10 holdings
Since we last published using data at the end of December 2025, SSI Securities and FPT have fallen out of the top 10, to be replaced by longstanding holding Phu Nhuan Jewelry and the conglomerate Masan Group.
Figure 17: Top 10 holdings as at 30 April 2026
| Stock | Sector | Portfolio weight 30 Apr 2026 (%) | Portfolio weight 31 Dec 2025 (%) | Change(%) |
|---|---|---|---|---|
| Mobile World | Retail | 10.0 | 10.0 | – |
| Hoa Phat Group | Industrials | 9.5 | 7.4 | 2.1 |
| MB Bank | Banks | 9.2 | 8.5 | 0.7 |
| VPBank | Banks | 6.8 | 6.4 | 0.4 |
| Techcombank | Banks | 6.7 | 6.4 | 0.3 |
| VietinBank | Banks | 5.5 | 5.4 | 0.1 |
| Vinhomes | Real estate | 4.7 | 6.1 | (1.4) |
| Asia Commercial Bank | Banks | 3.7 | 5.4 | (1.7) |
| Masan | Conglomerate | 3.7 | n/a | n/a |
| Phu Nhuan Jewelry | Retail | 3.4 | n/a | n/a |
| Total of top 10 | 63.2 | 63.7 |
Masan Group
Figure 18: Masan Group share price (VND)
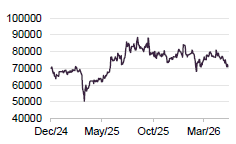
Masan Group (masangroup.com) is a conglomerate that was incorporated in 2004 as Ma San Shipping and now encompasses a number of companies in retail, branded FMCG, food, and beverages (including chilled meat and tea & coffee), financial services, and high-tech materials.
- Masan owns a stake in another VNH top 10 position, Techcombank. Its share of Techcombank’s profits was up 11.8% YoY in Q1 2026.
- WinCommerce is a nationwide chain of over 4,800 supermarkets and minimarts (225 new store openings in Q1 2026).
- Masan Consumer Holdings is one of Vietnam’s largest local diversified FMCG companies. It is targeting 11%-15% revenue growth over 2026.
- Masan MEATDeli is a chilled and processed meat business. Revenue was up 19.8% YoY over Q1 2026.
- Phuc Long Heritage has 205 tea and coffee stores and plans to open 40-50 more this year.
- Masan High-Tech Materials is a significant producer of fluorspar and bismuth, and it also owns tttery business Nyobolt in 2022 was a precursor to developing a vertically integrated tungsten business.
Performance
Whilst VNH reports its NAV in US dollars, we have translated its returns into sterling for the purposes of producing the numbers in Figure 19.
Figure 19: Cumulative total return performance over periods ending 31 May 2026
| 3 months(%) | 6 months (%) | 1 year (%) | 3 years(%) | 5 years(%) | |
|---|---|---|---|---|---|
| VNH share price | (13.6) | (11.0) | 1.2 | 34.6 | 39.2 |
| VNH NAV | (10.3) | (5.5) | 9.1 | 22.1 | 28.5 |
| VN All-Share | (1.8) | 3.5 | 37.7 | 55.3 | 38.6 |
| MSCI Emerging Markets | 9.4 | 27.3 | 55.0 | 82.7 | 56.5 |
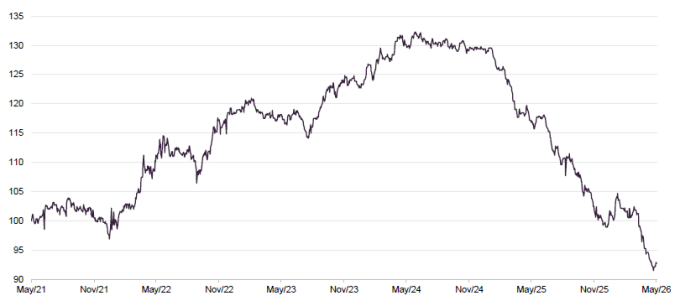
A strong run of relative outperformance faltered early in 2025 and VNH has given up all of this since. Whilst net FDI remains strong, foreign investors have been pulling money out of the market, in part a response to the tariff announcements in April 2025, and more recently on concerns about the impact of the Iran war. Retail investors are less cognisant of governance concerns and more prone to momentum investing. This is not an environment that suits VNH’s investment approach. On average, its companies are still delivering the sales and profits uplifts that the manager is anticipating but this is not reflected in their valuations.
Figure 20: VNH’s NAV performance relative to the VN All-Share over five years to 31 May 2026
Premium/(discount)
Over the 12 months to the end of May 2026, VNH traded in a discount range of 0.7% to 12.7% and averaged 7.4%. As at 11 June 2026, VNH was trading on a discount of 12.5%.
Figure 21: VNH premium/(discount) over five years
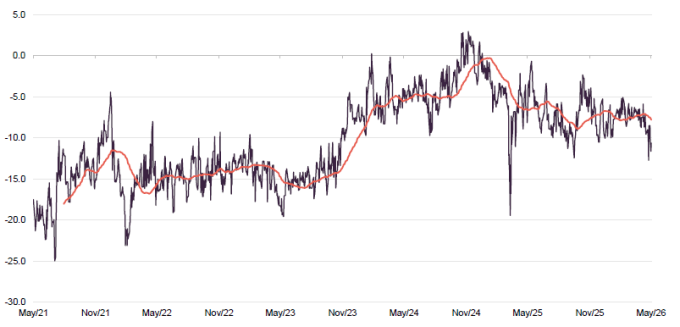
VNH’s board is keen to keep the discount tight, with the ultimate aim of re-expanding the company by issuing shares at a premium when investors re-embrace the Vietnam story. It was able to issue a small amount of stock in January 2025.
To that end, in addition to regular share buybacks VNH operates an annual redemption facility. This was announced towards the end of 2023 and first implemented in September 2024, when about 12% of the issued share capital was redeemed. We believe that the facility has made a significant contribution towards keeping the discount tight. To be eligible to participate in the facility, shareholders have to have held the stock that they want to redeem for at least six months, which helps to deter arbitrageurs from gaming it.
In 2025’s redemption opportunity, investors holding c.4.2m shares (about 17.9% of VNH’s shares in issue) opted to redeem these shares.
SWOT and bull versus bear analysis
Figure 22: SWOT analysis for VNH
| Strengths | Weaknesses |
|---|---|
| Great long-term track record of NAV and share price growth | Lack of exposure to Vingroup and other momentum-driven retail favourites has damaged track record in the short term |
| Tough on discount control, including provision of annual redemption facility | Annual redemption opportunity creates risk that the company may no longer be viable, especially if it coincides with a period of market instability |
| Small enough to be nimble in what can still be an illiquid market | Small size pushes up expense ratio and reduces liquidity in VNH’s shares |
| Opportunities | Threats |
| Vietnamese market and stocks in VNH’s portfolio are cheap, especially considering their growth potential | Economic disruption from the Iran war could worsen and weigh on Vietnam’s exports with knock-on effects on the domestic economy |
| When foreign investor confidence returns, VNH is positioned to re-expand | |
| Vingroup’s bubble might burst to the benefit of VNH’s relative performance |
Figure 23: Bull versus bear case for VNH
| Aspect | Bull case | Bear case |
|---|---|---|
| Performance | Good long-term | One-year relative performance has been poor |
| Dividends | N/A | N/A |
| Outlook | Vietnam’s government has its foot on the economy’s accelerator, which should feed through into positive share price performance | Macroeconomic events could hold back Vietnam’s growth ambitions |
| Discount | Strong discount control has been achieved through shrinking the trust, but renewed appetite for the shares could see it trading at a premium and issuing stock | Continued shrinkage makes VNH’s shares less liquid, which could exacerbate discount problem |
Previous publications
Readers interested in further information about VNH, such as investment process, fees, capital structure, life, and the board, may wish to read our note – Cheap stocks, bold reforms, big ambitions – published on 29 April 2025. You can read the notes by clicking on them in Figure 24 or by visiting our website.
Figure 24: QuotedData’s previously published notes on VNH
IMPORTANT INFORMATION
This marketing communication has been prepared for Vietnam Holding Limited by Marten & Co, which is authorised and regulated by the Financial Conduct Authority (FCA). It constitutes non-independent research as defined under the UK MiFID II regime and the onshored Commission Delegated Regulation (EU) 2017/565.
This communication is intended for use by investment professionals as defined in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005. Marten & Co is not authorised to provide advice to retail clients. Accordingly, if you are not a professional investor, or are otherwise restricted from receiving this information, you should disregard it. The note does not have regard to the specific investment objectives, financial situation and needs of any specific person who may receive it.
The note has not been prepared in accordance with legal requirements designed to promote the independence of investment research and as such is considered to be a marketing communication. The analysts who prepared this note are not constrained from dealing ahead of it, but in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.