
Back this horse?
Vietnam continues to push forward with its reforms aimed at addressing obstacles to its goal of double-digit annual GDP growth between now and 2030. A 28% increase in one of Vietnam Holding (VNH)’s comparator indices over 2025 suggests that some of this potential growth may be reflected in valuations, but over half of that increase came from a single company that VNH has chosen not to include in its portfolio. Despite these growth prospects, much of the Vietnamese market appears to remain at relatively low valuations (VNH’s portfolio was trading on a forecast P/E of 9.5x at end December 2025), which may in part be because foreign investors have not yet returned in significant numbers. The process towards an upgrade to emerging market status is progressing, and FTSE Russell looks set to upgrade Vietnam with effect from September this year.
17 February 2026 marks the beginning of the year of the Fire Horse in Vietnam. This period is considered auspicious by some individuals, while others may focus on Vietnam’s economic fundamentals.
Capital growth from a concentrated portfolio of high growth Vietnamese companies
VNH aims to provide investors with long-term capital appreciation by investing in a portfolio of high-growth companies in Vietnam. These should come at an attractive valuation and demonstrate strong environmental, social, and corporate governance awareness.
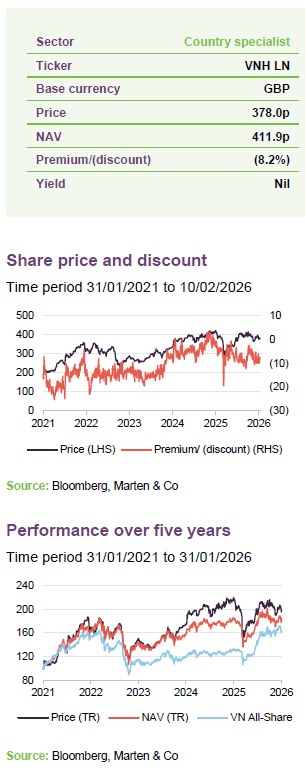
| Year ended | Share price total return (%) | NAV total return (%) | Vietnam All-Share TR (%) | MSCI Emerging Mkts TR (%) |
|---|---|---|---|---|
| 31/01/2022 | 67.7 | 64.0 | 54.4 | (5.1) |
| 31/01/2023 | (9.9) | (12.2) | (25.1) | (3.9) |
| 31/01/2024 | 15.5 | 9.3 | 2.4 | (5.6) |
| 31/01/2025 | 23.0 | 17.4 | 11.8 | 17.7 |
| 31/01/2026 | (7.3) | (0.0) | 23.8 | 30.4 |
Source: Bloomberg, Marten & Co
Fund profile – listed Vietnamese equities with strong ESG focus
Further information on VNH can be found at the company’s website: www.vietnamholding.com
VNH is a closed-end fund, domiciled in Guernsey, that aims to provide investors with long-term capital appreciation by investing in a concentrated portfolio of companies in Vietnam that, according to the fund, demonstrate high growth and strong environmental, social, and corporate governance (ESG) awareness.
VNH invests predominantly in publicly-traded companies in Vietnam, but it may also – subject to certain restrictions – invest in foreign companies if a majority of their assets and/or operations are based in Vietnam (up to a maximum of 25% of its net assets). It can invest in equity-like securities, such as convertible bonds, and may also hold private companies (up to a maximum of 20% of its net assets).
VNH does not have a formal benchmark. However, for the purposes of performance evaluation, the manager has traditionally included comparisons against the VN All-Share and the MSCI Emerging Markets Index in its literature.
Macroeconomic outlook
Vietnam delivered 8% growth in GDP in 2025
Vietnam reported 8% growth in GDP in 2025, up from 7.1% in 2024, and the rate of growth appeared to accelerate through the year, which may have been influenced by government reforms and economic stimulus. A ceremony on 19 December 2025 marked the launch of 148 new infrastructure projects and the inauguration of a further 86, collectively worth a total of $129bn. These include Long Thanh International Airport (which is scheduled to open later this year and is expected to have the capacity to handle 100m passengers each year; for comparison, Heathrow managed 84.5m in 2025), the 400km Lao Cai–Hanoi–Hai Phong railway, three new metro lines, and the creation of a new Olympic park in Hanoi.
The tourism sector recorded a 20% growth in visitor numbers over 2025 to a record 21.2 million international arrivals. The majority of these (79%) were from other countries in Asia, notably China and South Korea.
Tariffs – not as bad as some feared
Vietnam’s trade surplus with the US looks to have grown over 2025 despite US tariffs
Our last note on VNH was published on 29 April 2025, following “Liberation Day”, when Trump imposed tariffs on Vietnamese imports (an initial rate of 46%) and the subsequent “pause” to these, as the associated market backlash appeared to trigger some backtracking by the US administration and the rate was temporarily reduced to 10%. The Vietnamese government reacted and was one of two countries to secure a trade deal with the US ahead of the original 9 July deadline. The terms of this agreement mean that Vietnamese imports to the US attract a 20% tariff while US imports to Vietnam are tariff-free. Vietnam’s trade surplus with the US appears to have grown over the course of 2025.
VNH’s manager observes that within those figures, electronics and computers made a significant contribution, which the manager believes reflects Vietnam’s shift towards higher-added-value manufacturing.
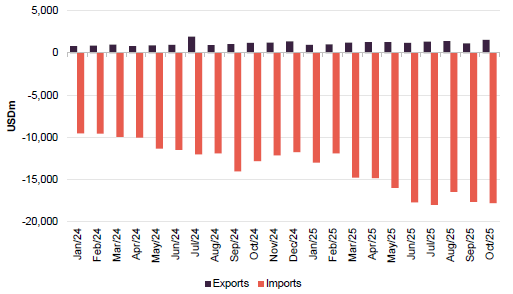
Figure 1 uses data from The US Census Bureau. According to this data, by the end of October 2025, the US had imported goods worth $158bn from Vietnam in 2025 and the trade deficit was $146bn.
Figure 1: US exports/imports to/from Vietnam
Source: The US Census Bureau
Vietnamese figures for 2025 were for total exports of $475bn over 2025, up by 17% year-on-year and within that, total exports to the US of $153bn. While there is some discrepancy in the figures, some commentators suggest that US tariffs may be less of a problem for Vietnam than previously anticipated. Vietnam also has trade agreements in place with its other leading trading partners, including China.
Inflation, interest rates, and currency
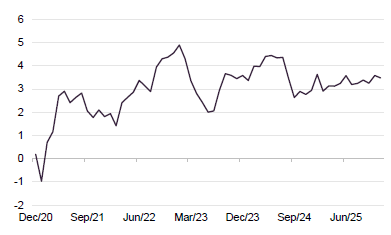
Figure 2: Vietnam CPI
Source: Bloomberg
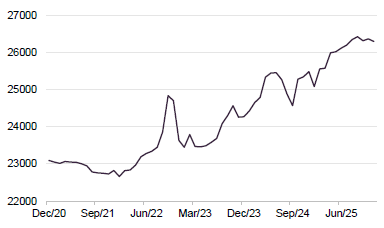
Figure 3: Vietnamese Dong US dollar exchange rate
Source: Bloomberg
As Figure 2 shows, inflation has been less volatile recently and at levels the manager considers comfortable. The official interest rate has remained flat at 4.5% since June 2023, but lending rates increased by 100bp towards the end of 2025, which the manager believes is manageable. Credit growth was 19% year-on-year in 2025. The government is running a budget surplus, and foreign direct investment was reported at $38.4bn (with FDI disbursed at $27.6bn). Despite these factors, the Vietnamese Dong has weakened slightly against the dollar and by a larger margin against sterling (see page 10).
Politics – driving an ambitious growth agenda
Target of $8,500 per capita GDP by 2030, up by about 80% on 2025
The 14th Party Congress has concluded without any major surprises and has confirmed Tô Lâm as its General Secretary for a further five years. To further its goal of becoming a high-income nation by 2045, the Vietnamese government is targeting 10% GDP growth in 2026. The government’s stated ambition is to maintain that rate of growth through to 2030 and achieve per capita GDP of $8,500 by that date (it was about $4,700 in 2024 – for comparison, China’s GDP per capita in 2025 was estimated at about $13,800). The manager expects that as household wealth grows and Vietnam’s middle class expands, this should contribute to increased retail sales and a growing services sector. The manager highlights the political support for the economy, citing two “Resolutions” in particular.
Resolution 68
In May 2025, Resolution 68 officially recognised the private sector as a driving force behind Vietnam’s economic growth. It aims to promote entrepreneurship with a goal to double the number of private enterprises in the country to 2m by 2030 and to reach 3m by 2045.
There is a target of supporting the creation of at least 20 large private Vietnamese companies with brands that are capable of integrating into global value chains and contributing to industrial growth. Some commentators have suggested that this is an attempt to replicate the approach taken by South Korea’s chaebols (such as Samsung, LG, and Hyundai). This may have been a factor in the increase in the share price of Vin Group (see page 6).
There is also an ambition to achieve 10%–12% annual economic growth within the private sector.
To meet these targets, the plan is to reduce bureaucracy, facilitate access to finance, reform taxation, and end the automatic preference of State-Owned Enterprises (SOEs) and foreign investors over domestic private enterprises. Amongst other things, this could result in more IPOs and privatisations.
Resolution 79
Aiming to create national champions to become leading Asian companies
In January 2026, Resolution 79 reinforced and expanded on 68. It sets out a goal of having at least 50 SOEs within Asia’s 500 largest enterprises by 2030, with an expectation that this may support the growth of the private businesses that support these SOEs. It also aims to have three state-owned commercial banks ranked among the top 100 banks in Asia by that date.
However, it wants the SOEs to achieve these targets without receiving preferential state support and for these SOEs to adopt OECD levels of governance.
Markets
EM status
FTSE Russell upgraded Vietnam to emerging market status last year. The decision is subject to an interim review in March this year and, assuming all goes well, the change should take effect in September. The effect may be limited, as most investors and tracker funds tend to favour the MSCI series of indices. MSCI is expected to review Vietnam’s status. Vietnam currently makes up over 30% of the MSCI frontier markets index and has daily turnover averaging in excess of $1bn, which is higher than many emerging markets. There are reports that Vanguard is exploring launching funds investing in the country.
Valuations and the Vingroup problem
Figure 4: Valuation data
| Historic P/E (x) | Current P/E (x) | Forecast P/E (x) | |
|---|---|---|---|
| Vietnam Ho Chi Minh VN All-Share (VNAS) | 13.2 | 11.1 | 9.2 |
| Vietnam Ho Chi Minh Stock Index (VNI) | 14.8 | 13.1 | 10.9 |
| MSCI Vietnam | 16.7 | 15.3 | 12.8 |
| MSCI Emerging Markets | 17.8 | 17.0 | 13.3 |
| MSCI ACWI | 22.5 | 22.1 | 19.3 |
Source: Bloomberg as at 9 February 2026
In its factsheets, VNH compares its returns to the Vietnam Ho Chi Minh VN AllShare (VNAS), while its peers use the Vietnam Ho Chi Minh Stock Index (VNI), which has a larger focus on large-cap stocks. The MSCI Vietnam Index appears to be more concentrated.
Currently, a large constituent of all three indices is Vingroup, which is not held by VNH. According to VNH, this decision is based on the company’s fundamentals, low liquidity, and governance. Vingroup is the holding company for a group of businesses that includes resorts, robotics and cybersecurity divisions, the NASDAQ-listed EV company VinFast Auto, and Vinhomes, which is in VNH’s top 10 (see page 8).
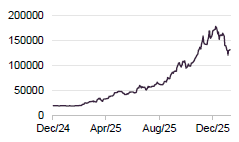
Figure 5: Vingroup (VND)
Source: Bloomberg
As Figure 5 shows, Vingroup’s share price was strong over 2025. The manager states that a relatively small free float and domestic investor interest in the stock (partly due to the potential for it to be one of the leading groups of companies identified in Resolution 68) may have contributed to its valuation reaching high levels. At the time of publication, it was trading on a P/E of 79x. At the end of December 2025, Vingroup and its associated companies accounted for about a quarter of the market cap of the Ho Chi Minh Stock Exchange (HOSE) and Vingroup alone accounted for 25.3% of the MSCI Vietnam Index, with Vinhomes accounting for a further 8.3%. VNAS is a free float-adjusted index. However, the manager believes that due to the out-sized market cap of Vingroup, none of these indices would constitute a valid and replicable performance benchmark.
It appears that Vingroup may have influenced the performance of VNH’s benchmark comparator
The effect appears to be that the Vietnamese market appears more expensive than it might otherwise, and the various indices performed better over 2025 than they may have otherwise (Vingroup accounted for about half the return on the VNI, for example).
A growing market in Vietnamese corporate bonds
The equity market has seen a return to IPOs, with three totalling $1.5bn in 2025, following a seven-year period without IPOs, and additional IPOs are planned for this year. VNH’s manager notes that one of the government’s stated goals is to develop Vietnam’s corporate bond sector as a means of increasing the capital available to growing companies. According to domestic ratings agency FiinRatings, issuance of VND644.3trn of corporate bonds by 122 issuers over 2025 brought the total size of the market to VND1,413trn across 321 issuers. At approximately 11.4% of GDP, this figure is below the 20% target for 2025 set by the government. It is also smaller relative to other markets and to the Vietnamese equity market.
FiinRatings believes that new financial leverage limits of 5x debt-to-equity may help improve the overall credit quality of the market, while a Ministry of Finance decision to permit new investment funds could help channel more of the domestic savings market into this area.
Asset allocation
As at 31 December 2025, VNH’s portfolio had exposure to 25 securities (up from 23 at 31 March 2025, the data that was used in the previous note). On average, these were valued at 9.5x prospective earnings and the companies in the portfolio are forecast to deliver 18.0% earnings growth. The top 10 holdings accounted for 63.7% (65.6%) of VNH’s portfolio as at 31 December 2025.
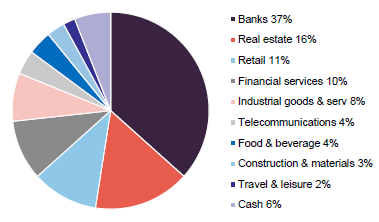
Figure 6: VNH portfolio sectoral allocation as at 31 December 2025
Source: Dynam Capital, Marten & Co
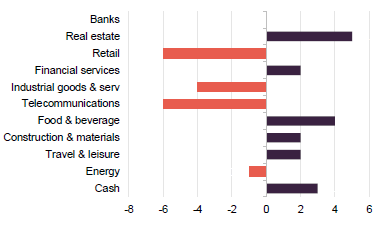
Figure 7: VNH change in portfolio sectoral allocation since 31 March 2025
Source: Dynam Capital, Marten & Co
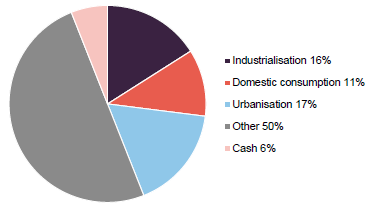
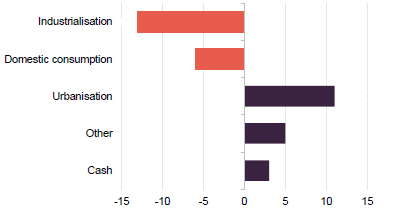
The shift towards greater exposure in real estate (Figure 7) and the urbanisation theme (Figure 9) appears to be associated with changes in the residential property market and an increase in Vinhome’s share price (see below).
Figure 8: VNH portfolio by theme as at 31 December 2025
Source: Dynam Capital, Marten & Co
Figure 9: VNH change to split of portfolio by theme since 31 March 2025
Source: Dynam Capital, Marten & Co
Top 10 holdings
Since the last publication using data at the end of March 2025, Sacombank, Sai Gon VRG Investment, FPT Digital Retail, and Phu Nhuan Jewelry are no longer included in the list of the 10 largest holdings. They have been replaced by VP Bank, Vinhomes, VietinBank, and SSI Securities.
Figure 10: Top 10 holdings as at 31 December 2025
| Stock | Sector | Portfolio weight 31 Dec 2025 (%) | Portfolio weight 31 Mar 2025 (%) | Change(%) |
|---|---|---|---|---|
| Mobile World | Retail | 10.0 | 8.2 | 1.8 |
| MB Bank | Banks | 8.5 | 7.3 | 1.2 |
| Hoa Phat Group | Industrials | 7.4 | 6.1 | 1.3 |
| VPBank | Banks | 6.4 | 6.6 | (0.2) |
| Techcombank | Banks | 6.4 | 8.7 | (2.3) |
| Vinhomes | Real estate | 6.1 | 3.9 | 2.2 |
| Asia Commercial Bank | Banks | 5.4 | 7.3 | (1.9) |
| VietinBank | Banks | 5.4 | 5.7 | (0.3) |
| SSI Securities | Financials | 4.5 | 4.4 | 0.1 |
| FPT Group | Telecommunications | 3.6 | 9.8 | (6.2) |
| Total of top 10 | 63.7 | 65.6 |
Source: Vietnam Holding Limited, Marten & Co
Mobile World
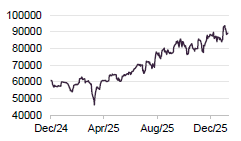
Figure 11: Mobile World share price (VND)
Source: Bloomberg
Mobile World Investment Corporation (mwg.vn) operates as a multi-category retailer in Vietnam, with over 6,000 stores nationwide, an ecommerce business, and a joint venture that is developing a retail business in Indonesia. The largest portion of its revenue (38%) is from phones and accessories, with additional products including food, fast moving consumer goods, consumer electronics, pharmaceuticals, and mother & baby products. Revenue increased by 16% over 2025 to over VND156trn, exceeding the company’s stated target by 4%. Revenue growth was higher than Vietnam’s retail sales growth of 9.2%.
For 2026, Mobile World is targeting 18% revenue growth and 30% profit growth, which the company believes is supported by government policy and opportunities to use AI to reduce costs, improve labour productivity, and enhance operational efficiency. The company also has in-house warehousing, logistics, delivery, installation, and after-sales services.
VNH’s manager has expressed a positive outlook regarding the prospects for growth in consumer spending and Mobile World, in particular.
VPBank
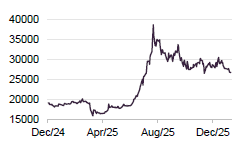
Figure 12: VPBank share price (VND)
Source: Bloomberg
The manager says that, in general, Vietnam’s banks are in good shape, which may be supported by monetary policy, credit growth, and low levels of bad debts. The manager is also reassured by what it considers to be healthy levels of provisions. According to the manager, the recovery in the real estate market may also benefit the sector. The manager believes there could be further upside in banks’ share prices over 2026.
Vietnam Prosperity Joint-Stock Commercial Bank, or VPBank (vpbank.com.vn/en), has stated that it aims to be one of the 100-largest banks in Asia. As a private bank, it would not count towards the Resolution 79 goal.
Q4 2025 figures show 35% year-on-year growth in its loan book, a 52% increase in profit before tax, and a 52% increase in its EPS, which may have been influenced by credit growth and lower provisioning. Analysts state that its asset quality appears to be improving.
Vinhomes
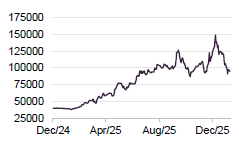
Figure 13: Vinhomes share price (VND)
Source: Bloomberg
Vinhomes (vinhomes.vn/en) is one of Vietnam’s largest developers. 2025 saw a recovery in sales following a difficult period for the residential property sector. Pre-sales of its new-build homes are at record levels, prices are rising, and margins are improving. The company was targeting 27% revenue growth and 20% profit growth for 2025.
Vinhomes reports an extensive residential landbank of over 17,000ha, which it notes is over 10 times the size of its nearest competitor, a 1,970ha industrial landbank, and 379,000sqm of offices (of which 75% is occupied).
Its development pipeline includes several large projects such as Olympics Village in Hanoi, where Vietnam is building infrastructure that may support a bid for the Asian Games and potentially a future bid for the Olympics).
VietinBank
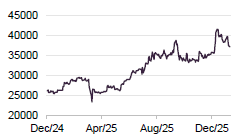
Figure 14: VietinBank share price (VND)
Source: Bloomberg
The manager comments that The Vietnam Joint Stock Commercial Bank for Industry and Trade or VietinBank (vietinbank.vn/en) – a state-owned bank – has a reported a return on equity (ROE) of approximately 21.6% for 2025, a cost-income ratio of about 27%, and non-performing loans (NPL) of about 1%. According to the manager, the bank delivered over 25% annual profit growth over the past couple of years, supported by lower bad debts. The manager also notes that the valuation is approximately 1.6x price/book and about 8.3x P/E.
As a state-owned enterprise (SOE), it has a role in financing government infrastructure projects. The bank is headquartered in Hanoi and operates across the country.
SSI Securities
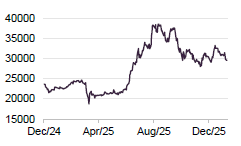
Figure 15: SSI Securities share price (VND)
Source: Bloomberg
SSI Securities (ssi.com.vn/en) is one of the three-largest brokers in Vietnam, with a 12.5% market share at the end of 2025. Higher brokerage volumes, growth in its margin lending and fund management businesses, and the launch of new products appear to have contributed to a 54% increase in revenue for 2025 versus 2024, which was accompanied by a 46% increase in profits. Over 800,000 new trading accounts were opened in Q4 2025.
SSI also has a presence in bond underwriting, which could benefit the company if the corporate bond market expands as the manager expects.
Performance
Whilst VNH reports its NAV in US dollars, its returns have been translated into sterling for the purposes of producing the numbers in Figure 16. As shown in Figure 3, the Vietnamese Dong weakened by about 3% relative to the US dollar over 2025. However, relative to sterling, the Dong’s depreciation was greater – about 12% over the 12 months to the end of January 2026.
Figure 16: Cumulative total return performance over periods ending 31 January 2026
| 3 months(%) | 6 months (%) | 1 year (%) | 3 years(%) | 5 years(%) | Since 31 Mar 191 (%) | 10 years(%) | |
|---|---|---|---|---|---|---|---|
| VNH NAV | (8.0) | 4.1 | (7.3) | 31.7 | 99.0 | 111.0 | 210.1 |
| VNH share price | (0.9) | 5.3 | (0.0) | 28.3 | 85.0 | 102.7 | 183.4 |
| VN All-Share | 2.0 | 14.3 | 23.8 | 41.7 | 63.9 | 80.9 | 208.0 |
| MSCI Emerging Markets | 4.9 | 19.6 | 30.4 | 44.9 | 32.3 | 65.8 | 184.5 |
Source: Bloomberg, Marten & Co. Note 1) We are using the 31 March 2019 as a cut off for when VNH’s board and manager had completed their remedial measures (largely corporate governance- and investment management-related) as part of the major overhaul that was undertaken to address failings on the part of the previous board and investment manager (see page 4 of our December 2019 note for more details of these).
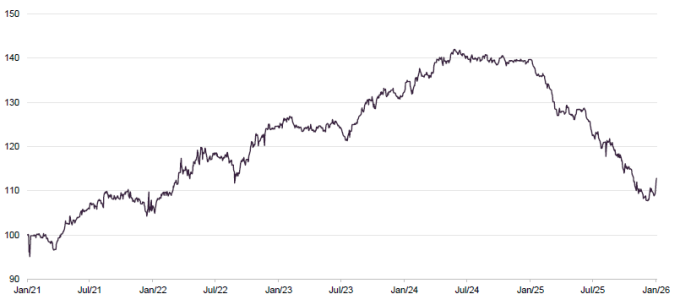
As Figure 17 shows, VNH has underperformed the VNAS recently, which appears to have contributed to lower longer-term relative returns. The manager attributes this primarily to the lack of exposure to Vingroup, as discussed above. The manager notes the extreme valuation at which Vingroup trades. It appears likely that Vingroup’s rapid rise, which Figure 5 shows has already stalled, may reverse, which could benefit VNH’s relative performance.
That relative performance change is evident in the period from February 2025 onwards.
Figure 17: VNH’s NAV performance relative to the VN All-Share over five years to 31 January 2026
Source: Bloomberg, Marten & Co
Premium/(discount)
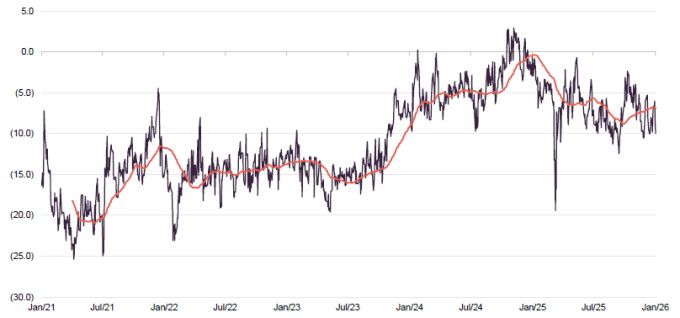
Over the 12 months to the end of January 2026, VNH traded in a discount range of 0.7%–19.4% and averaged 6.8%. As at 10 February 2026, VNH was trading on a discount of 8.2%.
VNH’s board has stated that it aims to keep the discount tight with the intention of re-expanding the company by issuing shares at a premium if investor demand increases. The company issued a small amount of stock in January 2025.
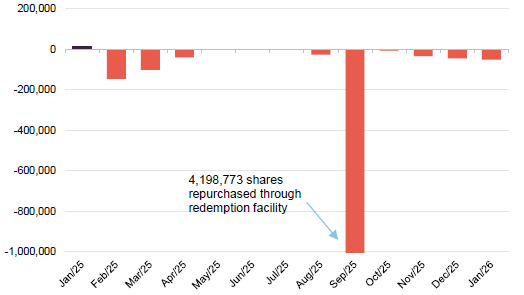
In addition to regular share buybacks, VNH operates an annual redemption facility. This was announced towards the end of 2023 and first implemented in September 2024, when about 12% of the issued share capital was redeemed. The company states that the facility has contributed towards keeping the discount tight. To be eligible to participate in the facility, shareholders must have held the stock that they want to redeem for at least six months, which the company states is intended to deter arbitrageurs from gaming it.
Figure 18: VNH premium/(discount) over five years
Source: Bloomberg, Marten & Co
In the 2025 redemption opportunity, investors holding approximately 4.2m shares (about 17.9% of VNH’s shares in issue) chose to redeem these shares.
Figure 19: VNH share repurchases over the past year
Source: Vietnam Holding
Previous publications
Readers interested in further information about VNH, such as investment process, fees, capital structure, life and the board, may wish to read our note – Cheap stocks, bold reforms, big ambitions – published on 29 April 2025, as well as our previous notes (details are provided in Figure 22 below). You can read the notes by clicking on them in Figure 22 or by visiting our website.
Figure 20: QuotedData’s previously published notes on VNH
Source: Marten & Co
IMPORTANT INFORMATION
Marten & Co (which is authorised and regulated by the Financial Conduct Authority) was paid to produce this note on Vietnam Holding Limited.
This note is for information purposes only and is not intended to encourage the reader to deal in the security or securities mentioned within it. Marten & Co is not authorised to give advice to retail clients. The research does not have regard to the specific investment objectives financial situation and needs of any specific person who may receive it.
The analysts who prepared this note are not constrained from dealing ahead of it but, in practice, and in accordance with our internal code of good conduct, will refrain from doing so for the period from which they first obtained the information necessary to prepare the note until one month after the note’s publication. Nevertheless, they may have an interest in any of the securities mentioned within this note.
This note has been compiled from publicly available information. This note is not directed at any person in any jurisdiction where (by reason of that person’s nationality, residence or otherwise) the publication or availability of this note is prohibited.
Accuracy of Content: Whilst Marten & Co uses reasonable efforts to obtain information from sources which we believe to be reliable and to ensure that the information in this note is up to date and accurate, we make no representation or warranty that the information contained in this note is accurate, reliable or complete. The information contained in this note is provided by Marten & Co for personal use and information purposes generally. You are solely liable for any use you may make of this information. The information is inherently subject to change without notice and may become outdated. You, therefore, should verify any information obtained from this note before you use it.
No Advice: Nothing contained in this note constitutes or should be construed to constitute investment, legal, tax or other advice.
No Representation or Warranty: No representation, warranty or guarantee of any kind, express or implied is given by Marten & Co in respect of any information contained on this note.
Exclusion of Liability: To the fullest extent allowed by law, Marten & Co shall not be liable for any direct or indirect losses, damages, costs or expenses incurred or suffered by you arising out or in connection with the access to, use of or reliance on any information contained on this note. In no circumstance shall Marten & Co and its employees have any liability for consequential or special damages.
Governing Law and Jurisdiction: These terms and conditions and all matters connected with them, are governed by the laws of England and Wales and shall be subject to the exclusive jurisdiction of the English courts. If you access this note from outside the UK, you are responsible for ensuring compliance with any local laws relating to access.
No information contained in this note shall form the basis of, or be relied upon in connection with, any offer or commitment whatsoever in any jurisdiction.
Investment Performance Information: Please remember that past performance is not necessarily a guide to the future and that the value of shares and the income from them can go down as well as up. Exchange rates may also cause the value of underlying overseas investments to go down as well as up. Marten & Co may write on companies that use gearing in a number of forms that can increase volatility and, in some cases, to a complete loss of an investment.